


Canadian Stock Market Today: TSX Futures Slip On First 2026 Factory Contraction Concern
The Morning Bull - Canadian Market Morning Update Tuesday, 3 Nov 2026
Canadian stocks look set for a cautious open, with sentiment softened by fresh evidence of domestic slowdown. The single driver today is Canada’s first manufacturing contraction of 2026, which puts the focus squarely on homegrown demand rather than overseas headlines.
The S&P Global Manufacturing PMI slipped to 49.6 in October, below the 50 line that separates expansion from contraction. Weak output and new orders, coupled with softer employment, point to pressure on both factory activity and export pipelines at the start of the week.
When manufacturing cools, pricing power often weakens and margins can come under strain, especially for businesses tied to cyclical demand and trade. That dynamic can feed into more cautious hiring plans and tighter capital spending. In turn, this can affect expectations for future earnings across domestically focused sectors.
The open now comes down to one question: Does this single soft PMI print signal a broader slowdown in Canadian activity, or will upcoming data on trade and employment later this week indicate a more resilient picture for the rest of 2026?
Stocks to Watch Before the Opening Bell
Ero Copper (ERO)
Ero Copper reported record third quarter 2026 results, with performance supported by higher copper and gold sales volumes. The miner cut net debt by about $100 million on strong free cash flow. Management reaffirmed consolidated copper production guidance and adjusted copper cost guidance to factor in inflation and foreign exchange hedge benefits. Watch how updated cost assumptions feed into cash generation.
Topaz Energy (TPZ)
Topaz Energy released third quarter 2026 figures that included 9% growth in average royalty production versus a year earlier. The business declared a fourth quarter dividend of $0.35 per share, which equates to a 4.5% trailing annualized yield. Guidance for 2026 was reconfirmed and management projects year end net debt between $425.0 million and $430.0 million. Income focused investors often track that leverage range closely.
Brookfield (BN)
Brookfield is planning an AI focused data center project of more than one gigawatt at a power station site in England. Phase one targets up to 100 megawatts in service by early 2028. Total spending could exceed £20b, with about £2.5b committed initially. The development links Brookfield directly to rising power demand from artificial intelligence infrastructure and future funding milestones will be key.
Top Movers
- Curaleaf Holdings (TSX:CURA) surged 9.01% after acquiring Boone Town Provisions, expanding its New Jersey dispensary footprint.
- Brookfield Asset Management (TSX:BAM) gained 6.65% as investors reacted to the completion of the all cash acquisition of LXP Industrial Trust.
- Eldorado Gold (TSX:ELD) climbed 5.39%.

Top Losers
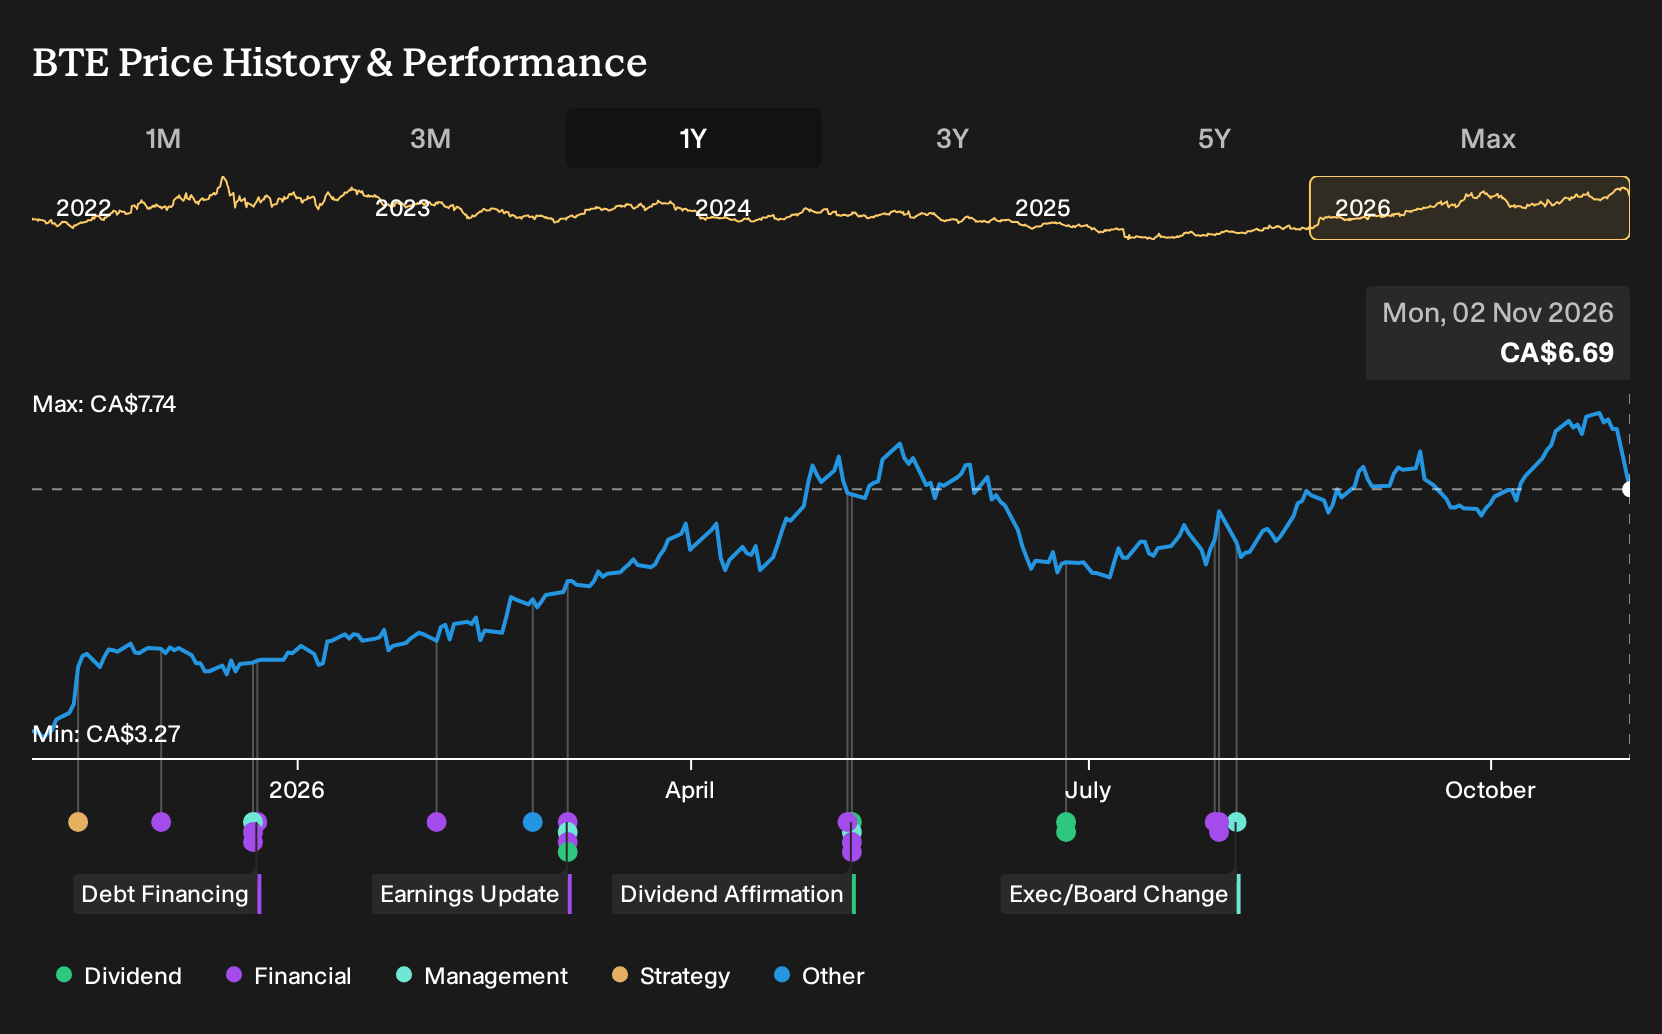
- Baytex Energy (TSX:BTE) declined 11.04%.
- Strathcona Resources (TSX:SCR) declined 10.33%.
- Precision Drilling (TSX:PD) declined 7.67%.
On The Radar
For Canadian investors, the next few sessions hinge on fresh trade and jobs data at home, backed up by a heavy run of TSX earnings and a key US labour report.
- Canada Balance of Trade, Wed 4 Nov. The prior surplus sat at C$4.2b, with consensus near C$4.1b. A softer surplus than that range would underline the PMI weakness and may pressure the loonie alongside exporters tied to US demand.
- Canadian labour market pack, Fri 6 Nov. Unemployment is forecast at 6.5% with employment expected to rise 13,600 after a drop of 68,300. A weaker hiring rebound would reinforce concerns around domestic consumption and rate sensitivity across TSX consumer and financial stocks.
- Canada Ivey PMI, Fri 6 Nov. The index previously printed 58.2 with consensus at 58. A clear step below that mark would signal that October’s 49.6 manufacturing PMI softness is broadening beyond factories into wider business activity.
- Canadian energy and utilities earnings cluster, Thu 5 to Fri 6 Nov. Results from TC Energy, Pembina Pipeline, Canadian Natural Resources, Enbridge and others will put the focus on cash flow durability and capital spending plans across Canada’s pipeline and upstream complex.
- North American jobs data twin peak, Wed 4 to Fri 6 Nov. US ADP and Friday’s Non Farm Payrolls, with payrolls forecast at 65,000 and unemployment at 4.2%, will feed into US rate expectations that often move the US$ and Canadian dollar together.
Sector & Industry Watch
Materials: Weak week as PMI flashes warning
Materials has fallen over the past 7 days and slipped more over the last month, leaving the sector down year to date despite a positive 1 year return. The soft Canadian Manufacturing PMI points to cooler factory demand, which matters for chemicals, packaging and construction tied producers in this group.
The single macro check here is Wednesday’s Canada trade balance, since softer export momentum for industrial goods would reinforce that more cautious backdrop.
Metals and Mining: Share pullback while projects keep moving
Metals and Mining has declined over the last week and month and remains down year to date, even with a positive 1 year result. Company newsflow stays busy, from Ero Copper’s record quarter to a wave of gold and battery metal drilling updates, which keeps long dated production stories alive despite recent price weakness.
If you hold miners, focus on Wednesday’s Canada trade data, because any sign of softer resource exports can influence how investors treat higher cost or early stage projects.
Real Estate: Rate sensitive but deals still printing
Real Estate is down over the past week, year to date and 1 year, with only a small 30 day gain showing that pressure has eased but not disappeared. At the same time, transactions involving Morguard, Dream Industrial REIT, Canadian Apartment Properties REIT and others show apartments and industrial properties are still changing hands, which feeds directly into asset values and refinancing terms.
For REIT and property service investors, Friday’s Canadian jobs report is the key release, because weak employment trends can affect occupancy, rent growth and retail traffic that support distributions.
Energy and Oil and Gas: Strong year, income theme in focus
Energy and Oil and Gas have inched higher over the past week and month and show some of the strongest 1 year and year to date gains on the TSX sector list. Recent results from Gibson Energy, Rockpoint Gas Storage, Topaz Energy and International Petroleum highlight busy activity in pipelines, storage and royalties, which links closely to dividends, buybacks and drilling plans.
The main swing factor remains weekly US crude inventory numbers, since a sharp build or draw can move oil prices quickly and reset sentiment toward Canadian producers and midstream stocks.
Financials and Banks: Strong 12 month run, credit in focus
Financials and Banks have delivered solid 1 year and year to date gains, while 7 day moves have been relatively muted as the sector catches its breath. Activity from Brookfield, Brookfield Asset Management, National Bank, TD, Royal Bank and Laurentian’s portfolio sale shows how deals, cards and brand consolidation continue to matter for fee income and balance sheet mix.
If you own Canadian lenders or diversified financial stocks, Friday’s Canadian unemployment and employment figures are the key risk check, since labour trends feed straight into loan growth, credit losses and mortgage demand.
Where Are The Opportunities Now?
If income is the part of today’s TSX story that matters most to you, start with this list of 3 dividend fortresses while yields stay front and centre for Canadian investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com