


Earnings And Renewable Fuel Deal Might Change The Case For Investing In Phillips 66 (PSX)
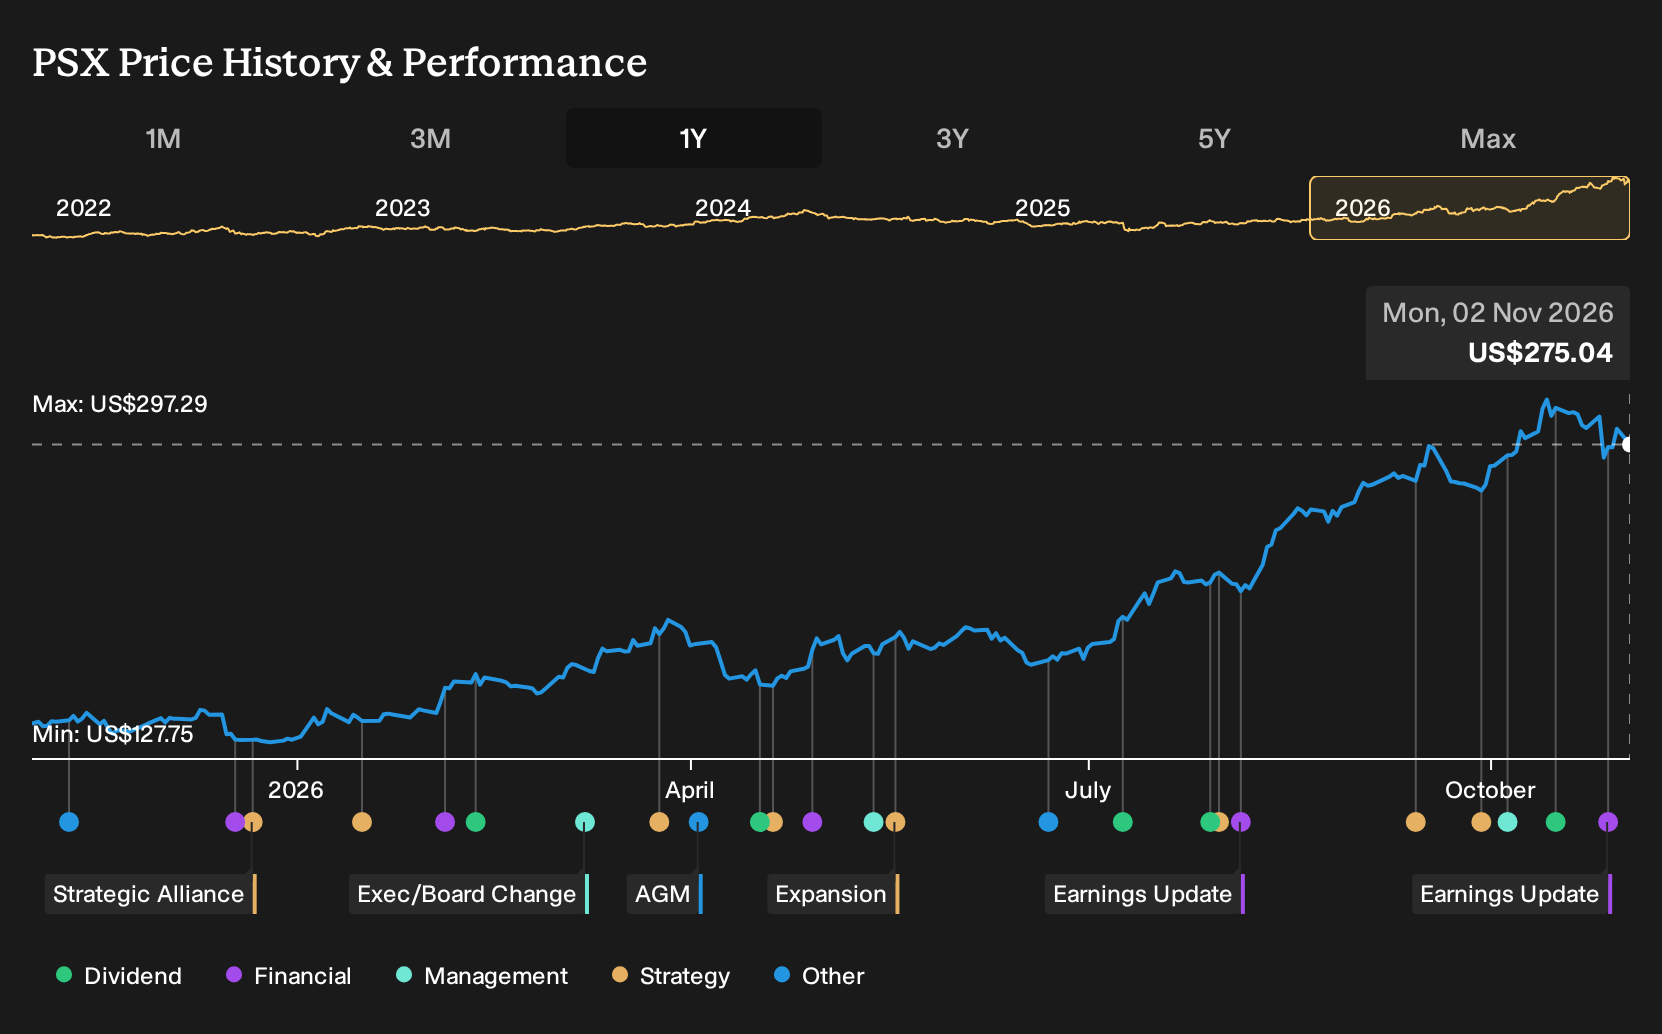
- Phillips 66 reported third quarter 2026 revenue of US$51,506 million and net income of US$5,616 million, with basic EPS from continuing operations of US$14.14, along with stronger nine month figures through September 30, 2026.
- A long term used cooking oil supply deal with Restaurant Technologies supports renewable diesel and sustainable aviation fuel production at the Rodeo Renewable Energy Complex, linking Phillips 66's earnings profile more closely to developments in lower carbon fuels.
- Next, attention will turn to how Phillips 66's investment narrative is shaped by this earnings performance and the renewable feedstock agreement.
Scan stocks that are following similar lower-carbon and earnings storylines by checking the hand picked list of solid balance sheet and fundamentals (24 results), which highlights companies that resemble Phillips 66's mix of cash generation and energy transition exposure.
Phillips 66 Investment Narrative Recap
To back Phillips 66 as a shareholder, you need to be comfortable with an integrated energy business that leans heavily on refining, fee based midstream and chemicals to fund steady cash returns while gradually building renewables. The third quarter numbers, including US$5,616 million of net income and US$14.14 basic EPS, reinforced that the current profit engine is intact.
The key short term catalyst remains execution on midstream growth and ongoing refinery cost reductions, since both support earnings resilience if crack spreads soften. The main risk is still operational or derivative related hits that absorb cash and disrupt this program. The latest earnings themselves do not change that risk reward balance in a major way.
The used cooking oil agreement with Restaurant Technologies is the most relevant operational update around this earnings print. It links Phillips 66's Rodeo Renewable Energy Complex more tightly to a domestic feedstock source for renewable diesel and sustainable aviation fuel, which matters for reliability as lower carbon fuel markets evolve.
For you as an investor, that contract speaks directly to future catalysts rather than quarter to quarter swings. Consistent feedstock helps Rodeo work toward its EBITDA ambitions and diversifies the business mix away from traditional refining. Execution risk shifts toward successfully running and scaling these renewable operations while managing regulatory credit markets and potential cost swings in collected used oil.
Phillips 66's narrative projects US$138.4b revenue and US$9.6b earnings by 2029. This is based on an assumed annual revenue decrease of 3.1% and requires an earnings increase of about US$2.5b from US$7.1b today.
Uncover why Phillips 66's fair value indicates a 4% potential upside to its current price before other investors close that discount.
Exploring Other Perspectives
Some of the lowest Phillips 66 analysts focus on the risk that heavy capital projects underdeliver. Before this earnings and used cooking oil deal, they were working off revenue projections of about US$122.6b and earnings near US$9.8b by 2029, paired with a much lower assumed P/E. That more cautious story could shift as new information is incorporated.
Explore 2 other Phillips 66 fair value estimates, including one that suggests it could be worth just $285.74.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Phillips 66 research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Phillips 66. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Phillips 66's overall financial health at a glance.
Looking for more Phillips 66 style investment ideas?
If the Phillips 66 story has you thinking about balance sheets, cash generation and risk, it can help to compare it with other companies that show similar traits. A few focused screeners on Simply Wall St can quickly surface stocks that fit the kind of profile you are searching for.
- For investors who want to focus on quality at a discount, scan a curated set of companies with stronger fundamentals and pricing appeal using the 34 high quality undervalued stocks.
- If capital preservation matters just as much as upside, narrow your research to businesses with steadier risk profiles through the 29 resilient stocks with low risk scores.
- When you want both resilience and financial strength, broaden your watchlist with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com