


Affirm Holdings (AFRM) Lands New Retail Deals, Is It Still Undervalued?
Affirm Holdings (AFRM) is back in focus after fresh partnerships with Sur La Table and an exclusive multi-year tie up with Sam’s Club, just as Wall Street raises near term earnings and revenue expectations.
Recent price action suggests that enthusiasm is building again around Affirm Holdings, with a 7 day share price return of 5.89% and a 30 day gain of 3.97%, even though the 90 day share price return declined 5.81% and the year to date move is slightly lower. Over a longer window, the 1 year total shareholder return of 2.08%, the very large 3 year total shareholder return of about 3.4x, and a 5 year total shareholder return that declined 54.96% paint a picture of a stock where sentiment has swung sharply over time. The latest retail partnerships and higher earnings expectations are now feeding into a renewed debate about future growth and risk.
Spot emerging buy-now-pay-later momentum early by comparing Affirm Holdings with a hand picked 19 high quality undiscovered gems.Bulls point to Affirm Holdings’ fresh retailer deals and higher analyst forecasts, while bears highlight its uneven long term return profile. Which case looks stronger once you stack those stories against today’s valuation?
Most Popular Narrative: 26% Undervalued
Against a last close of $73.58, the most followed narrative places Affirm Holdings' fair value at $99.23. The story leans toward upside but demands close attention to what is driving that gap.
Rapid growth and strong engagement with Affirm Card, an actively invested product moving toward high attach rates and greater offline usage, expands Affirm's addressable market beyond online retail, diversifies revenue streams, and drives higher frequency of transactions, which should accelerate GMV and contribute to margin improvement.
See why 53 investors see Affirm Holdings as 26% undervalued.
Result: Fair Value of $99.23 (UNDERVALUED)
Still, the bullish Affirm Holdings story can unravel if a key merchant partnership expires or if rising competition and credit losses squeeze its unit economics.
Find out about the key risks to this Affirm Holdings narrative.
Another View On Affirm Holdings: Our DCF Model Says Overvalued
Analysts see upside for Affirm Holdings based on earnings forecasts and price targets, but the Simply Wall St DCF model points the other way. On that cash flow view, the shares trade above an estimated value of $61.37, which frames the stock as overvalued rather than discounted. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
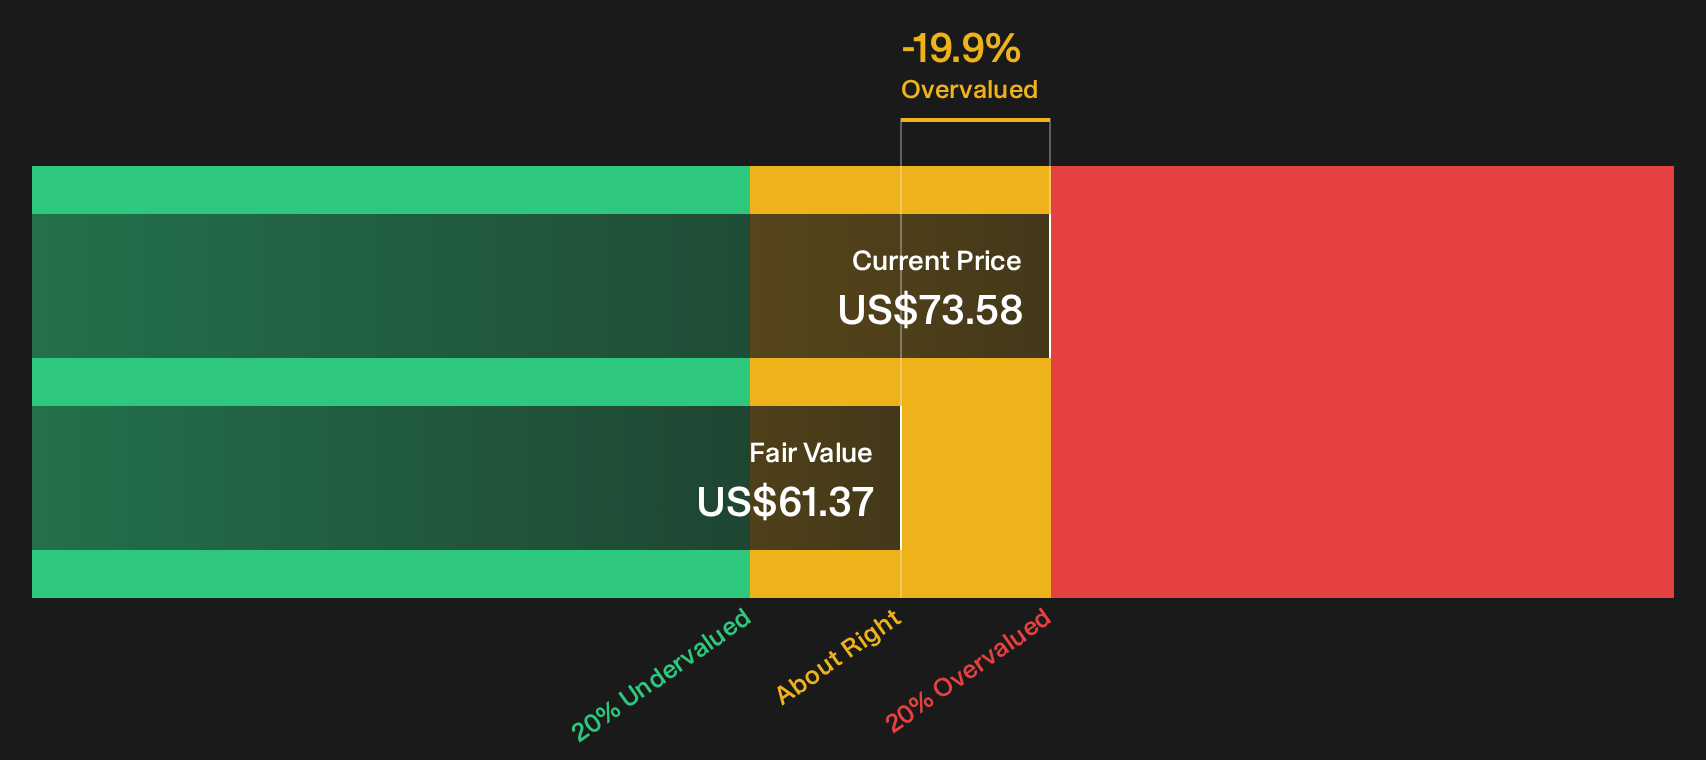
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Affirm Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Affirm Holdings feels familiar, treat that as your cue to move quickly and test the numbers yourself using our breakdown of 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Affirm Holdings?
Do not stop at Affirm Holdings. Use the Simply Wall St Screener to quickly surface fresh opportunities that fit your goals before everyone else spots them.
- Target value first and hunt for resilient businesses trading below their implied worth through our curated 34 high quality undervalued stocks.
- Prioritise capital protection and filter for companies with sturdier finances using the focused list of solid balance sheet and fundamentals (24 results).
- Lock in potential income streams and scan for higher yielding payers with staying power via the concentrated 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com