


Is Replimune Group (REPL) Above Fair Value After A 119% Jump?
Replimune Group has seen its share price climb sharply in 2026, which puts a spotlight on a simple question for anyone looking at the stock today. Is the latest jump in Replimune Group justified by what its balance sheet and book value currently support?
- With the stock up 119.0% year to date, a lot now rests on whether that market enthusiasm lines up with the value of the assets backing each share.
- The early commercial uptake of TUDRIQEV and wider guideline inclusion may support expectations for stronger future cash generation, which can change how investors weigh the company against its book value and the industry average.
- Your read on Replimune Group is one view; the desks covering it have another. See what analysts think Replimune Group's shares could be worth.
The issue now is whether Replimune Group's recent price level makes sense when stacked against its book value compared with the industry average.
If you want a wider watchlist of asset focused opportunities alongside Replimune Group, a targeted screen built around 34 high quality undervalued stocks can be a useful next step in your research.
Is Replimune Group Getting Expensive on Book Value?
P/B fits Replimune Group because the business is still loss making and tangible capital on the balance sheet is one of the cleaner anchors for today’s price.
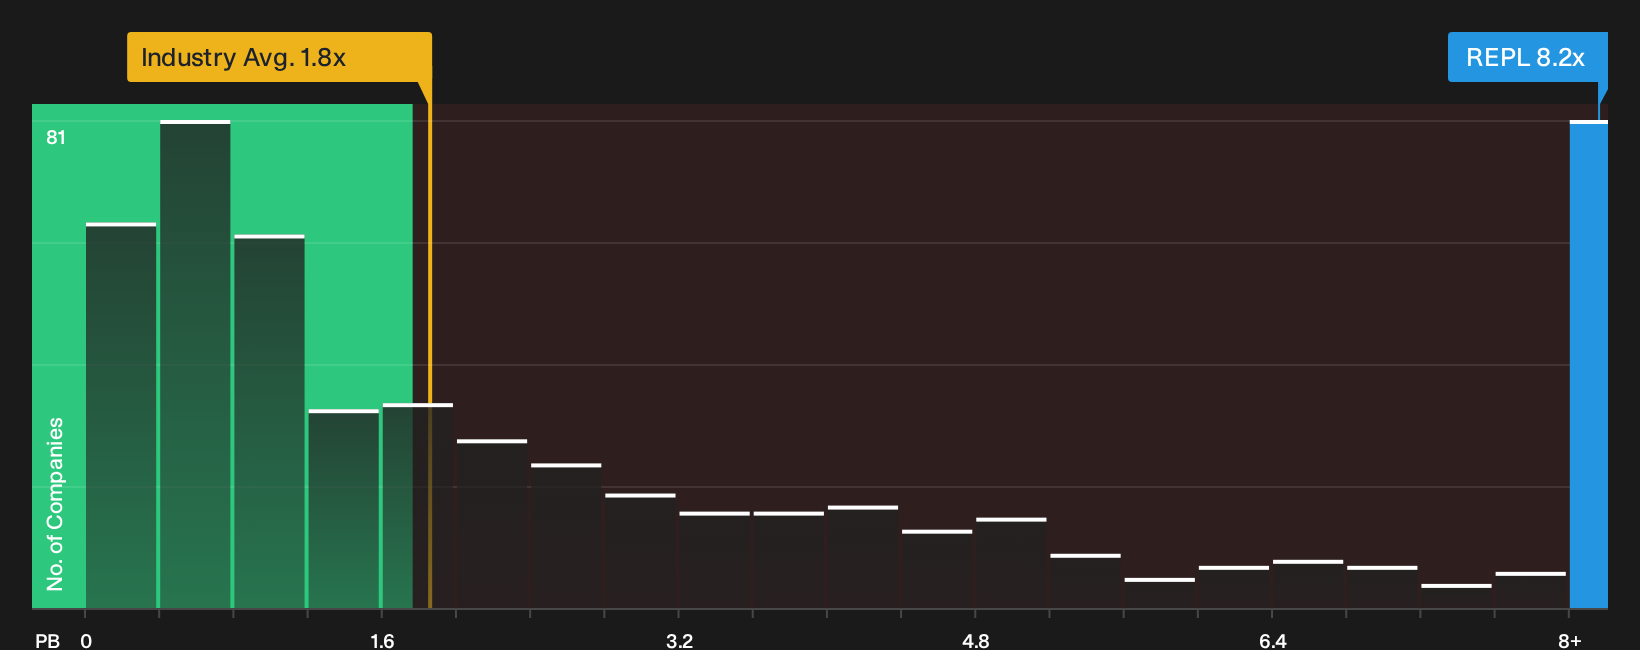
On this yardstick, Replimune Group trades at about 9.0x P/B, which is well above the Biotechs sector average of roughly 1.8x and also ahead of the peer group around 5.6x. That gap signals an overvalued read on this metric, and the size of the premium suggests the model is heavily penalising the current losses and risk profile, so the figure works more as a warning flag than a precise target. Despite the early traction for TUDRIQEV and guideline inclusion lifting interest in the story, the P/B multiple still prices the stock on much richer terms than most similar biotech listings. Explore the numbers behind Replimune Group's P/B valuation.
The Replimune Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that P/B puzzle for Replimune Group and spell out what mix of future growth, profitability and earnings power would need to play out for the current valuation to look too high or too low. Each narrative links its implied number to a clear view on how Replimune Group's revenue trajectory, margin profile and risk outlook could evolve, which gives you something concrete to compare against as fresh results come through.
Community views on Replimune Group are split between those who think the new melanoma franchise is not fully appreciated and those who think the risks already match the current tag.
Bull case: roughly fairly valued
"The FDA accelerated approval of TUDRIQEV in combination with nivolumab for unresectable advanced cutaneous melanoma that progressed on a PD-1 regimen opens access to an estimated 10,000 US patients each year…"
Discover why this Narrative puts Replimune Group at roughly fairly valued.
Bear case: 39% overvalued
"Now that stockholders have approved an increase in authorized shares from 150,000,000 to 300,000,000 to support launch and trial funding, the expanded capacity for equity issuance points to a higher probability of dilution funded spending…"
Explore why this Narrative puts Replimune Group at 39% overvalued.
One more Replimune Group check that sits beyond the share price chart
Before moving on, it is worth asking who is steering Replimune Group and how their pay packets line up with the risks and rewards you are weighing today. See who runs Replimune Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com