


What Alector Doubters Missed
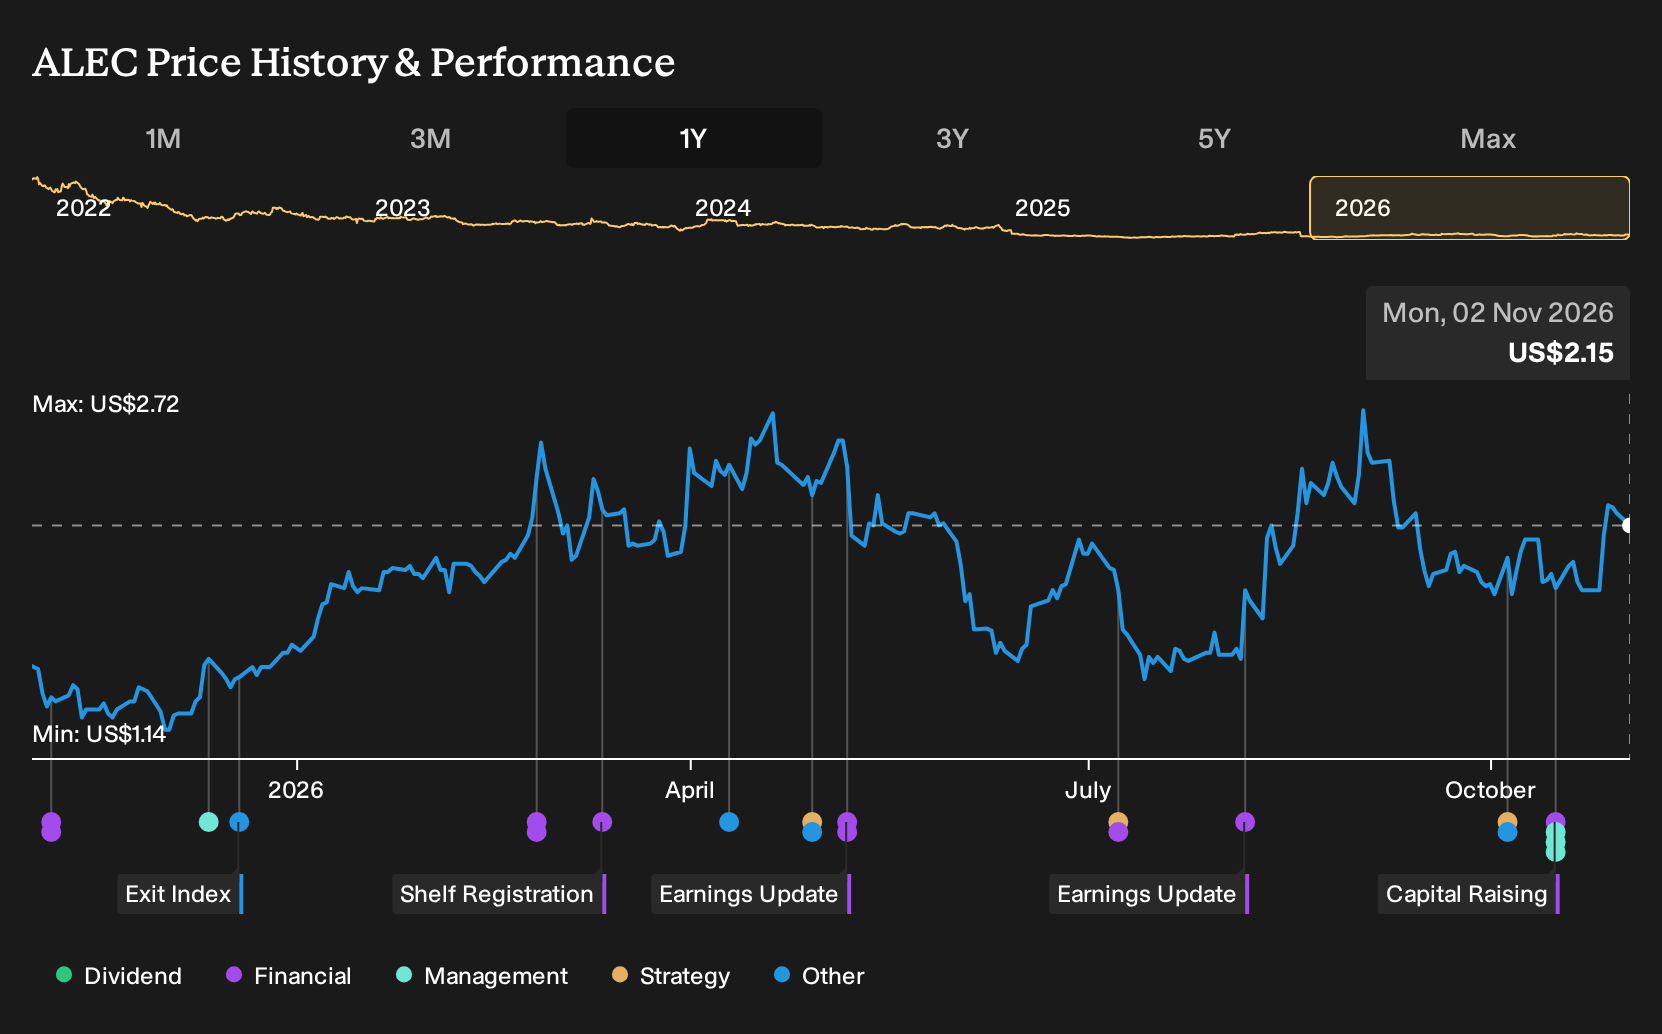
If Alector was on your watchlist instead of in your portfolio, the payoff probably feels like a missed call. Investors who held Alector over the past year are up 49.3%, including dividends. That result arrived alongside a period where quarterly revenue moved to US$3.32 million while losses narrowed to US$22.99 million. The obvious question is simple. Back on 2 November 2025, what might have signalled that analyst assumptions about a future 7.6x P/E on sharply higher earnings were worth taking seriously?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Alector has already moved. See which of 34 high quality undervalued stocks still trade below our estimates.
The Two Futures Alector Investors Had To Consider
The shares cost US$1.48 at the start of the period, and anyone looking at Alector then had to choose between two very different stories that both sounded plausible.
On the bullish side, one Narrative put Fair Value at US$3.83, with the case resting on revenue growth of 64.8% a year and profit margins shifting to 18.8% within three years. That view leaned heavily on latozinemab success and a pipeline that could, in theory, support a 7.6x future P/E assumption.
The bearish Narrative pointed to a Fair Value of US$1 and assumed revenue would decline 43.3% annually while the business moved only gradually toward a 14.2% margin and a much higher 65.8x future P/E assumption. This camp focused on the small FTD-GRN market, persistent losses, and the risk that ongoing R&D needs would force more dilution.
What The Results Changed For Alector
Alector’s most concrete update was financial. Total revenue moved from US$7.87 million in Q2 2025 to US$3.32 million in Q2 2026, which pushed against the bullish 64.8% growth story. Net loss narrowed from US$30.52 million to US$22.99 million, so profitability trended in the right direction but still fell short of the positive-margin scenario.
The clash between weaker top line and improving earnings showed where the bet really sat. The crucial assumption was rapid revenue expansion, not just shrinking losses. When you look at another biotech, check whether reported sales are tracking anywhere near the growth path that earlier forecasts implied.
What Alector’s Recent Run Leaves You Paying For
Alector now trades at US$2.15, after a 49.3% gain over the past year from US$1.48. The selected Narrative argues that its Fair Value sits above the current price, framed around the Alector Brain Carrier platform rather than any single late stage drug.
In that view, today’s valuation still does not fully credit the idea that ABC based programs could support a broader central nervous system franchise and future partnership economics.
"The current valuation suggests the market is pricing Alector cautiously despite the Genentech/Roche AL050 deal, the extended cash runway to around 2029, and research firms highlighting the company as a platform story rather than a single asset stock."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 37% below our estimate - convert a growing backlog of subsea projects into faster, higher margin contracts.
- Company 2 - 38% below our estimate - tie an extensive reserve base to higher cost infrastructure in politically sensitive regions.
- Company 3 - 36% below our estimate - tackle complex safety and regulatory challenges as clients adopt AI driven operational systems.
Those are three of them. See every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com