


Is Earnings Guidance Raise Altering The Investment Case For Teledyne Technologies (TDY)?
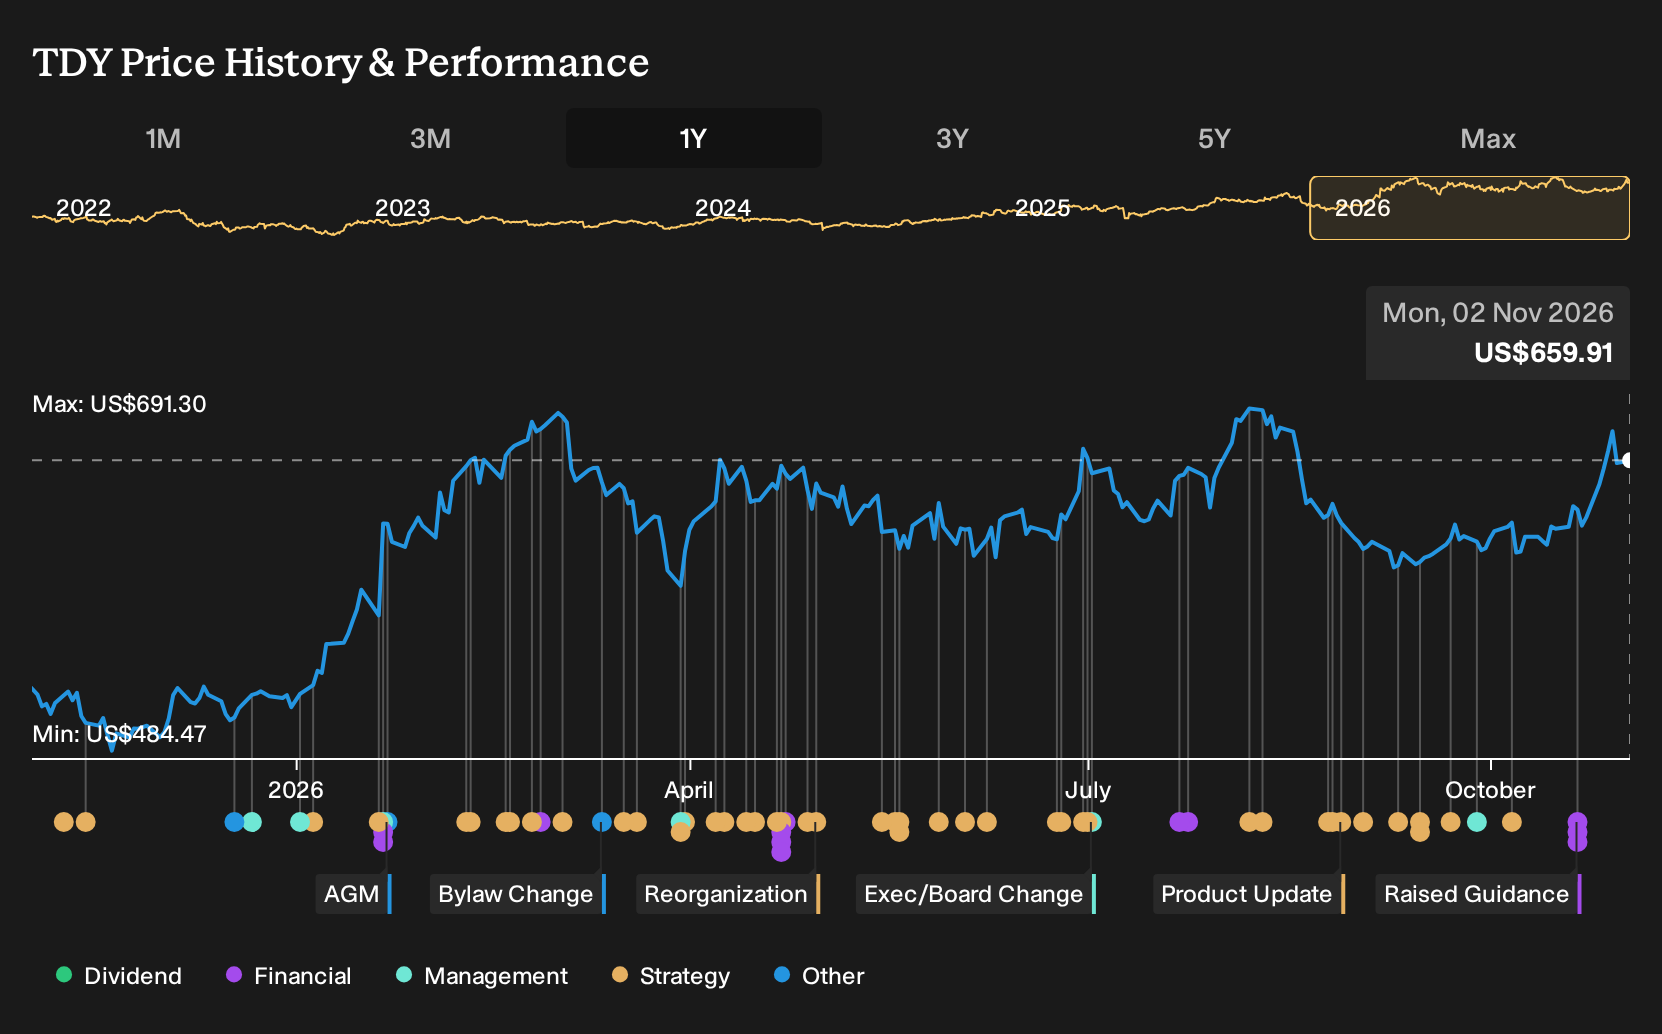
- Teledyne Technologies reported third quarter 2026 sales of US$1,684.9 million and GAAP diluted EPS of US$5.82, and raised full year 2026 GAAP diluted EPS guidance to a range of US$21.71 to US$21.87 from the prior range of US$20.73 to US$20.99.
- The combination of higher year-to-date sales and earnings and tighter full year guidance suggests Teledyne Technologies is operating with clearer visibility on demand, costs, and execution across its sensing and imaging businesses.
- The next step is to examine how this upgraded earnings outlook could influence Teledyne Technologies' existing investment narrative around backlog and margins.
Scan how Teledyne Technologies' guidance upgrade compares with other companies tightening their outlooks by reviewing the hand picked 29 resilient stocks with low risk scores in the market today.
Teledyne Technologies Investment Narrative Recap
To own Teledyne Technologies, you need to be comfortable with a long pipeline of high reliability sensing and imaging programs and a management team focused on steady margin work rather than headline grabbing swings. The raised full year EPS guidance tightens the near term picture and mainly reinforces that current execution on backlog and costs is tracking close to plan.
The key short term catalyst remains how well Teledyne converts its roughly US$5b funded backlog into shipments without supply issues or cost spikes in components and specialty materials. Margin dilution from mix shifts, especially toward defense and any acquired lower margin operations, still appears to be a significant operational risk.
The most relevant update is management’s higher 2026 GAAP diluted EPS guidance to a range of US$21.71 to US$21.87, alongside a fourth quarter EPS outlook of US$5.68 to US$5.83. These figures are reported on top of third quarter GAAP diluted EPS of US$5.82, with US$1,684.9 million of sales and US$272.8 million of net income.
For you as an investor, that cluster of figures ties directly into the existing catalyst list. Recent earnings and tighter guidance relate to execution in defense sensing, Digital Imaging and healthcare related imaging, but do not remove the focus on Teledyne Technologies to keep expanding operating margins, integrate any acquisitions cleanly, and manage potential mix drag from lower gross margin programs.
Teledyne Technologies' current analyst narrative points to US$7.4b of revenue and US$1.2b of earnings by 2029, based on forecast yearly top line growth of 5.2%. That profile assumes earnings today of US$974.8 million and implies an earnings increase of about US$225 million by the 2029 estimate year.
Uncover how Teledyne Technologies' fair value indicates a 15% potential upside to its current price before the discount narrows.
Exploring Other Perspectives
Across 2 fair value estimates from the Simply Wall St Community, Teledyne Technologies sits in a tight band from about US$631.5 to US$758.1, with views spread across the full range. Those retail investors have not yet reflected the raised guidance. At the same time, supply chain pressure and potential margin dilution could still reshape how the business is priced. Opinions differ widely, so you may want to weigh several of these viewpoints before making your own call.
Explore another Teledyne Technologies fair value estimate, including one that suggests it could be worth just $631.50.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Teledyne Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teledyne Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teledyne Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Teledyne Technologies?
If you want to stress test your view on Teledyne Technologies against other opportunities, a quick sweep through the Simply Wall St Screener can help you see how different business models, balance sheets, and income profiles stack up side by side.
- For potential mispriced opportunities with quality traits, compare Teledyne Technologies against a curated set of 34 high quality undervalued stocks that combine strong fundamentals with room for the market to reassess their pricing.
- If durability matters more to you than headline growth, line up Teledyne Technologies next to a list of solid balance sheet and fundamentals (24 results) to see which businesses look better equipped to handle shocks.
- Investors hunting for future leaders earlier in their journey can scan a 19 high quality undiscovered gems and cross check where Teledyne Technologies fits on quality, scale, and risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com