


Murphy USA (MUSA) Earnings Put Fair Value Back In Focus Following Expansion Plans
How Murphy USA’s latest earnings reset the conversation for investors
Murphy USA (MUSA) put fresh numbers on the table with its third quarter 2026 earnings, pairing higher revenue and net income with a bigger dividend and an ambitious store expansion pipeline.
Murphy USA’s share price has pulled back in the short term, with the stock down 4.1% on a 1-day basis and 13% over 90 days. At the same time, the year-to-date share price return of 26.6% and a 5-year total shareholder return of 196.3% point to longer term momentum. Recent earnings, dividend increases and the expanded store pipeline now contribute to a more finely balanced debate about upside potential versus execution risk.
Scan how Murphy USA compares with other fuel and retail operators by reviewing a hand picked list of solid balance sheet and fundamentals (24 results) that could handle the same kind of volatility.
Earnings and dividends point to a strong Murphy USA franchise. After a sharp pullback from a US$513 share price, the real question is whether that strength is already fully reflected in the valuation.
Most Popular Narrative: 17% Undervalued
Against Murphy USA’s last close of $513, the most followed narrative pegs fair value closer to $617.80. This shifts the focus to whether current earnings power and margins can genuinely support that gap, or if expectations have run ahead of what the business can sustainably deliver.
Structurally higher all in fuel margins, supported by guidance of about $0.35 per gallon for the back half of 2026 and evidence of rational pricing and higher breakeven levels for marginal retailers, could keep Murphy USA’s gross profit and net margins above prior cycles.
Consistent contribution from the integrated fuel supply chain, with controllable economics in the range of $0.02 to $0.03 per gallon and leverage to periods of tight physical supply and price volatility, creates an additional earnings stream that can support overall margin resilience.
See why 12 investors see Murphy USA as 17% undervalued.
Result: Fair Value of $617.80 (UNDERVALUED)
Still, this narrative can unravel if structurally higher fuel margins prove temporary or if insider selling and any further valuation premium start to pressure Murphy USA’s P/E.
Find out about the key risks to this Murphy USA narrative.
Another view on Murphy USA’s valuation
A second lens on Murphy USA comes from simple earnings multiples rather than narrative fair value estimates. The stock trades on a P/E of 14x, which is cheaper than the US Specialty Retail industry at 18.1x and slightly below peer levels at 14.9x, yet above a fair ratio of 12.2x that the market could move toward. That mix of discount and premium raises a practical question for you as an investor: Is the current price a cushion or a warning sign if earnings slip from here?
To see how that earnings multiple gap might resolve, including what a move toward the 12.2x fair ratio could mean in practice, review the See what the numbers say about this price — find out in our valuation breakdown..
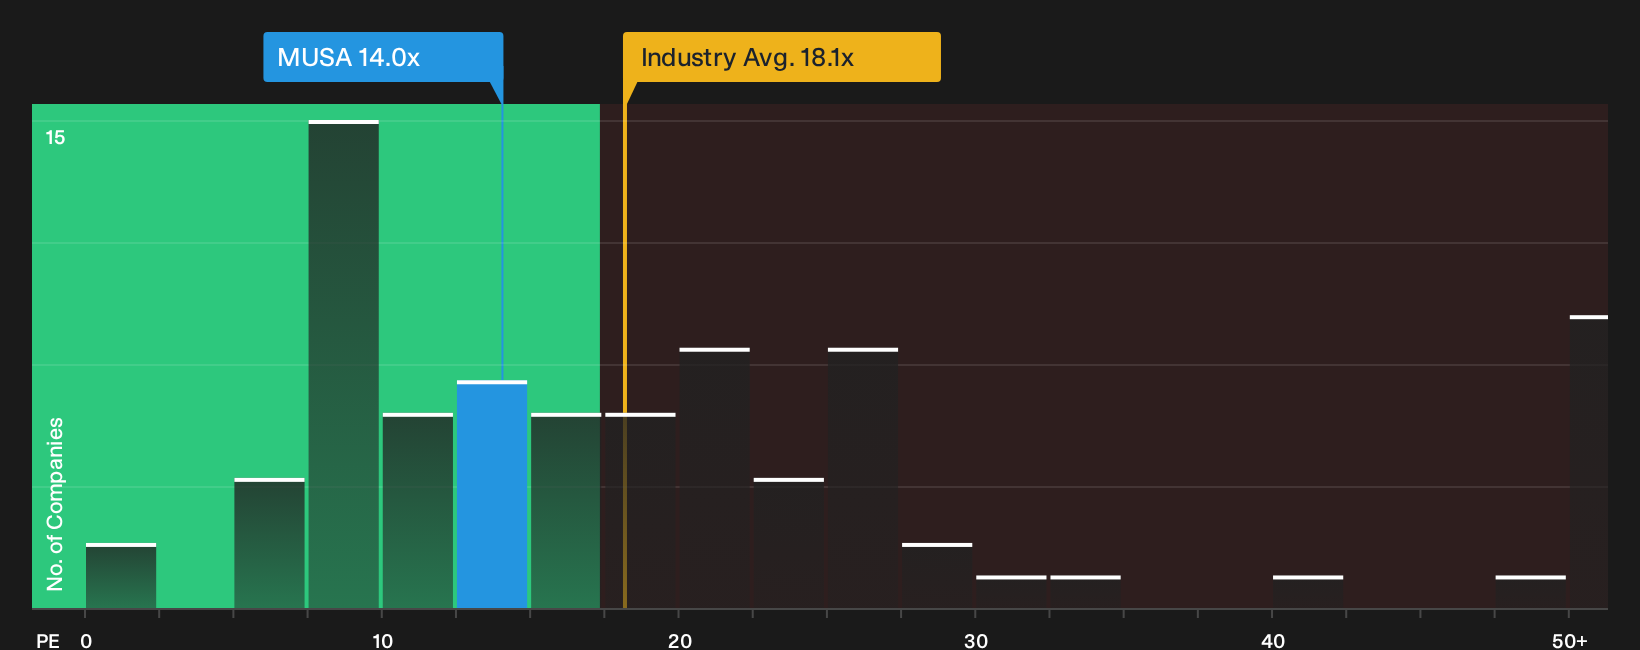
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murphy USA for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Murphy USA’s valuation and earnings quality are clear. Consider acting promptly, reviewing the numbers independently, and weighing both sides of the story with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Murphy USA?
If you stop with Murphy USA, you miss the chance to spot fresh opportunities other investors may overlook, diversify your watchlist, and sharpen your edge.
- Target stability first by scanning a 29 resilient stocks with low risk scores that could help you focus on businesses with steadier risk profiles.
- Hunt for value by reviewing a 34 high quality undervalued stocks that may highlight companies combining solid fundamentals with appealing pricing.
- Boost your income potential by checking a 4 dividend fortresses that focuses on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com