


How Investors May Respond To StorageVault Canada Stock After Losses Deepen
- StorageVault Canada Inc. reported third quarter 2026 revenue of C$94.24 million with a net loss of C$6.38 million, and at the same time raised its fourth quarter dividend by 0.5% to C$0.003051 per share, following results released on October 21, 2026.
- The shift from net income in the prior year to losses for both the quarter and the first nine months highlights pressure on StorageVault Canada's profitability even as revenue figures rise.
- Next, the focus turns to how StorageVault Canada's swing to losses, alongside a token dividend increase, could reshape its broader investment narrative.
What Is StorageVault Canada's Investment Narrative?
The StorageVault Canada story still hinges on whether you believe in a capital intensive, asset heavy self storage platform that leans on steady demand and pricing discipline while working through current losses. The latest quarter shows revenue of C$94.24 million but a net loss of C$6.38 million, which keeps the spotlight on execution, cost control, and interest expense rather than headline growth. A very small 0.5% dividend bump to C$0.003051 per share reads more like a signaling move than a cash return catalyst in the near term.
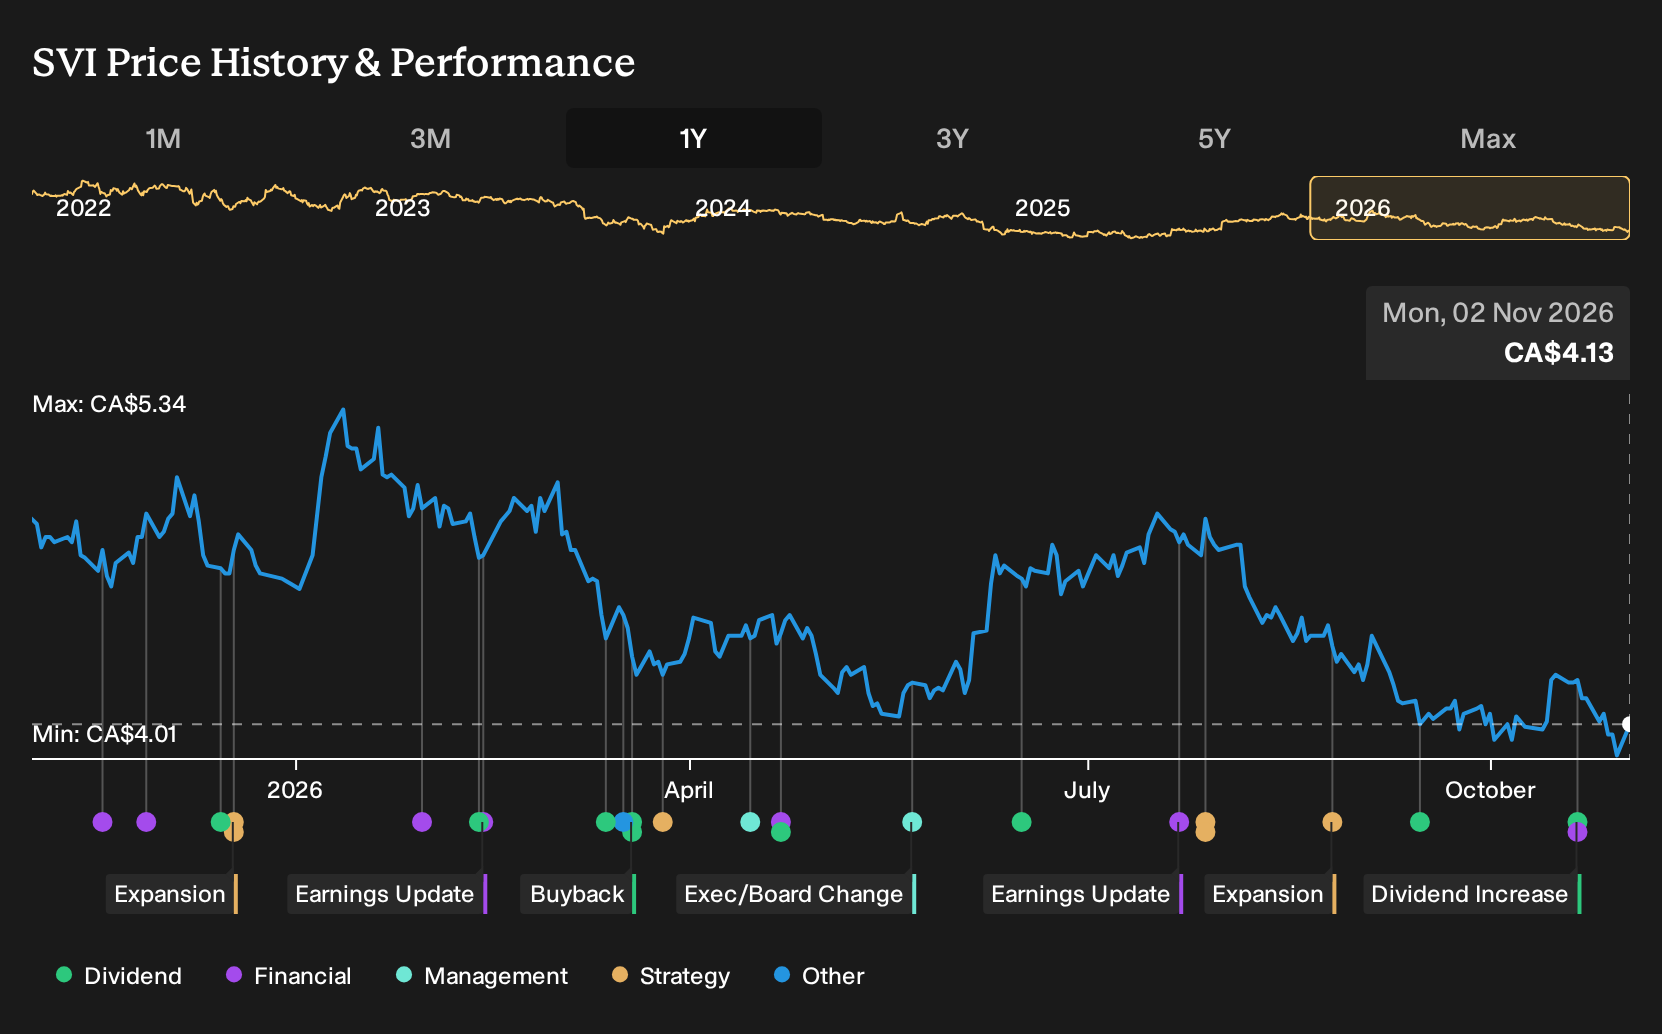
In the short term, the swing to losses and the share price decline over the past year put profitability squarely in focus for StorageVault Canada. Forecast revenue growth of around 5.4% a year and analyst targets above the current price give some investors a reason to be patient, although the stock already screens as expensive on P/S compared with peers and the wider Canadian real estate group. The key question now is whether management can translate that top line into sustainable earnings while carrying higher risk funding and ongoing investment needs for sites, portable units, and records facilities.
Even so, there is a separate pressure point around StorageVault Canada that does not show up in the headline numbers and ...
There's only one way to know the right time to buy, sell or hold StorageVault Canada. Head to Simply Wall St's company report for the latest analysis of StorageVault Canada's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your StorageVault Canada research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for StorageVault Canada. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StorageVault Canada's overall financial health at a glance.
Looking For More Investment Ideas Beyond StorageVault Canada?
Once you have formed a view on StorageVault Canada, it often helps to compare it with other businesses that offer different mixes of income, balance sheet strength, and risk. The Simply Wall St Screener can help you line up those options quickly instead of sifting through tickers one by one.
- For investors who want potential value combined with quality fundamentals, review a curated set of 5 high quality undervalued stocks that might warrant a closer look.
- If capital preservation is high on your list, focus on companies that score well on stability measures through our 9 resilient stocks with low risk scores and see which ones fit your comfort level.
- Anyone hunting for income alongside robust finances can filter for a list of solid balance sheet and fundamentals (6 results) to spot candidates that pair distributions with sturdier foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com