


Patrick Industries Stock After Earnings Miss Has The Bull Case Changed?
- Patrick Industries reported third quarter 2026 results with sales of US$975.28 million and net income of US$21.06 million, with both basic and diluted earnings per share from continuing operations below the prior year.
- The nine month figures show relatively steady sales of US$3,014.15 million and net income of US$103.96 million, while earnings per share eased slightly, indicating pressure on profitability rather than demand.
- We now examine how Patrick Industries' softer third quarter earnings per share may reshape the broader investment narrative around the business.
Patrick Industries Investment Narrative Recap
To own Patrick Industries, you need to be comfortable with a business that leans on content per unit growth, aftermarket exposure and a larger non RV mix, while living with earnings that can still swing when volumes soften. The latest quarter fits that pattern. Sales were broadly steady, but earnings per share from continuing operations compressed, so execution on costs and mix matters more than ever.
In the short term, the key swing factor is whether management can keep margins from slipping further while RV and Marine shipments remain below pre 2019 levels. The main risk is that weaker RV retail and high working capital combine with the company’s existing debt load to restrain cash generation, which would limit flexibility around dividends, buybacks or faster deleveraging.
The most relevant reference point here is the planned merger with LCI Industries. The merger targets US$150 million of annual run rate cost synergies on roughly US$8.1b of combined revenue and about US$1b of adjusted EBITDA. Those numbers help explain why many investors focus on Patrick Industries as a platform story rather than a pure RV supplier.
Against the backdrop of softer third quarter earnings per share, that merger is both an opportunity and an execution test. Synergies rely on procurement and supply chain savings. Risk comes from sharing benefits with OEMs or seeing margins capped if affordability support for customers goes further than expected. Your view on the stock probably turns on confidence in that balance.
Patrick Industries Earnings Reset Through the Analyst Lens
Analysts frame Patrick Industries as a business that needs steady progress rather than a rapid overhaul. The current consensus builds on revenue rising by 3.6% a year over the next three years, while profit margins are expected to lift from 3.7% today to 5.2% over that same period. Those assumptions sit behind a forecast that earnings move from US$147.3 million today to US$229.9 million by around 2029, helped by share count reduction of about 3.48% a year and the planned merger benefits that need to come through without eroding pricing power.
On this view, the Patrick Industries story hinges on earnings quality catching up with the broader product and end market mix. Management is being measured against a path where the firm becomes more efficient on every dollar of revenue, not simply larger. The report uses a discount rate of 10.39% to pull those future cash flows back to today. This approach puts more weight on consistent execution of procurement savings, working capital discipline and aftermarket growth than on a sharp snapback in RV shipments or a sudden surge in Marine demand.
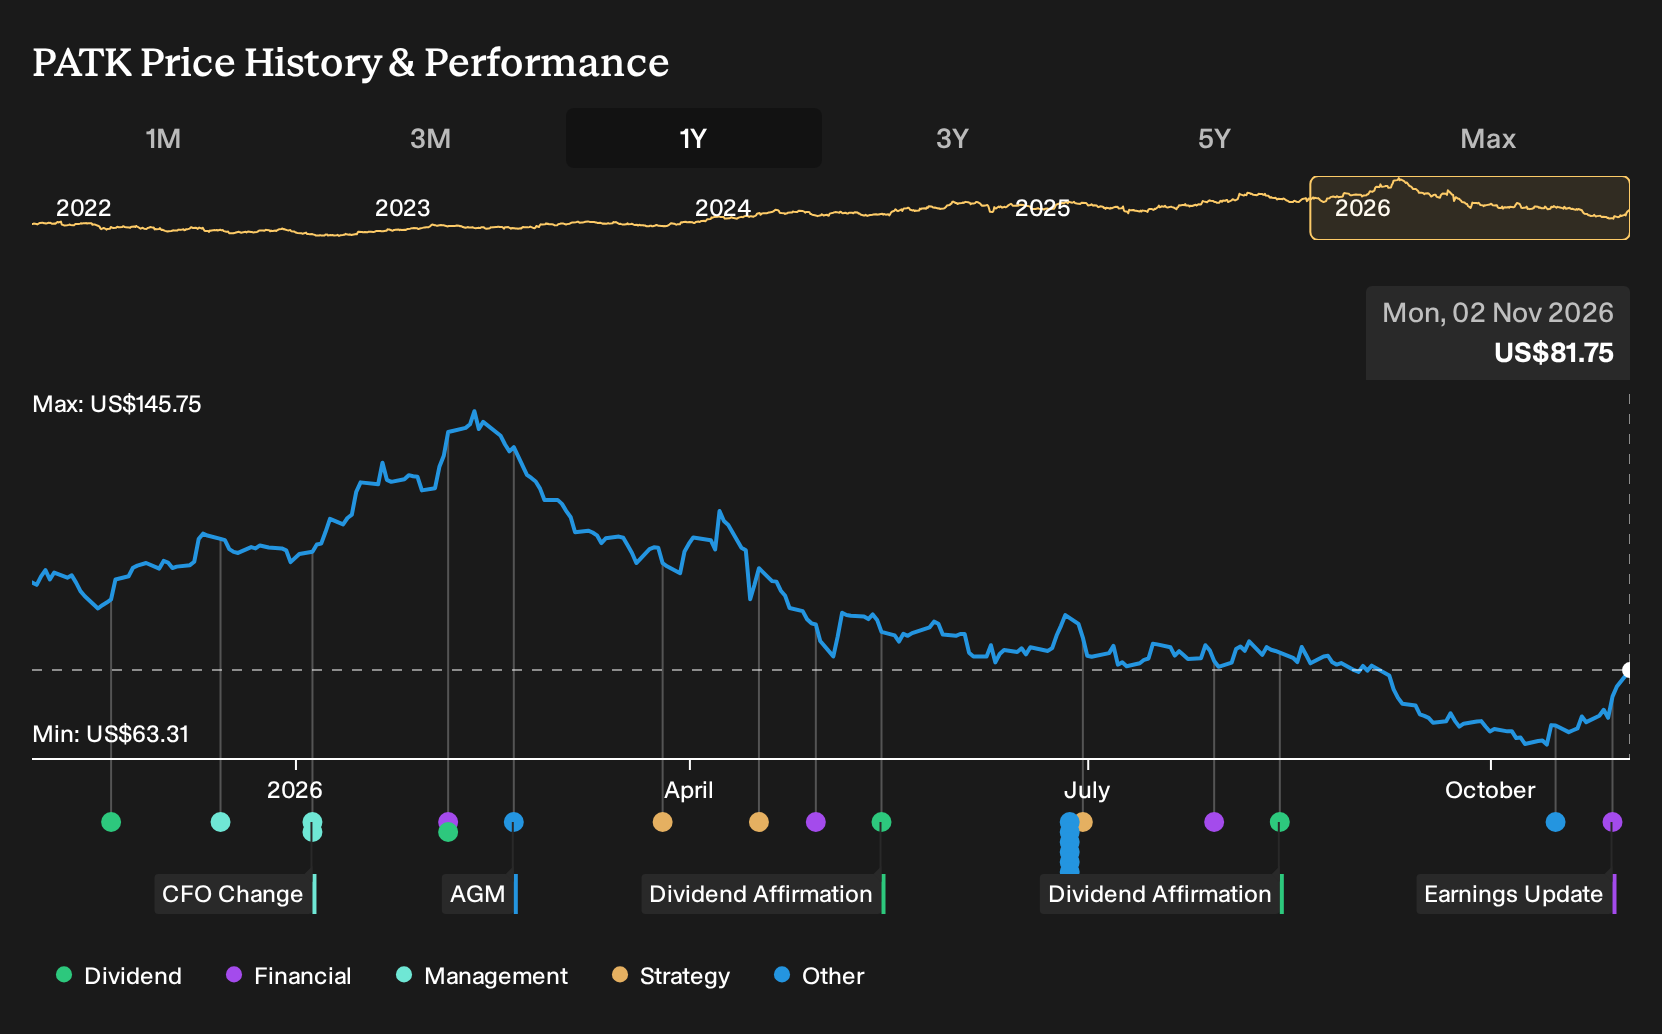
Valuation work in the consensus pack pulls these inputs together into a single reference point rather than a prediction. The current analyst price target sits at US$100.82 per share, compared with a recent share price of US$68.04, and is underpinned by the expectation that by 2029 Patrick Industries could be generating US$4.4b in revenue and US$229.9 million in earnings at a P/E of 17.0x. Targets span a wide range, with the most optimistic forecast at US$130.00 and the most cautious at US$68.00. It is therefore worth treating these as scenario markers and testing them against your own expectations for merger execution, end market volumes and margin resilience rather than as a single fixed outcome.
Patrick Industries' narrative projects US$4.4b revenue and US$229.9 million earnings by 2029. This assumes 3.6% yearly revenue growth and an earnings increase of about US$82.6 million from US$147.3 million today.
Uncover why Patrick Industries' fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a very different angle, focus on the bullish catalyst around the planned LCI merger. The most optimistic analysts were modelling roughly US$4.5b in 2029 revenue and US$252.5 million in earnings, which suggests a much stronger Patrick Industries story than the latest EPS miss. Use that range of opinions as a prompt to explore several possible paths from here.
Explore 3 other Patrick Industries fair value estimates, including one that suggests potential upside of as much as 110% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Patrick Industries research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Patrick Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Patrick Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Patrick Industries?
If Patrick Industries has sharpened your sense of what you want in a business, use that lens across the wider market. The Simply Wall St Screener can help you quickly sort through opportunities that better fit your comfort level on quality, balance sheet strength and risk.
- If capital preservation sits high on your list, start with a set of companies that pair resilience with lower risk profiles through the 29 resilient stocks with low risk scores.
- For investors who care most about strong finances and clean balance sheets, filter for businesses with sturdy fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Those hunting for mispriced quality can scan a curated pool of potentially underappreciated opportunities through the 34 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com