


Chaleit Holdings And 2 British Quality Stocks To Watch
Rising UK interest rates, with the Bank of England signalling caution on further hikes, have pushed many large cap favourites into the spotlight while smaller British companies get far less attention. That gap creates an opening. High quality, profitable businesses can trade quietly while institutions focus elsewhere. This article highlights 3 under the radar UK stocks from a rigorous quality screener that might deserve a place on your watchlist.
The three stocks below are a useful sample of what rises to the top, but the full screen surfaced 2 more small caps with equally compelling stories that are not covered here.
If you want to identify and analyze the rest of this elite pool, head straight to the High-Quality Undiscovered Gems screener.
Chaleit Holdings (AIM:CHA)
Chaleit Holdings runs a specialist cyber security consultancy focused on penetration testing, adversary simulation and AI led protection work, generating about £2.11 million from its Cyber Digital Protection Services unit. With a £15.5 million market cap, it fits the High-Quality Undiscovered Gems theme as a small, focused operator serving under defended clients.
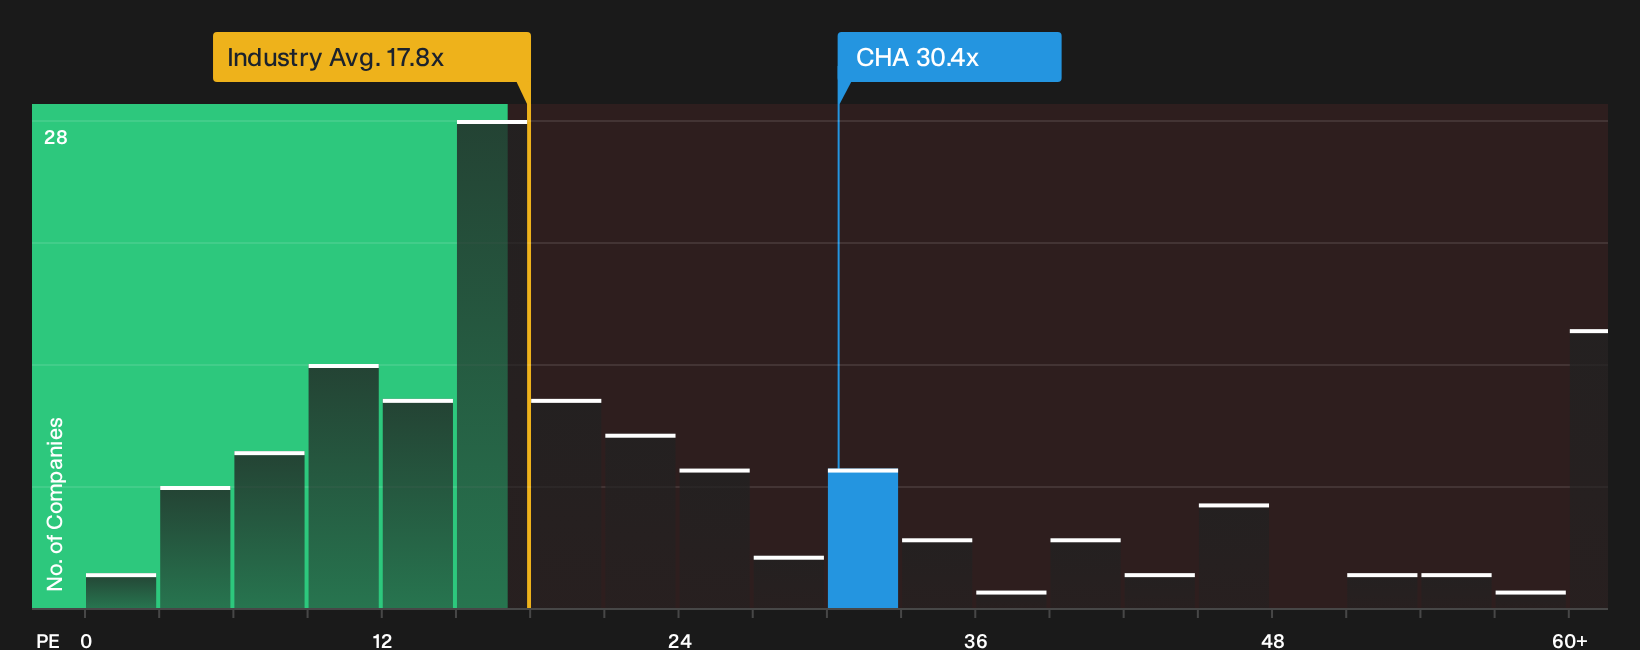
Chaleit Holdings sits squarely in the High-Quality Undiscovered Gems theme, pairing niche cyber security services with £2.11 million in revenue, 24.2% net margins and a P/E of 30.4x that signals investors already pay up for perceived quality. For a £15.5 million consultancy, the key question is what happens when that premium meets its tiny scale and funding mix.
That tension between premium pricing and tiny scale is exactly why the 2 key rewards and 2 important warning signs (1 is major!) could reshape how you view Chaleit Holdings potential upside and pressure points.
Integrated Diagnostics Holdings (LSE:IDHC)
Integrated Diagnostics Holdings plugs directly into the High-Quality Undiscovered Gems theme through its wide diagnostic and imaging platform in underpenetrated healthcare markets, and the real story for investors is how much of that operating strength ultimately filters down to shareholders.
Although management is reporting structurally higher gross and EBITDA margins supported by digitalization and procurement efficiencies, a persistently high effective tax rate of about 35% to 37% means that a smaller share of these operating gains converts into net profit, which can limit growth in earnings per share even if operating trends look strong.
What happens to future earnings power hinges on how one less visible cost pressure evolves over the next few years.
That pressure point is exactly where the full narrative for Integrated Diagnostics Holdings digs in, showing how tax, pricing power and capital allocation could be decoupling headline strength from long term value creation.

Skillcast Group (AIM:SKL)
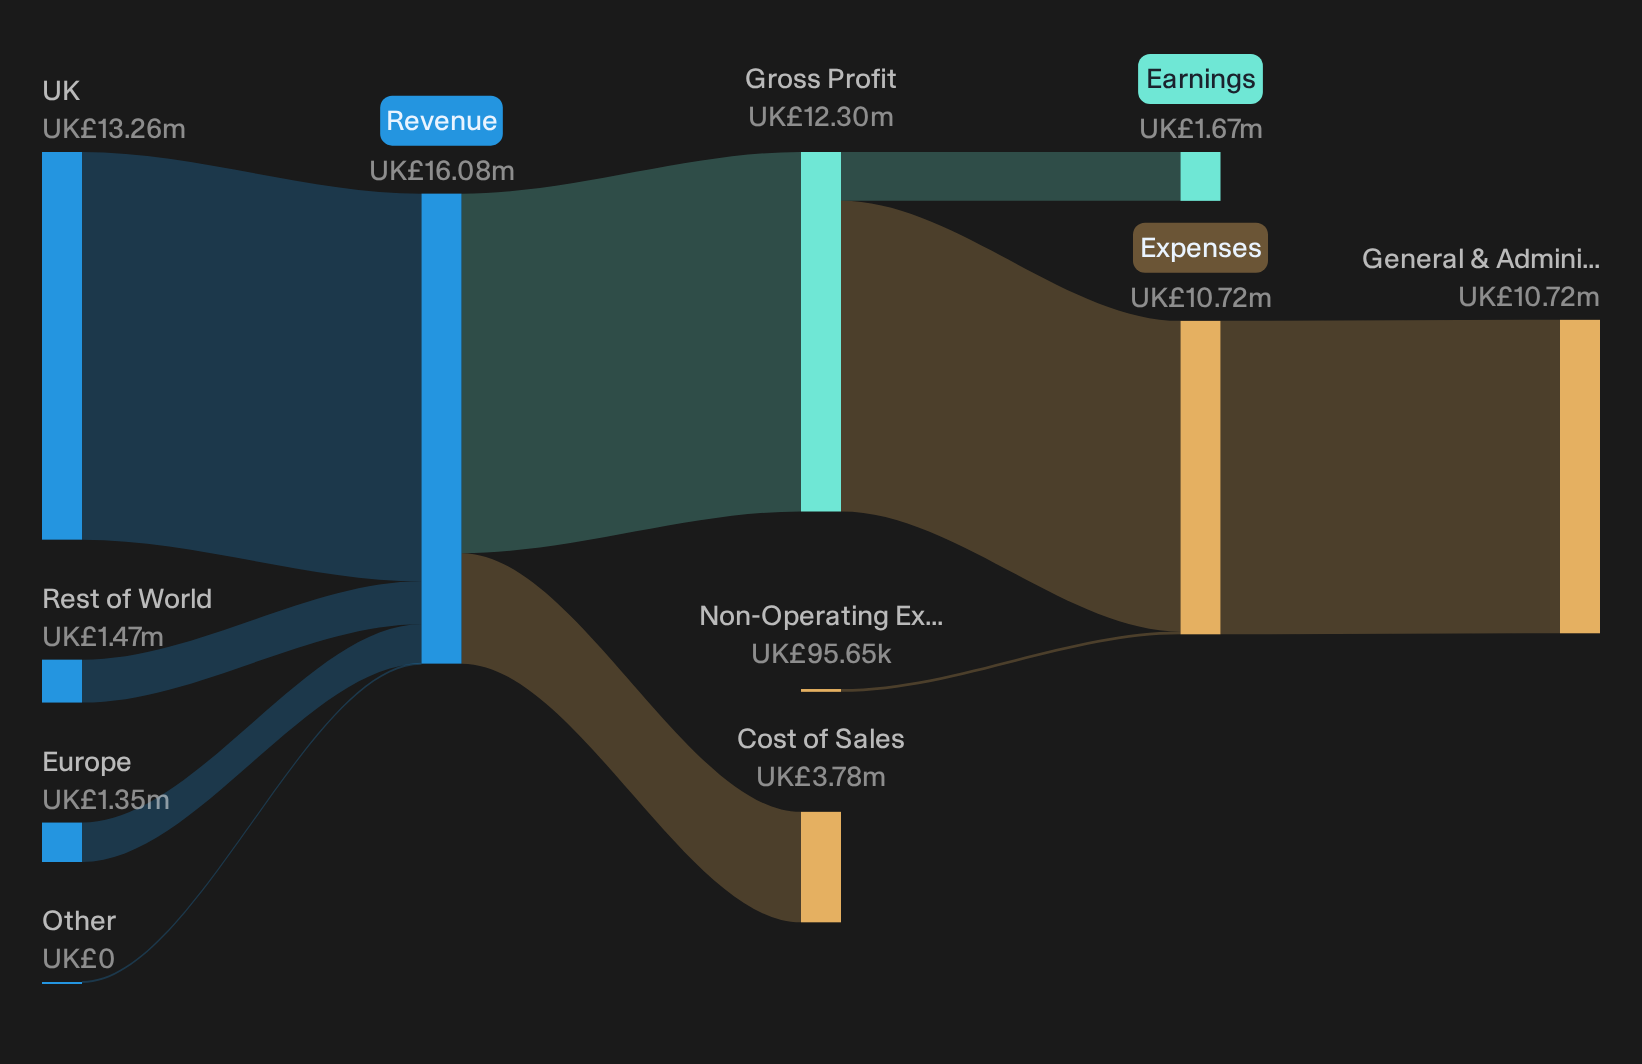
Skillcast Group delivers compliance-focused e-learning and its Learning Management System to regulated firms, with all £16 million of revenue tied to SaaS subscriptions and related professional services. Most income comes from the UK, and the business is valued at about £37.7 million.
Skillcast Group fits directly into the High-Quality Undiscovered Gems theme because its LMS, Policy Hub and SMCR tools turn rising regulatory training into sticky subscription income, backed by 21.3% ROE and 10.4% net margins. The key question is how that earnings engine behaves if a single unseen funding pressure tightens.
If that funding strain is what you are weighing up, go straight to the Skillcast Group financial health report for a closer look at how resilient Skillcast Group really is.
Seeking Fresh Alternatives Beyond Today
Fresh breakouts and quiet momentum can get caught quickly once the crowd arrives. Scan under the radar stocks while it matters, before the best entry points start dropping, and consider acting earlier in your research process.
- Spot income workhorses early by scanning the 5 dividend fortresses that aim to keep cash returns flying while they are still under the radar for now.
- Track real-world AI demand by scouting the 53 AI infrastructure stocks built around companies powering chips, data centers and networks before that story goes fully mainstream.
- Position ahead of electrification themes by combing through the 16 top copper producer stocks that focuses on producers tied to grid upgrades and energy transition while prices still look reasonable.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com