


Do Stronger Earnings Change The Bull Case For TriMas (TRS)?
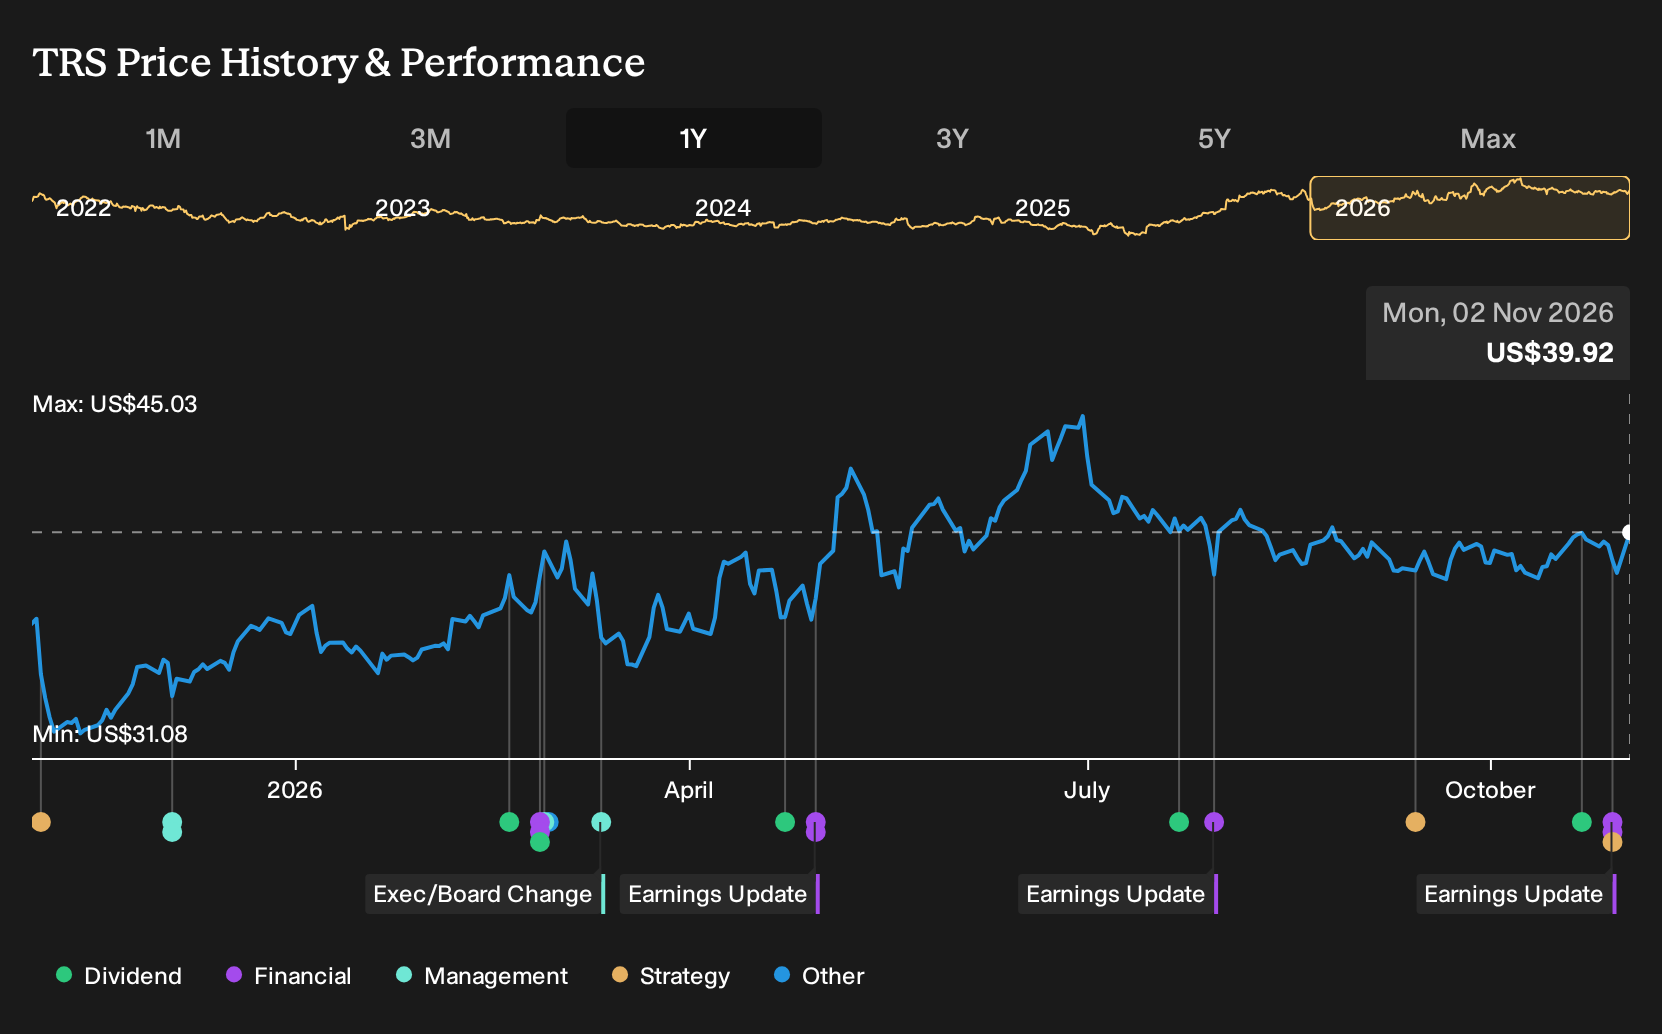
- TriMas reported third quarter 2026 sales of US$178.74 million and net income of US$19.36 million, alongside full year 2026 GAAP diluted EPS guidance of US$1.06 to US$1.13 and a maintained quarterly dividend of US$0.04 per share.
- The combination of higher earnings per share compared with the prior year period and fresh full year EPS guidance highlights how TriMas is leaning on recent execution, cost control and portfolio focus to support both reinvestment capacity and ongoing cash returns.
- The focus now turns to how TriMas' investment narrative aligns with this stronger quarterly profitability, as fresh EPS guidance reframes expectations.
Scan how TriMas' earnings guidance compares with other industrials by reviewing a hand picked set of 34 high quality undervalued stocks with resilient balance sheets and proven cash generation.
TriMas Investment Narrative Recap
To own TriMas, you need to believe the packaging focused portfolio and Specialty Products can convert operational discipline into consistent earnings, even with only modest top line expansion. The fresh 2026 GAAP EPS guide of US$1.06 to US$1.13 leans on cost control and execution. The near term catalyst is whether that profitability holds as the refocused group beds down.
The biggest risk still sits in execution, especially if past manufacturing inefficiencies in Specialty Products or pressure from sustainability rules on packaging resurface. The latest quarter, with higher sales and net income than the prior year period, improves confidence but does not fully remove those operational and regulatory uncertainties.
The most relevant update here is the new 2026 GAAP diluted EPS range of US$1.06 to US$1.13. That number becomes the reference point for whether TriMas converts its cost savings program, portfolio reshaping and Norris Cylinder initiatives into cleaner earnings, rather than one off items or non cash gains.
For investors, that guidance ties directly into the key catalyst, consistent margin improvement from Packaging and Specialty Products. The reaffirmed US$0.04 quarterly dividend remains in the background as a cash return, but the core test will be whether future quarters track close to this EPS range without quality concerns around the profit mix.
TriMas' current analyst narrative points to forecast revenues of US$730.4 million and earnings of US$41.3 million by 2029, based on 3.2% yearly revenue growth and an earnings decline of US$42.2 million from US$83.5 million today.
Uncover why TriMas' fair value points to a 13% potential upside to its current price, which could close faster than expected.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$4.52 to US$45 per share, which shows how far apart retail views on TriMas can be. When this is set against the fresh EPS guidance and ongoing cost savings plan, it serves as a reminder to weigh multiple viewpoints before forming your own stance.
Explore another TriMas fair value estimate, including one that suggests as much as 89% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TriMas research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TriMas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TriMas' overall financial health at a glance.
Looking for more investment ideas beyond TriMas?
Once you have a view on TriMas, it can help to widen the lens and compare it with other opportunities that share similar qualities or very different risk profiles. The Simply Wall St Screener lets you do that in a structured way so you are not relying on hunches or headlines.
- If you want steadier profiles with limited downside risk, start by scanning a curated set of 29 resilient stocks with low risk scores that emphasise resilient business models over excitement.
- For income focused portfolios, you can scan for cash generators with higher yields by reviewing a hand picked group of 4 dividend fortresses that aim to combine payout strength with balance sheet support.
- To search for under the radar ideas, widen your research to a broader 19 high quality undiscovered gems that may not be widely followed but still show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com