


Integra LifeSciences Holdings (IART) Returns To Profit, Is The Stock Still A Bargain?
What the latest Integra LifeSciences Holdings earnings tell you
Integra LifeSciences Holdings (IART) just reported third quarter earnings for 2026, with sales of US$411.18 million and net income of US$14.85 million after a loss in the same period last year.
The company paired that return to profitability with fourth quarter revenue guidance of US$413 million to US$433 million. This indicates a possible year over year decline that gives investors a more cautious near term outlook to assess.
Integra LifeSciences Holdings is trading at US$13.61, with a 1-day share price return of 6.75% and a 7-day share price return of 12.48%. This contrasts with a 90-day share price decline of 23.97%, while the 1-year total shareholder return of 18.45% sits against a 3-year total shareholder return decline of 64.33% and a 5-year total shareholder return decline of 81.24%. This suggests that recent momentum has picked up even as longer term holders still face steep losses.
See how Integra LifeSciences Holdings compares with other healthcare names showing renewed earnings momentum using our curated list of 33 healthcare AI stocks.
Integra LifeSciences Holdings just bounced on its earnings surprise, yet analyst targets and intrinsic estimates still sit above today’s US$13.61 quote. How far does fair value really stretch beyond the recent rebound?
Most Popular Narrative: 41% Undervalued
The most followed narrative pegs Integra LifeSciences Holdings at a fair value of $23 against the latest $13.61 close. This frames today’s post earnings bounce as only a partial catch up to those expectations.
Analysts already factor in Integra LifeSciences Holdings finishing its Compliance Master Plan and stabilising operations. However, the reported reduction in remediation spending, several quarters without major supply upsets and ongoing transformation savings point to further room for structural cost efficiency gains that could still lift gross margin and earnings quality beyond what current models assume.
See why 2 investors see Integra LifeSciences Holdings as 41% undervalued.
Result: Fair Value of $23 (UNDERVALUED)
Still, Integra LifeSciences Holdings faces real pressure if high leverage persists, and any further guidance cuts revive concerns about execution and earnings quality.
Find out about the key risks to this Integra LifeSciences Holdings narrative.
Another View on Integra LifeSciences Holdings Valuation
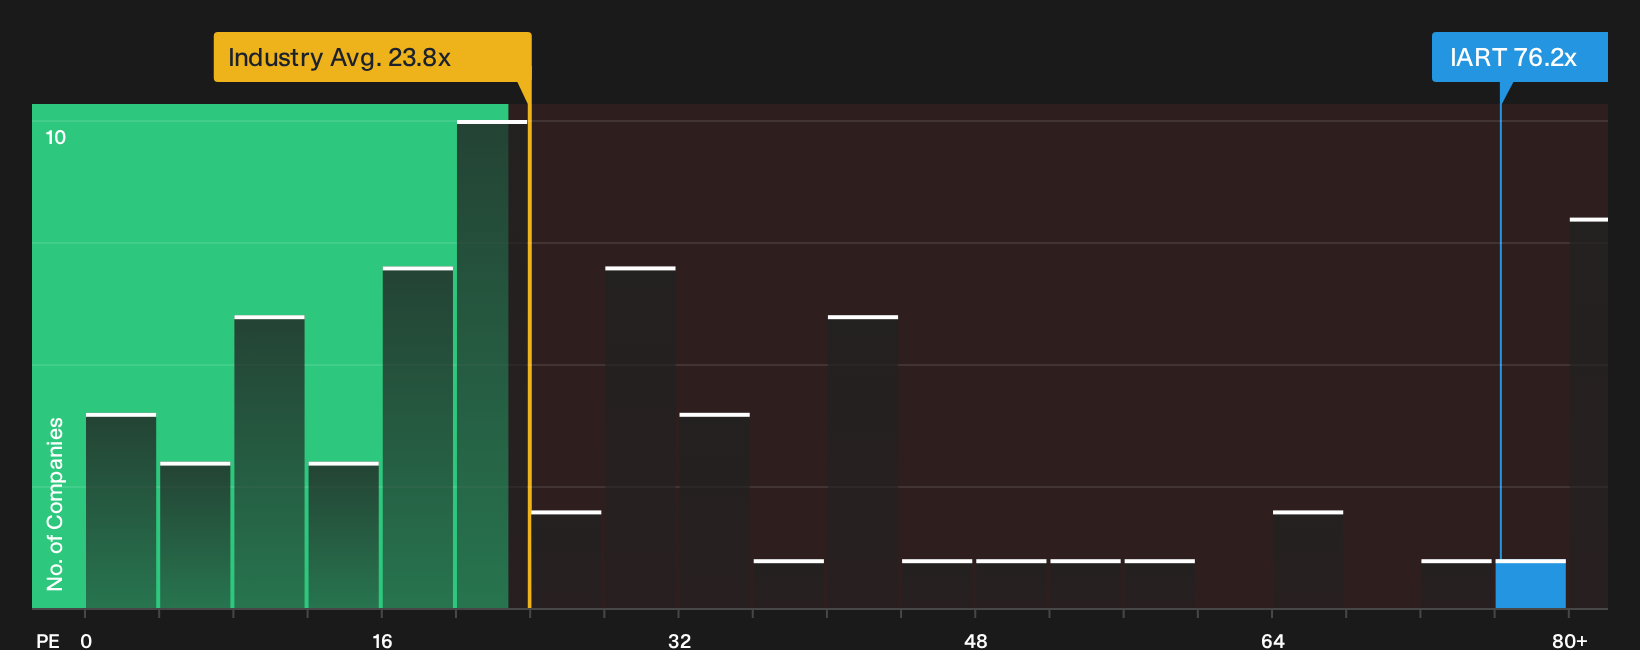
Multiples tell a very different story for Integra LifeSciences Holdings. The stock trades on a P/E of 81.4x, which is materially higher than the US Medical Equipment industry at 23.8x and above a fair ratio of 54x that the market could move toward. That gap suggests investors face more valuation risk if sentiment cools than the bullish fair value of $23 alone implies.
For a closer look at what this pricing gap could mean in practice, including how it compares with peers on the same yardstick, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Integra LifeSciences Holdings can make the story feel messy, which is exactly why readers who care about the risk reward balance should pressure test the data themselves and weigh the 3 key rewards and 2 important warning signs.
Hunting for more ideas beyond Integra LifeSciences Holdings?
If Integra LifeSciences Holdings has your attention after this update, broaden your opportunity set now and pressure test where your next dollar really works hardest.
- Target quality at a discount by scanning companies on our 33 high quality undervalued stocks that pair stronger fundamentals with prices below their estimated worth.
- Prioritize resilience by reviewing the 29 resilient stocks with low risk scores that focuses on businesses with steadier risk profiles and fewer potential shocks.
- Get ahead of the crowd by checking the 19 high quality undiscovered gems that highlights financially solid companies still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com