


How User Acquisition Funding Will Impact Unity Stock (U)
- In October 2026, Unity Software announced that it partnered with PvX to offer eligible growth-stage studios in the Unity ecosystem access to non-dilutive user acquisition financing, supported by PvX’s more than US$1.3b in committed capital across 17 markets.
- The collaboration links PvX’s cohort-based funding model to Unity’s Vector advertising reach. This structure could make user acquisition spending more data-driven for qualified developers using Unity Ads, credits and support rather than relying on new equity raises.
- We will now look at how Unity Software’s investment narrative could be influenced by PvX’s non-dilutive user acquisition financing partnership.
Scan 41 profitable AI stocks that aren't just burning cash that, like Unity Software’s PvX tie-up, are using data driven user acquisition and capital efficiency to pursue additional growth.
Unity Software Investment Narrative Recap
To own Unity Software, you need to believe its twin engines, Create tools and the Vector ad stack, can support the kind of revenue expansion and margin lift analysts are modelling, while the stock’s relatively high P/S multiple stays supported. The PvX partnership ties directly into Vector, but on its own it does not radically change that core belief.
The near term swing factor still sits in execution on the Grow transition, including sunsetting ironSource Ad Network and the Supersonic sale, and whether recent EBITDA margin levels are sustainable. The key risk remains simple. Any visible slowdown versus the implied revenue and earnings ramp could quickly hurt confidence in Unity Software.
Among recent developments, the shift to Unity Vector as the central ad platform looks most relevant to this PvX tie up. Vector has already reached a run rate described as substantially above US$1b within six quarters of launch, and PvX financing plugs into that system. This keeps the focus on advertiser performance and ROAS products as a primary operational driver.
This matters because the biggest catalysts flagged by analysts sit around AI driven ad products, Unity 6 and the coming Unity 7 cycle, and the margin uplift from the Grow mix change. The PvX program leans on the same data stack, including the Developer Data Framework, so investor attention likely stays on whether campaign spend and free cash flow quality hold up as that ecosystem scales.
Unity Software's current analyst narrative points to forecast revenues of US$3.6b and expected earnings of US$992.0m by 2029. That profile assumes yearly revenue expansion of 20.7% and an earnings swing of roughly US$1.58b from a loss of US$587.5m today to the projected 2029 profit base.
Uncover why Unity Software's fair value indicates a 30% potential upside to its current price that may not last much longer.
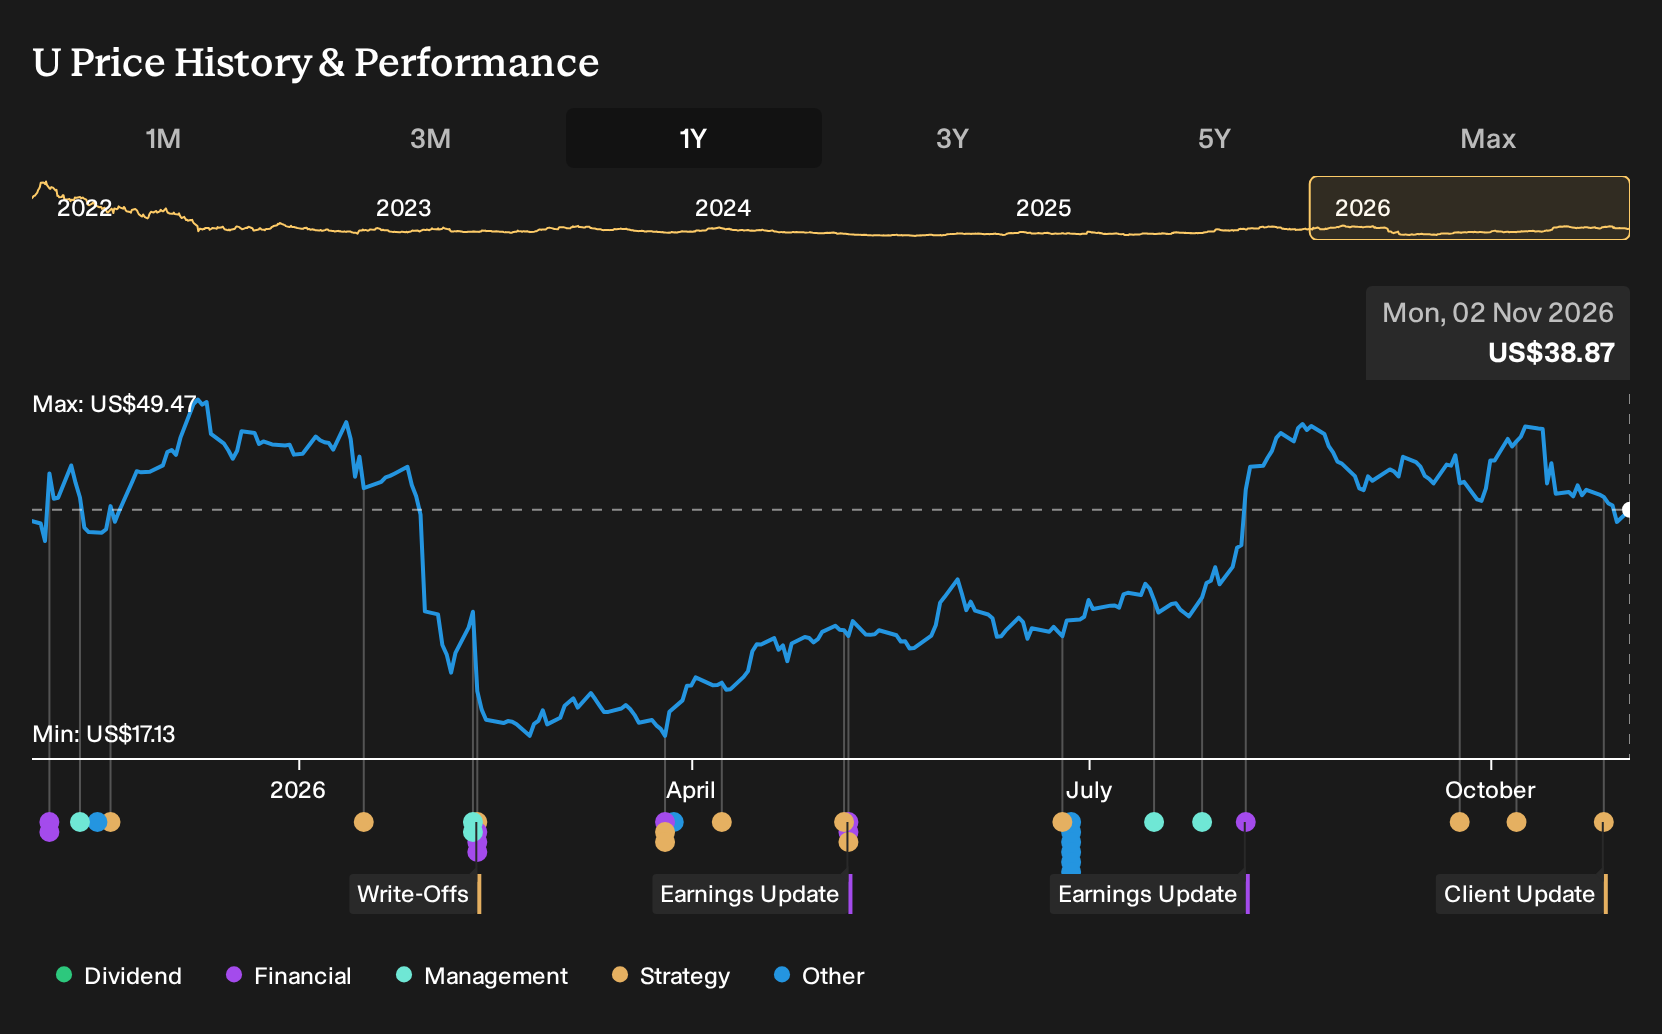
Exploring Other Perspectives
Unity Software looks very different if you focus on one bearish catalyst: higher ongoing AI and cloud spending. The lowest analysts were already pencilling in 14.3% annual revenue growth and about US$918.3m in earnings by 2029, compared with US$3.0b in sales, before this PvX funding news. Take that spread as an invitation to compare multiple narratives.
Explore 3 other Unity Software fair value estimates, including one that suggests it could be worth just $50.41!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Unity Software research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Unity Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unity Software's overall financial health at a glance.
Looking for more investment ideas beyond Unity Software?
If you want to round out your watchlist alongside Unity Software, it can help to scan other companies with different strengths and risk profiles using the Simply Wall St Screener.
- If resilience matters most to you, start with a 29 resilient stocks with low risk scores. This may suit a more defensive approach to building wealth over time.
- If balance sheet strength is your priority, filter for a list of solid balance sheet and fundamentals (24 results) that can better withstand tougher funding conditions.
- If you are hunting for potential up and comers, take a look at a 19 high quality undiscovered gems that combine strong fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com