


How Q3 Revenue Growth At Inchcape (LSE:INCH) Has Changed Its Investment Story
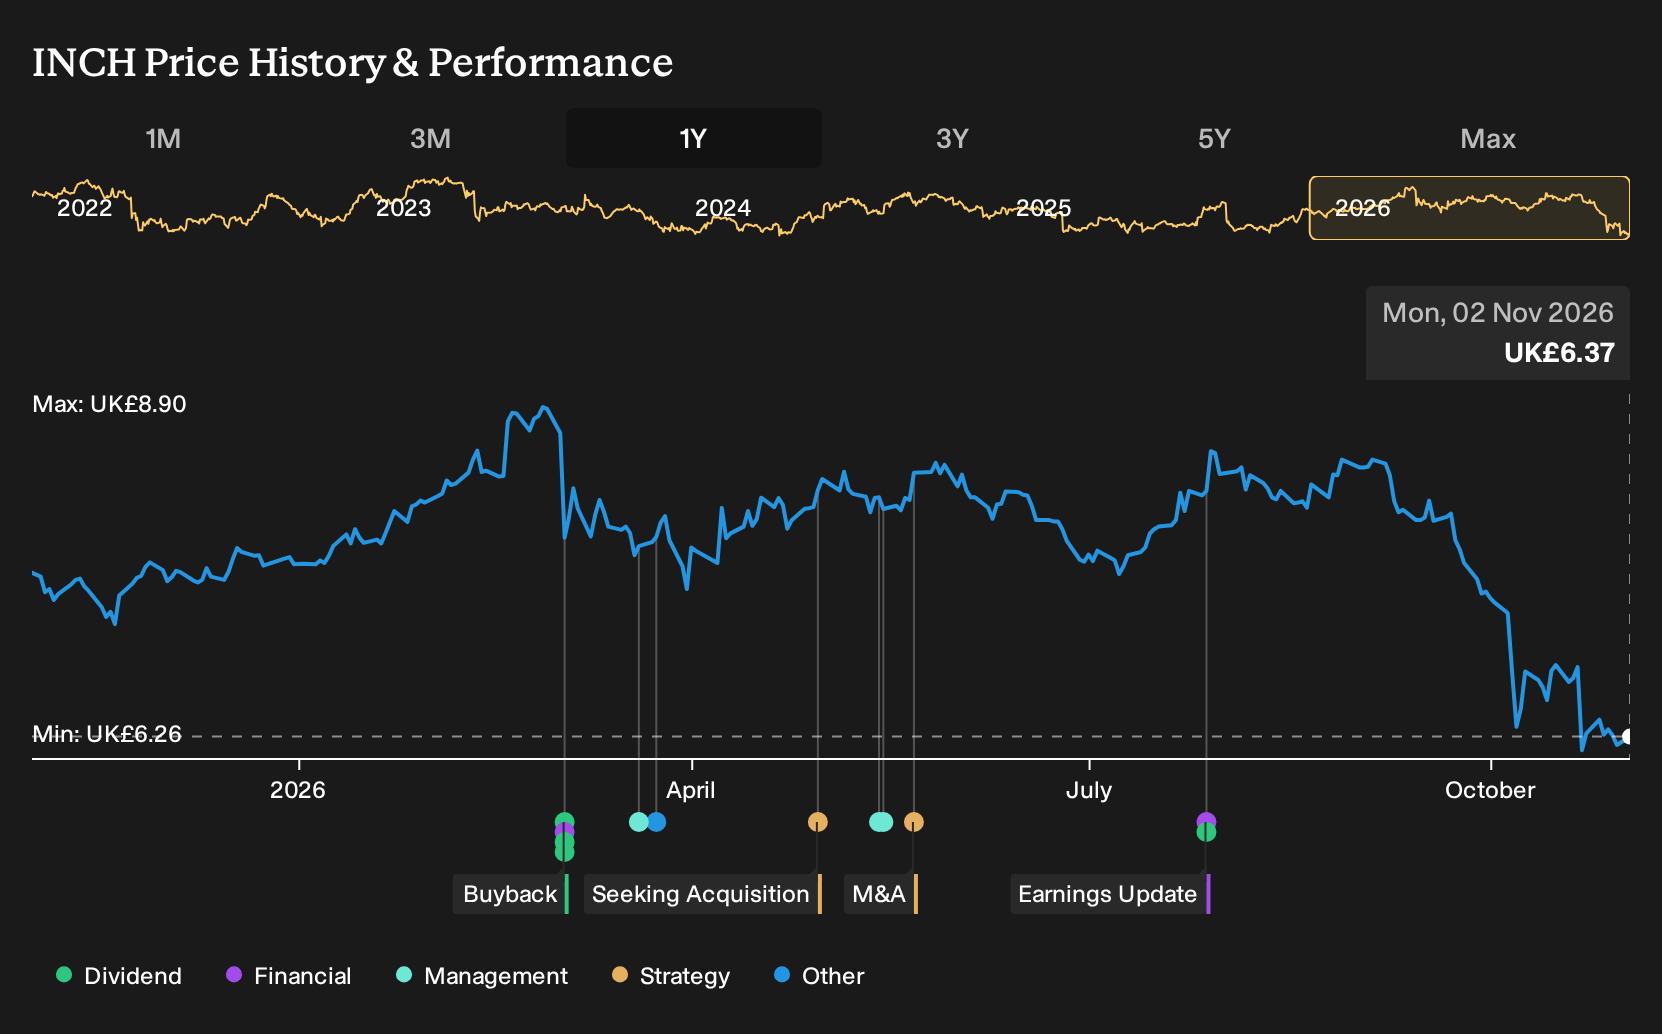
- Inchcape reported its third quarter 2026 trading update on 22 October 2026, with group revenue for the period at £2.5 billion, which the company described as 7% reported revenue growth compared with the same quarter a year earlier.
- The revenue update gives investors more detail on how Inchcape is converting its distributor contracts and emerging market footprint into reported sales. This offers a clearer read on current demand and execution than longer term forecasts alone.
- We will now examine how Inchcape's investment narrative could be affected by the reported 7% third quarter revenue growth to £2.5 billion.
See how Inchcape's latest revenue update compares with peers by reviewing our hand picked list of 13 high quality undervalued stocks that also pair solid cash generation with robust balance sheets.
Inchcape Investment Narrative Recap
An investor in Inchcape needs to believe the distributor model across Asia Pacific, the Americas and Europe & Africa can keep generating attractive contracts, while the business adapts to more digital and direct to consumer selling. The Q3 update, with £2.5b of revenue and 7% reported growth, points to demand holding up in the near term.
The key short term swing factor is execution in emerging markets, where FX moves and competition from Chinese manufacturers can quickly affect margins. The biggest operational risk still sits in the heavy reliance on physical retail, which could pressure profitability if online channels accelerate faster than Inchcape’s own digital rollout.
The Q3 2026 sales and trading statement call on 22 October is the announcement that matters most here. It gives texture on how Inchcape is actually trading against those risks and catalysts. Revenue of £2.5b for the quarter lets you assess whether contract wins in Latin America, Africa and Asia Pacific are translating into reported sales.
For anyone tracking catalysts, that call helps frame whether cost actions, aftermarket initiatives and OEM partnerships are offsetting known headwinds such as weak Chile volumes or FX volatility. It also matters for balance sheet questions, since debt is flagged as not well covered by operating cash flow and consistent cash generation is central to that debate.
Inchcape's current analyst narrative points to forecast revenue of £10.7b and projected earnings of £352.3 million by 2029, based on an assumed 4.0% yearly revenue growth rate and an earnings increase of about £122.3 million from earnings today of £230.0 million.
Uncover why Inchcape's fair value indicates a 46% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view focuses on APAC restructuring rather than the Q3 revenue headline. The most cautious analysts were only pencilling in revenue of about £10.0b and earnings of roughly £349.0 million by 2029, with slower 1.9% annual growth. You can treat the 7% Q3 update as fresh evidence that might eventually shift those expectations, and compare several viewpoints before drawing your own conclusion.
Explore 4 other Inchcape fair value estimates, including one that suggests it could be worth just £7.50.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Inchcape research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Inchcape. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Inchcape's overall financial health at a glance.
Looking for more investment ideas beyond Inchcape?
Once you have a view on Inchcape, it helps to compare it with other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener can surface stocks with very different profiles in a few minutes, so you can build a watchlist that actually fits how you want to invest.
- If you want potential upside from smaller companies without ignoring balance sheet quality, start with a focused group of 13 elite penny stocks with strong financials that already clear some basic financial strength hurdles.
- For investors who care most about resilient business models and capital preservation, a curated set of 4 resilient stocks with low risk scores can be a practical way to look for steadier performers.
- Anyone hunting for fresh ideas away from crowded trades can scan a refined pool of 5 high quality undiscovered gems that show strong fundamentals but attract less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com