


What Bank OZK Holders Got Right
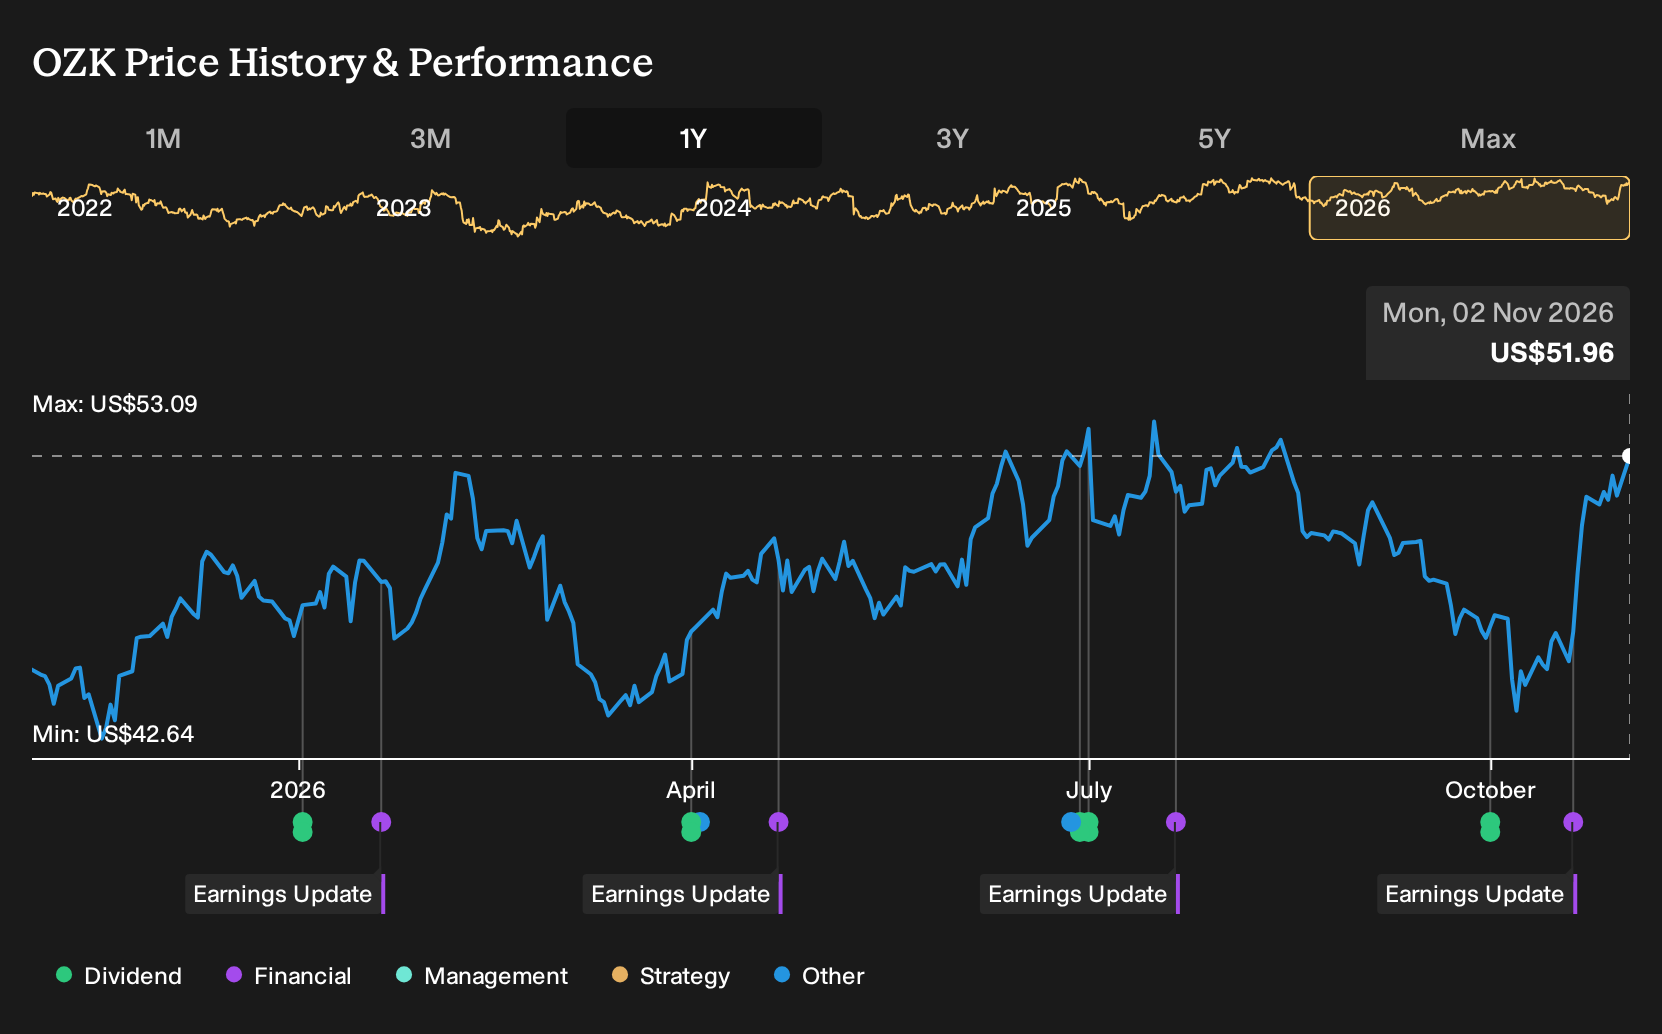
If you had bought Bank OZK on 2 November 2025 and simply held on, the outcome might surprise you. Holding Bank OZK over the past year would have returned 20.8%, including dividends. That result now sits alongside fresh 2026 headlines about softer earnings, a shrinking net margin in Q3, faster real estate paydowns, buybacks and steady dividend hikes. If you were making that call back then, how would you have weighed growth ambitions against rising commercial real estate strain?
Bank OZK has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On Bank OZK
The shares cost US$44.99 at the start, and investors had to decide which story about Bank OZK felt more believable.
One bullish view argued the stock was worth a Fair Value of US$57.5, a price implied by expectations of 10.6% annual revenue growth and a future P/E of 9.6x. That camp leaned on expansion in Sun Belt markets and a buildout of Corporate & Institutional Banking.
The bearish camp pointed to a Fair Value of US$42 and focused on concentrated commercial real estate exposure. It highlighted the risk that aggressive branch expansion and hiring could leave expenses high if new markets underperformed.
What The 2026 Results Did To The Bank OZK Debate
Bank OZK’s Q3 2026 figures showed revenue at US$391.5 million and net income at US$164.3 million, both below Q3 2025, with net margin slipping from 45.0% to 42.0%. That erosion challenged the bullish case that anticipated higher profitability, even as management pursued diversification and loan mix changes. The evidence cut both ways.
The key lesson is simple. When a thesis leans on better profitability, track the reported net margin and absolute earnings against that story each quarter, then decide how much you are willing to pay for those trends.
What Bank OZK’s Current Price Already Bakes In
Bank OZK now trades at US$51.96, with this Narrative’s Fair Value sitting below that quote. The gap reflects concern that heavy real estate exposure and elevated RESG repayments could leave earnings progress more muted than recent share gains might suggest.
For today’s valuation to hold up, a buyer has to believe the shift toward CIB, community, consumer and fee income offsets funding costs and RESG paydowns. The specific hurdle is whether credit costs tied to stressed life science and office loans stay contained enough for that transition to carry through.
"Although Bank OZK is building out Corporate & Institutional Banking with multiple lending verticals and fee services, the recent caution that 2026 net interest income may not match 2025 because average earning assets are held back by large, lumpy RESG paydowns points to a risk that balance sheet growth and revenue fall short of what high margins alone would suggest."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond Bank OZK
Bank OZK’s story points directly at commercial lending risk and potential reward. Nearby, a different kind of banking machine is quietly humming.
Large global lenders are wiring together payments, credit and markets under one roof. That mix aims to keep earnings linked to many fee streams, not only interest spreads.
The same companies are leaning into financing data infrastructure, security projects and cross border money movement. These areas reflect clients funding long term technology and resilience plans.
If Bank OZK highlights concentrated exposure questions, this broader model raises another. How much value may sit in banks that turn scale and diversification into recurring financial pipelines?
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 23% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com