


How Workforce Cuts And Ad Guidance Will Impact Netflix (NFLX) Investors
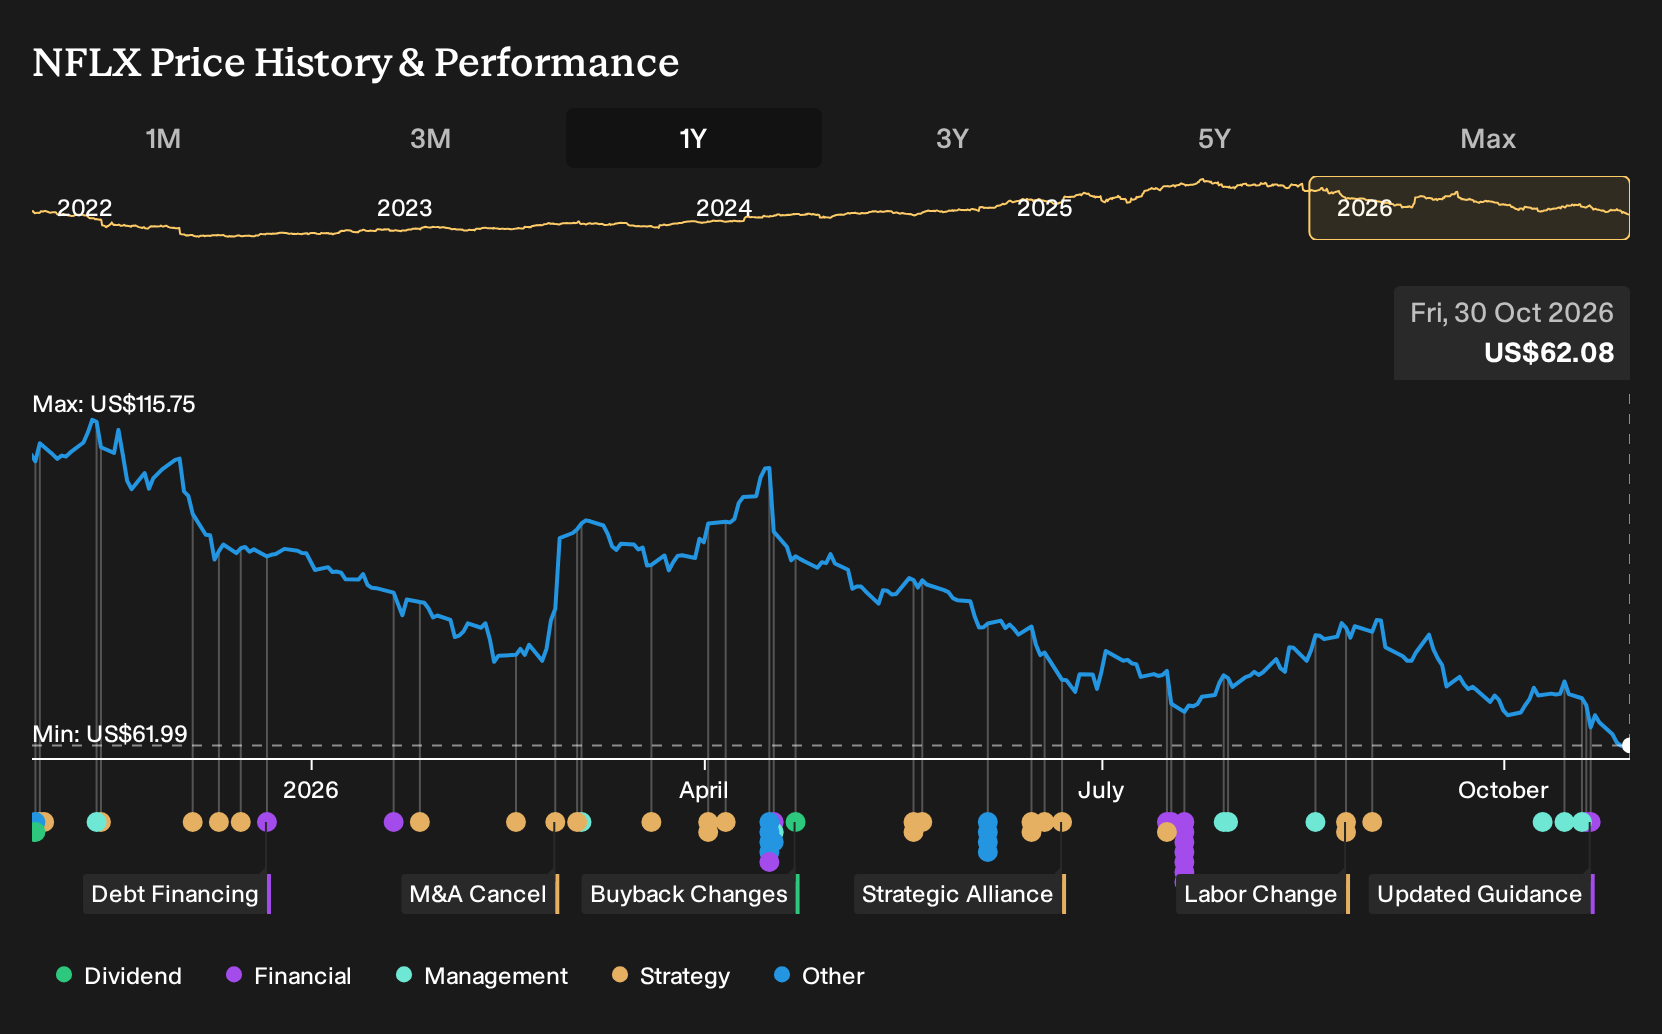
- Netflix issued Q3 2026 results showing higher sales and net income year over year, paired with new Q4 and full-year guidance that trims the 2026 ad revenue outlook to about US$2.7b and factors in workforce reductions that carry a modest drag on operating margin.
- The business is leaning harder on cost discipline and operating margin targets, using layoffs, headcount restructuring and ad tier execution to protect profitability even as user engagement and advertising uptake come under pressure.
- The focus now turns to how Netflix's investment narrative holds up when evaluated alongside slower ad revenue guidance and ongoing restructuring moves.
Scan how Netflix's recalibrated ad targets compare to peers and identify other platforms where the market may be mispricing cash flow with 36 high quality undervalued stocks.
Netflix Investment Narrative Recap
To own Netflix today, you need to believe the streaming giant can keep turning a single global platform into reliable subscription and ad cash flows while holding its high margins. The updated 2026 outlook still leans heavily on operating income and a 31.5% margin, even as engagement questions and viewing share pressure linger.
The main near term catalyst is whether the ad tier and live programming can stabilise viewing time and support the trimmed US$2.7b ad target. The biggest risk is that soft engagement and tougher competition further limit pricing power and ad demand. Recent guidance tweaks look material for expectations around both.
The fresh full year 2026 guidance is the key reference point. Management now expects about US$51.1b in sales, operating income growth above 20% and a 31.5% margin, with ad revenue of roughly US$2.7b instead of US$3b. That combination puts profit efficiency at the forefront while acknowledging slower ad product rollout.
For you as a shareholder, the question is whether Netflix can execute on ad tech, content, sports and live events quickly enough to keep that margin target credible while engagement is under strain. The trimmed ad outlook ties directly into both the main catalyst and the core risk, so it is hard to treat it as minor.
Analysts expect Netflix's revenues to reach US$66.5b and earnings to be US$19.9b by 2029, based on forecast revenue growth of 10.2% a year and an earnings increase of about US$5.1b from US$14.8b today.
Uncover why Netflix's fair value indicates a 39% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a different angle on Netflix, focus on the risk around ad margins rather than just slower ad growth. The most cautious analysts were already assuming revenue of about US$64.5b and earnings of roughly US$17.6b by 2029, with thinner margins. That is a far more downbeat story, and this new guidance could push those forecasts to shift again.
Explore 44 other Netflix fair value estimates, including one that suggests there may be as much as 8% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Netflix research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Netflix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Netflix's overall financial health at a glance.
Looking for more investment ideas beyond Netflix?
If the latest Netflix guidance has you thinking about position sizing and portfolio balance, it can help to line it up against other potential opportunities using the Simply Wall St Screener.
- For investors who want both quality and a margin of safety, compare Netflix with a curated set of companies screened for strong fundamentals and attractive valuations through 36 high quality undervalued stocks.
- If your priority is ballast in the portfolio, focus on firms with robust finances and resilient balance sheets by scanning the list of solid balance sheet and fundamentals (24 results).
- For those hunting for less crowded opportunities that might not be widely followed yet, broaden your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com