


Missed Prysmian's Rally? Here's What Holders Saw
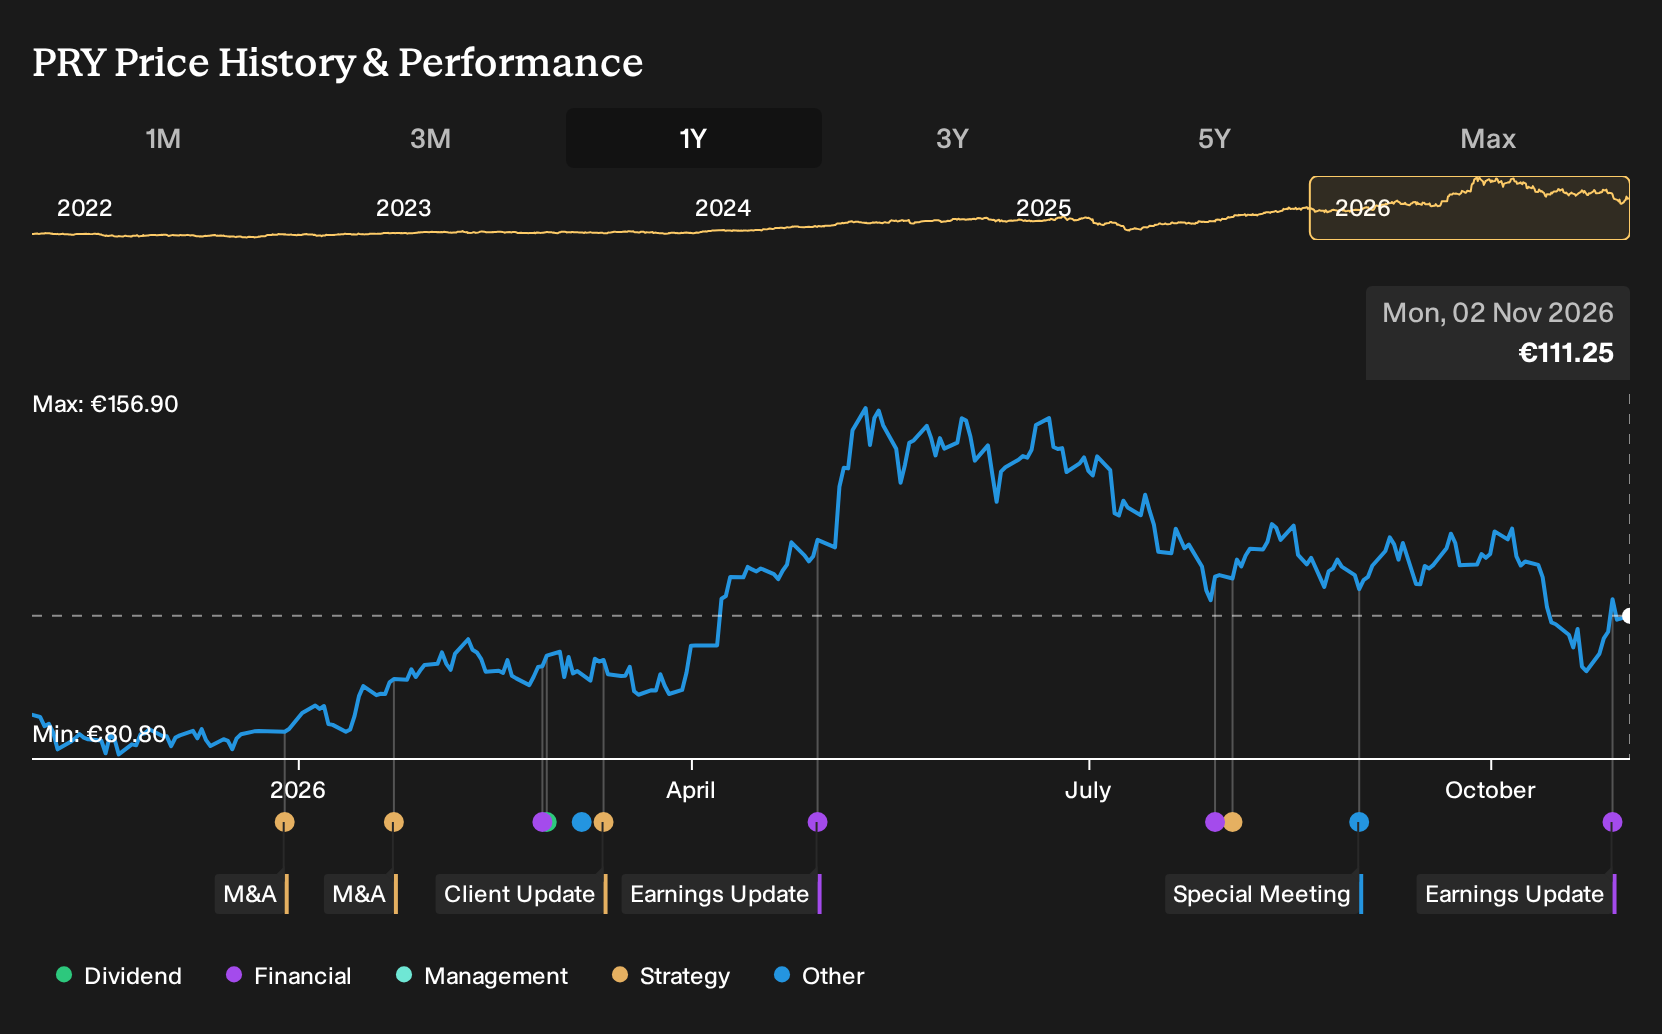
If you only glanced at Prysmian headlines this year, the Molex deal for up to €5.5b of data center fiber might be the one that stuck. For Prysmian shareholders, the return over the past year was 25.9%, including dividends. If you had been deciding on 2 November 2025 whether to buy, you had both bullish and cautious analyst camps on record. The real puzzle is how much conviction you needed about data and grid demand before that Molex contract surfaced.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Prysmian has already moved. Pinpoint other ways to investigate the theme among 43 power grid technology and infrastructure stocks.
The Two Prysmian Stories Investors Had In Front Of Them
The shares cost €89.82 at the start of the period, so anyone looking at Prysmian then had to decide which story about cables and data they trusted more.
The bullish narrative put fair value at €102. It focused on Prysmian using operational leadership and domestic production to keep transmission EBITDA margins high, while tariffs on imported copper and cable supported pricing power in the U.S.
The cautious narrative saw fair value at €79.13. It emphasized reliance on protective trade policies and large grid projects, where any policy reversal or project delays could pressure earnings.
What The Facts Did To The Prysmian Argument
Prysmian’s long term Molex supply agreement for up to €5.5b of data center fiber, plus more than €1b earmarked to expand U.S. capacity, directly leans toward the bullish story that counted on strong digital and grid demand. The agreed Atkore acquisition and later completion also line up with that growth focused script, so the evidence mainly supported the optimistic case.
The takeaway is simple. When a thesis hangs on demand and capacity, you test it against concrete contracts, committed capex, and executed M&A rather than price targets.
What Prysmian's Recent Run Already Prices In
Prysmian shares now trade at €111 after a 25.9% gain over the past year. The selected Narrative’s Fair Value sits above that level, reflecting confidence in long duration optical contracts and higher margin grid related solutions feeding into earnings and cash generation.
Today you are effectively assessing whether Prysmian can continue turning large AI data center and grid orders into realised margins, particularly once Encore Wire and Atkore are fully integrated and the expected synergies and free cash flow targets are tested in reported results.
"The main requirement is successful execution on large optical and grid contracts and on integrating Encore Wire and Atkore so that planned margins, synergies and free cash flow are reflected in future results."
One Narrative disagrees with today's price. → See where this Narrative says Prysmian should trade
Looking One Step Beyond Prysmian
Prysmian focuses on getting power and data to the right place. That still leaves a different challenge inside every data center.
All that hardware turns electricity into heat. If the heat is not controlled, the computing capacity you expect can start throttling back.
Another specialist builds the power systems, cooling gear, and thermal controls that keep those racks operating.
Its equipment helps data centers manage energy, remove heat, and keep critical services online.
As AI loads push hardware harder, that supporting infrastructure quietly becomes central to your broader thesis.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 76% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com