


Does Restaurant Expansion Change The Bull Case For Macerich Stock (MAC)?
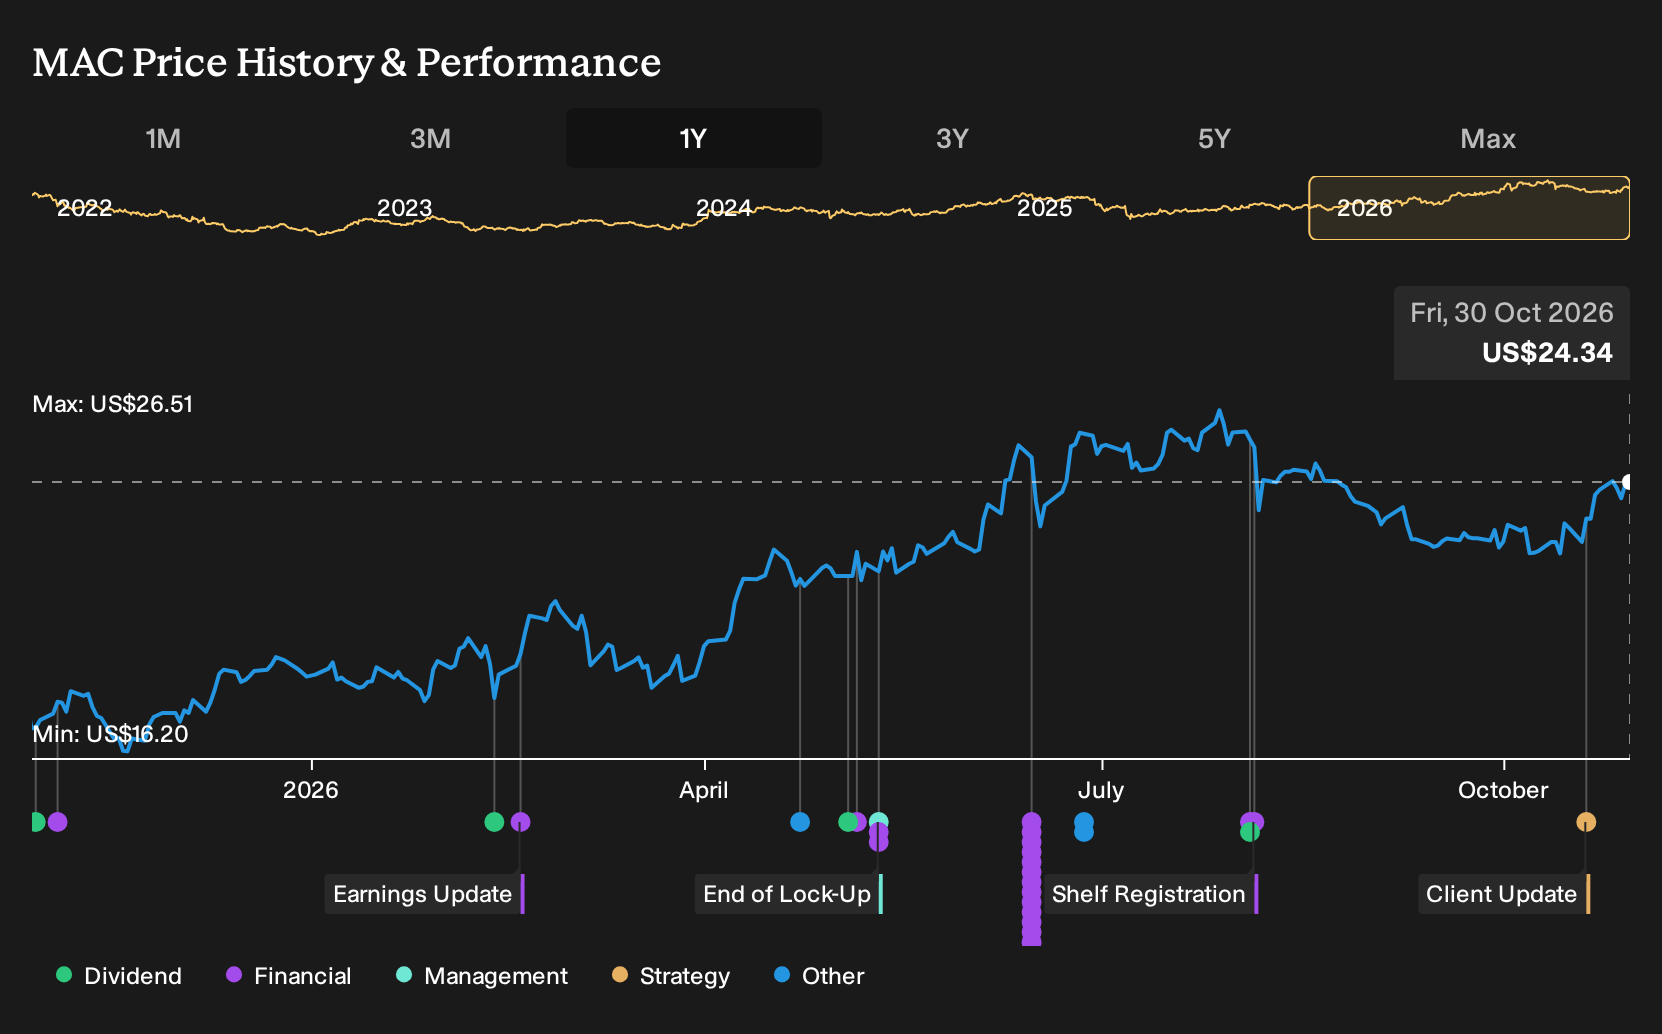
- Macerich’s board declared a quarterly cash dividend of $0.17 per common share, payable on December 28, 2026, to holders of record on December 14, 2026, and the REIT has been rolling out new restaurant and entertainment tenants across its Class A mall portfolio.
- The push into first to market and experience led dining concepts, from Eataly to Din Tai Fung and Seafood City, signals a heavier tilt toward food and entertainment as traffic drivers across Macerich’s higher quality centers.
- This article examines how Macerich’s investment narrative is shaped by this accelerated restaurant leasing push across its flagship shopping centers.
Scan beyond Macerich’s dividend and restaurant push by comparing it with 19 high quality undiscovered gems, which is built around strong fundamentals and under-the-radar expansion stories across the market.
Macerich Investment Narrative Recap
Macerich still appeals to investors who believe high quality malls can support traffic with food, entertainment and omni channel retail rather than just traditional apparel. The short term story hinges on executing the Path Forward leasing plan and turning the signed not open pipeline into paying tenants. The new dividend affirmation is reassuring but does not materially change that operating focus.
The biggest near term risk remains the balance sheet. Net debt to EBITDA sits above 7x and interest costs are not well covered by current earnings, so refinancing terms and asset sale progress matter more than a single US$0.17 dividend. If funding stays tight, redevelopment spending and NOI uplift could be slower than hoped.
The acceleration of restaurant leasing across Macerich properties is the announcement that really matters here. Eataly, Din Tai Fung, Seafood City and other experience led concepts speak directly to the traffic thesis behind those 30 backfilled anchor boxes and the roughly 1,000 new leases under the Path Forward plan.
Execution is still the test. These concepts need to open on time, pay agreed rents and support sales at neighboring shops to help justify high build out costs. If that plays out, it supports occupancy, NOI and potentially gives Macerich more flexibility as it works through debt, interest expense and future refinancing.
Macerich's narrative projects US$1.2b revenue and US$96.8 million earnings by 2029. This assumes revenue growth of 3.8% per year and an earnings swing of about US$267.2 million from the current earnings loss of US$170.4 million to the forecast consensus earnings level.
Uncover why Macerich's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some analysts focus less on Macerich’s restaurant roster and more on long term e commerce risk. The most cautious forecasts from before this dividend and leasing news penciled in roughly flat revenue at about US$1.0b by 2029 and earnings near US$90.7 million. That is a materially harsher script and a reminder to compare several narratives before deciding what you believe might change next.
Explore 2 other Macerich fair value estimates, including one that suggests it could be worth just $26.56.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgement.
- A great starting point for your Macerich research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Macerich. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it straightforward to evaluate Macerich's overall financial health at a glance.
Looking For More Ideas Beyond Macerich?
If you want to pressure test your view on Macerich against other opportunities, a quick sweep through the Simply Wall St Screener can surface very different types of companies built on clear fundamentals and specific risk profiles.
- If you care most about valuation support and business quality, scan through 36 high quality undervalued stocks that combine healthier cash profiles with more conservative pricing.
- If balance sheet resilience is your anchor, filter for a list of solid balance sheet and fundamentals (24 results) that can better absorb funding pressure and rate swings.
- If capital preservation is front of mind, focus on a 29 resilient stocks with low risk scores where the overall risk score screens lower than the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com