


Did Physical AI Safety Suite Just Shift Accenture's (ACN) Investment Narrative?
- In October 2026, TÜV SÜD AG and Accenture presented a Physical AI Safety Suite built on NVIDIA technologies to digitize parts of industrial automation certification using digital twins, AI agents and simulations that assess factory and warehouse layouts before deployment.
- The project targets a core operational bottleneck for Accenture’s industrial and logistics clients by aiming to bring production online up to 30% sooner through partially digitized safety assessments and structured evidence generation for certification.
- We will look at how Accenture's investment narrative is shaped by this Physical AI Safety Suite push into industrial automation certification.
Scan beyond Accenture and see how other physical AI and robotics plays stack up in our hand picked list of 95 robotics and automation stocks for this theme.
Accenture Investment Narrative Recap
To hold Accenture, you need to believe the consulting giant can keep turning its AI and cloud partnerships into steady project flow and margin support, even while headline growth expectations remain moderate. The Physical AI Safety Suite fits that story by deepening Accenture’s role in industrial automation, though it does not suddenly remove near term exposure to slower consulting demand in some regions.
The key short term swing factor remains how effectively Accenture converts its AI buzz into booked work and recurring style revenue, while managing federal and EMEA softness. The biggest near term risk is that lengthened decision cycles or public sector weakness drag on bookings, muting the benefit of high profile AI launches like this TÜV SÜD collaboration.
The most relevant related move is Accenture’s broader push into AI driven enterprise reinvention through deep partnerships with providers such as Google, NVIDIA, Anthropic and OpenAI. The Physical AI Safety Suite sits inside that same toolkit, aimed at giving industrial clients more structured, software like ways to deploy automation in warehouses and factories.
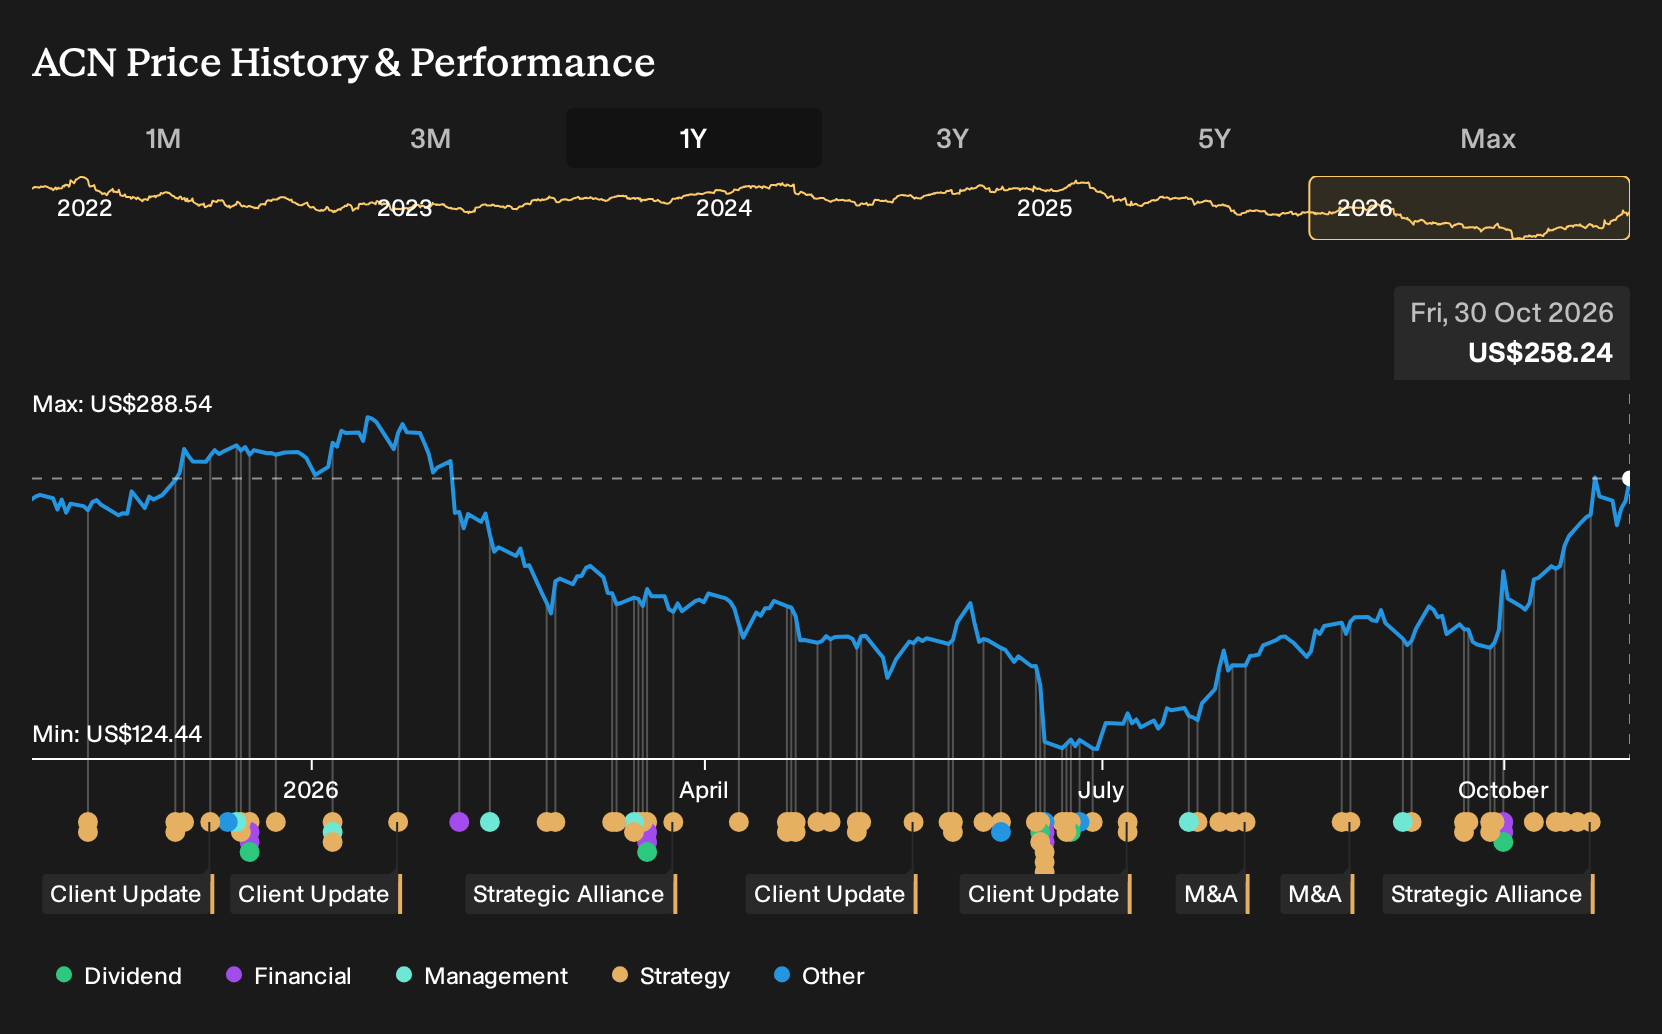
For you as a shareholder, the link is simple. If these AI launchpads and platforms translate into more non FTE, repeat style revenue, they may help offset cyclical consulting pauses and support earnings quality. If client caution or operational hiccups limit adoption, the risk is that recent share price strength outpaces the cash flows these AI collaborations actually produce.
Accenture's current narrative focuses on analysts expecting revenue to reach US$86.2b and earnings to come to US$10.2b by 2029. This is based on forecast yearly revenue growth of 5.1% and an earnings increase of about US$1.8b from current earnings of US$8.4b.
Uncover why Accenture's fair value indicates a 12% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts already saw Accenture differently before this TÜV SÜD news. They were leaning on a more aggressive AI project pipeline, with forecasts around US$91.4b of revenue and US$10.7b of earnings by 2029, and a higher implied P/E of 18.8x. You do not need to agree. Treat this Physical AI Safety Suite update as a fresh data point and explore how your own view might shift relative to both cautious and upbeat forecasts.
Explore 8 other Accenture fair value estimates, including one that suggests as much as 17% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Accenture research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Accenture. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Accenture's overall financial health at a glance.
Looking For More Investment Ideas Beyond Accenture?
If this TÜV SÜD collaboration has sharpened your view on Accenture, use that momentum to widen your watchlist. A broader set of ideas lets you compare risk, income and quality instead of anchoring everything to a single stock.
- If you want potential upside with companies that are still small but financially tested, check out 8 elite penny stocks with strong financials that pass tighter balance sheet and cash flow filters.
- For investors who care most about paying a reasonable price for strong fundamentals, take a look at a curated pool of 36 high quality undervalued stocks that combine solid cash generation with healthier balance sheets.
- If resilience is your priority and you prefer steadier profiles, review a focused 29 resilient stocks with low risk scores that screens for lower risk scores and more durable financial setups.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com