


Polaris (PII) Returns To Profit As Valuation Debate Heats Up
Polaris (PII) has drawn fresh attention after reporting a return to profitability in its third quarter and unveiling the RZR Pro R Factory Boost, a competition-focused machine aimed at high-speed desert racing.
For investors watching the ticker, Polaris has enjoyed a 7.72% 7 day share price return and a 10.61% 30 day share price return after its earnings rebound and product news. However, the 1 year total shareholder return is still down 5.65% and the 5 year total shareholder return is down 42.91%. This indicates that momentum has improved in the short term, while the longer record remains weak.
Scan Polaris alongside other powersports and consumer durables opportunities with the hand picked 36 high quality undervalued stocks that combine cash generation with balance sheet strength.
Bulls argue Polaris has turned a corner after its earnings rebound and fresh product buzz. Bears point to multi year shareholder losses that remain steep. Which side do the numbers lean toward as you value the stock today?
Most Popular Narrative: 14% Undervalued
Against Polaris's last close of $59.41, the most followed narrative pegs a fair value of $68.73. This frames the current debate around whether recent execution and cost actions justify a higher valuation.
Expansion of lean manufacturing and plant optimization, which has already produced about US$240 million of structural savings and is described as only in the third inning, can keep operational EBITDA margins and incremental earnings supported even if headline revenue growth is modest.
See why 34 investors see Polaris as 14% undervalued.
Result: Fair Value of $68.73 (UNDERVALUED)
Still, moderating off road retail trends and pressure from higher fuel and interest costs could both squeeze Polaris if demand for big ticket items weakens further.
Find out about the key risks to this Polaris narrative.
Another View: Polaris Through a Cash Flow Lens
The narrative crowd leans on a fair value of $68.73, yet Simply Wall St's DCF model points to a future cash flow value of $53.19 with Polaris trading at $59.41. That implies the shares screen as expensive on cash flows. Which story carries more weight for you right now?
To unpack how this cash flow view is built, and what would need to change for the gap to close, Look into how the SWS DCF model arrives at its fair value.
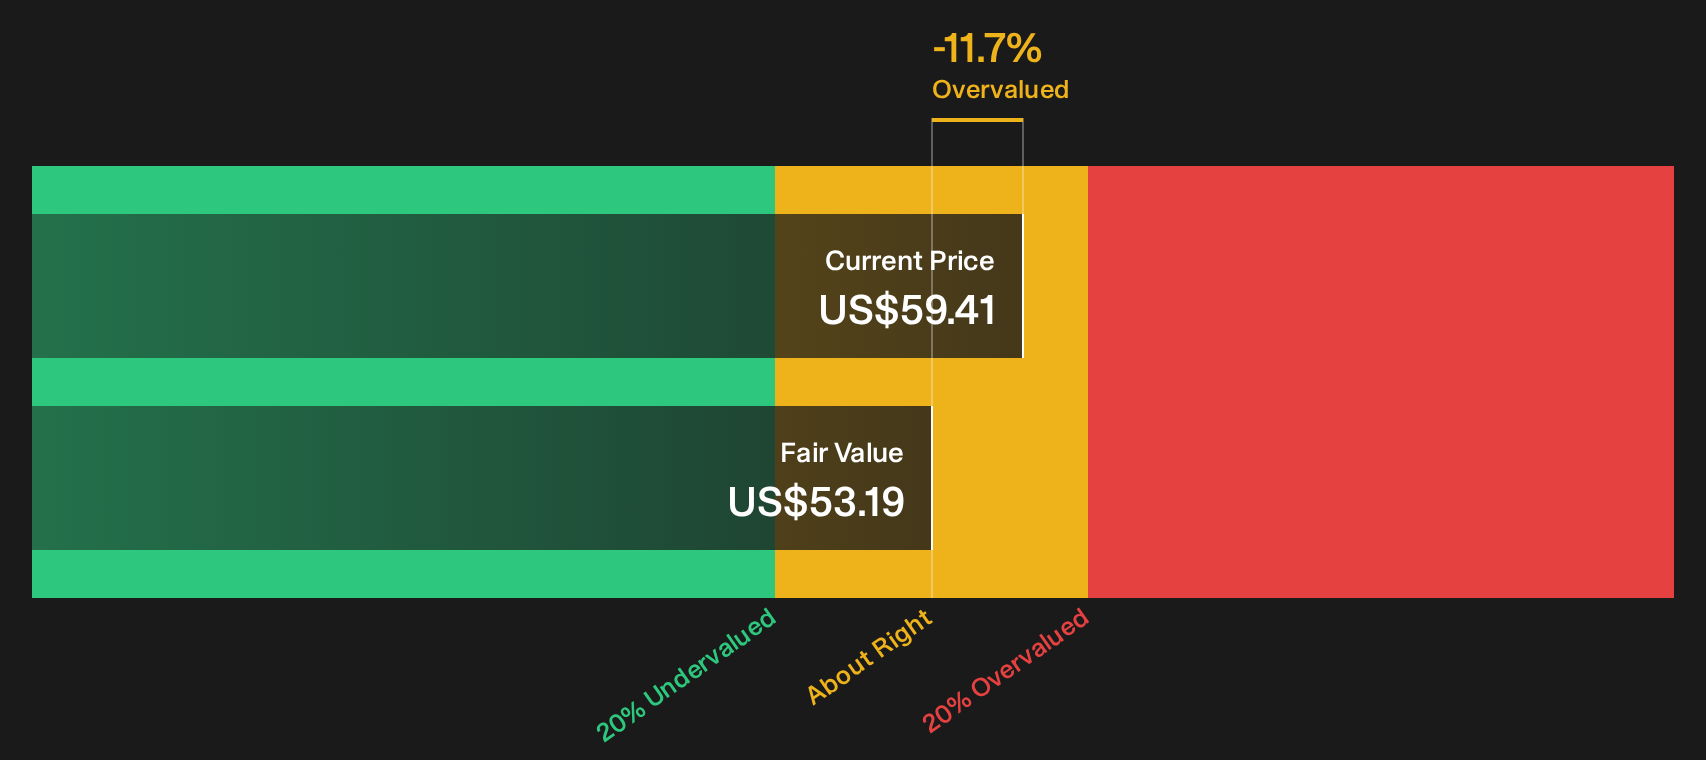
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Polaris for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages or early inflection, either way Polaris now splits opinion enough that it pays to review the data itself and move fast to shape your own thesis. Start with the balance between the 2 key rewards and 2 important warning signs.
Looking for more Polaris investment ideas?
If Polaris is on your radar, use this moment to widen your opportunity set with a few focused stock lists tailored to different priorities.
- Target potential mispricings by scanning companies that combine valuation appeal with solid fundamentals through the 36 high quality undervalued stocks.
- Prioritize balance sheet strength and financial resilience by running your eye over the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities by working through the 19 high quality undiscovered gems before others get there first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com