


BYD (SEHK:1211) Could Be 43% Undervalued On Flat Revenue And Softer Earnings
BYD (SEHK:1211) just reported nine-month earnings to September 30, 2026, with revenue holding near CNY 566.3b, while net income and earnings per share eased compared with the same period last year.
BYD's latest update landed as the share price closed at HK$70.45, with the 1 day share price return of 3.22% offering only a brief pause in a broader slide that includes a 90 day share price decline of 24.61% and a 1 year total shareholder return fall of 28.57%. This suggests that investors may be recalibrating expectations as profitability softens even while revenue holds steady.
Scan how other electric vehicle and battery players compare on profitability and share price momentum with our curated list of 200 high quality undervalued stocks.
BYD now trades well below recent levels after earnings showed flat revenue and softer profit. The key tension is simple: has most of the easy downside played out, or is the real upside still ahead from here?
Most Popular Narrative: 43% Undervalued
Against BYD's last close of HK$70.45, the most followed narrative anchors on a fair value estimate of HK$122.68 that is built using an 11.69% discount rate and assumes steady overseas expansion and improving profitability over time.
Planned expansion of BYD’s international sales to an expected 2.0 million vehicles in 2026 and 2.5 million vehicles in 2027, backed by investment in its own shipping fleet and overseas production, may add scale benefits that support revenue and earnings over time.
See why 14 investors see BYD as 43% undervalued.
Result: Fair Value of HK$122.68 (UNDERVALUED)
Still, weak domestic demand in China and rising policy barriers in higher priced regions could limit the extent to which BYD’s overseas push actually improves overall profitability.
Find out about the key risks to this BYD narrative.
Another View: BYD on Earnings Multiples
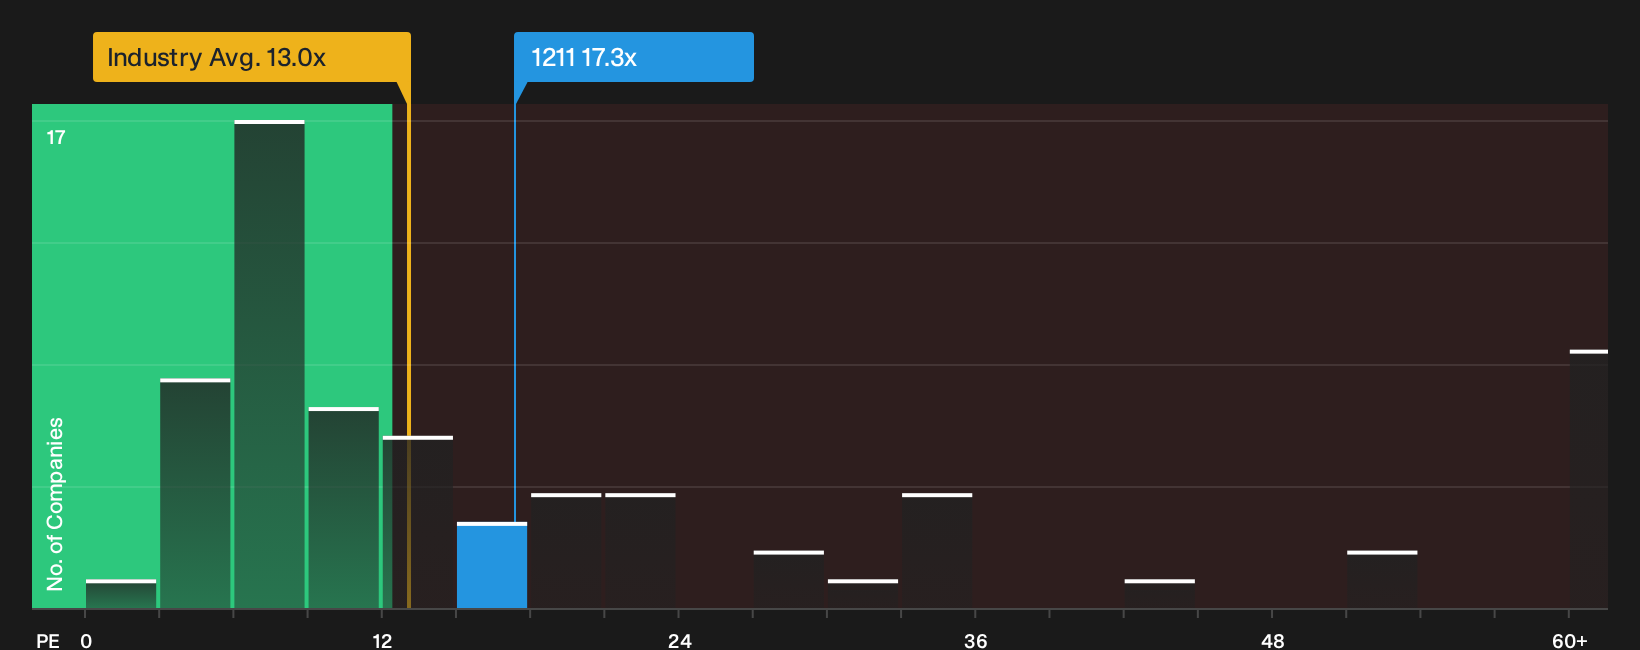
That 43% undervalued narrative leans on future cash flows and long term expansion. A different lens comes from today’s P/E ratios. BYD trades at 17.3x earnings, above the 13x Asian auto average and the 10.2x fair ratio level the market could move toward.
This combination of a higher current multiple, a lower fair ratio and a discount relative to peers highlights valuation risk if expectations reset, even though the stock appears inexpensive on some longer term models. Which yardstick do you rely on more when the story is tested next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk can spark debate, so move quickly, test the numbers yourself, and weigh 2 key rewards and 1 important warning sign
Looking for more ideas beyond BYD?
If BYD has you rethinking your watchlist, do not stop here. Fresh opportunities often sit just outside the stocks everyone is already debating.
- Spot potential mispricing early and track companies that may combine quality with depressed valuations through our focused list of 200 high quality undervalued stocks.
- Strengthen your income stream by scanning for payouts that may hold up better across cycles with a curated group of 223 dividend fortresses.
- Sleep easier by concentrating on financially robust businesses using the list of solid balance sheet and fundamentals (197 results), before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com