


Derwent London (LSE:DLN) In The AI Build Out Story As Investors Ask If It Looks Pricey
Recent commentary puts Derwent London (LSE:DLN) directly in the AI build out story, as landlords able to host both premium offices and data hungry occupiers draw fresh attention from investors tracking future tenant demand.
At a share price of £19.05, Derwent London has seen a 30 day share price return of 7.14%, although momentum has cooled recently with the 90 day share price return down 11.23% and a 5 year total shareholder return down 32.61%, contrasting with a 14.80% gain over 1 year.
Scan how other real estate and infrastructure plays are lining up for AI related tenant demand with our hand picked 54 AI infrastructure stocks alongside Derwent London.
Recent gains, longer term declines and a modest discount to analyst targets put Derwent London in an awkward middle ground. Is £19.05 already a fair reset, or is patience on price still your better ally as valuation work begins?
Price-to-Earnings of 43.5x: Is it justified?
On the current numbers, Derwent London changes hands at £19.05, which aligns with a P/E ratio of 43.5x that appears expensive compared with both peers and wider Office REIT benchmarks.
The P/E multiple compares what you pay today for each pound of earnings. For a landlord like Derwent London, it provides a quick sense of how much the market is willing to pay for its current profit stream, income profile and perceived resilience.
In this case, the gap is wide. The 43.5x P/E is significantly above the Global Office REITs industry average of 16.7x and also exceeds the peer group average of 20.6x. Relative to an estimated fair P/E of 19.2x, the current valuation appears stretched and would require meaningful earnings progress to close that spread rather than a simple compression of the multiple.
Explore the SWS fair ratio for Derwent London.
Result: Price-to-Earnings of 43.5x (OVERVALUED)
Still, the Derwent London story carries risk if office leasing demand weakens further or if higher interest costs start to pressure asset values and refinancing.
Find out about the key risks to this Derwent London narrative.
Another view on Derwent London’s value
The P/E screen says Derwent London looks expensive, yet our DCF model points to something even harsher. On estimated future cash flows, the SWS DCF model suggests a value of £6.09 per share, well below the current £19.05 level. This frames the stock as heavily overvalued on this lens.
When one approach flags rich earnings multiples and another implies a much lower cash flow value, which signal should carry more weight for you as an investor?
Look into how the SWS DCF model arrives at its fair value.
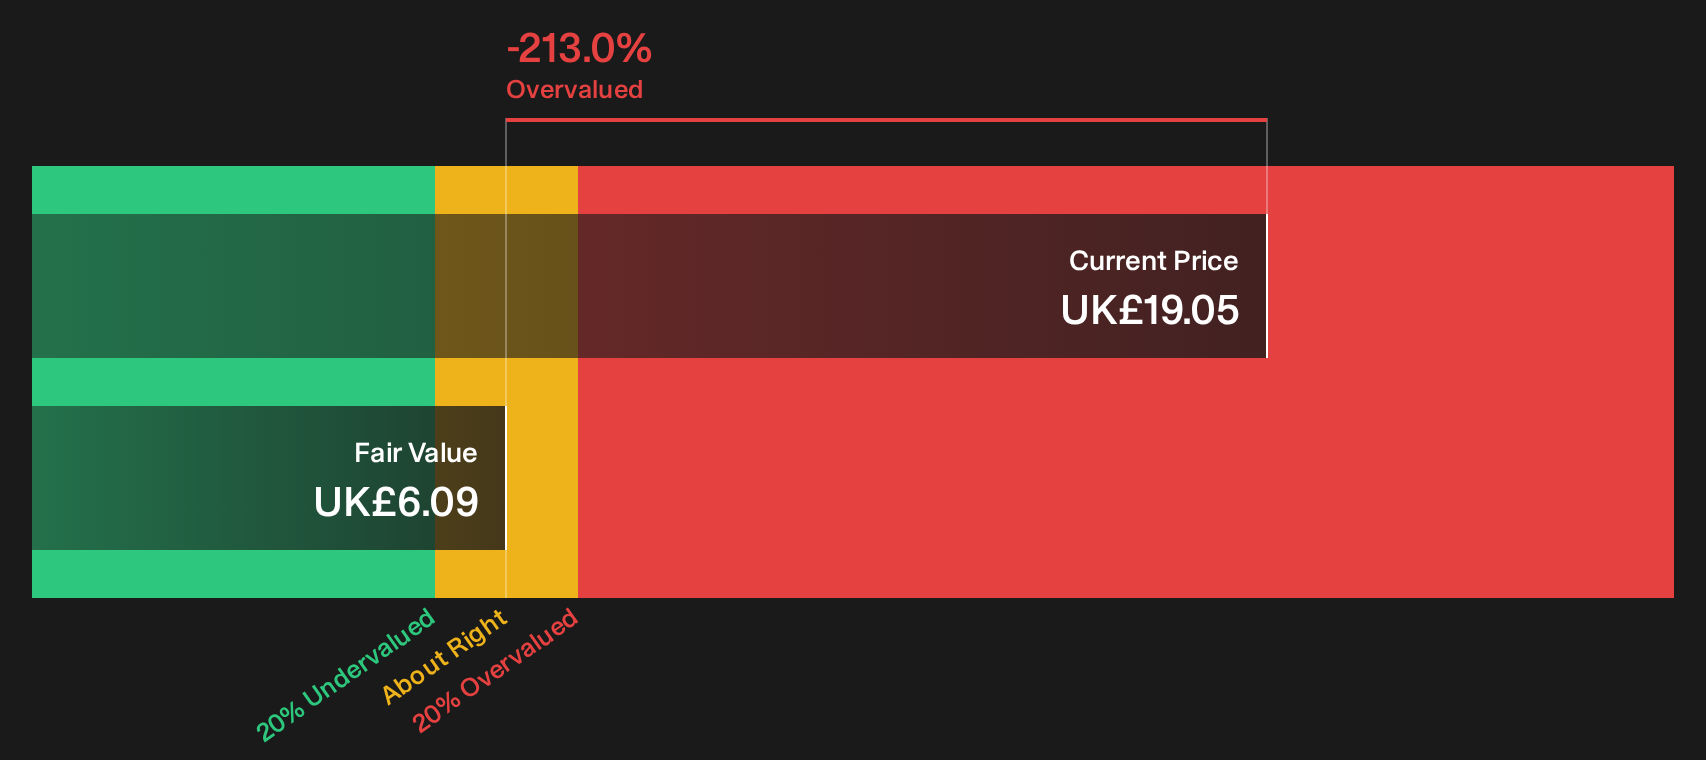
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Derwent London for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Derwent London can make the picture feel fuzzy. Act while the data is fresh and test the numbers against your own expectations using the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Derwent London?
If Derwent London has sharpened your focus on valuation, do not stop here. Use the Simply Wall Street Screener to pressure test fresh opportunities and avoid leaving potential upside on the table.
- Hunt for quality on sale by scanning our curated 14 high quality undervalued stocks that blend stronger fundamentals with prices that may still lag underlying business strength.
- Target resilient payers by reviewing the 5 dividend fortresses designed for investors who prioritise income durability alongside meaningful yield.
- Prioritise capital protection by using the 4 resilient stocks with low risk scores focused on companies with sturdier balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com