


What Ipca Laboratories Holders Bought Into
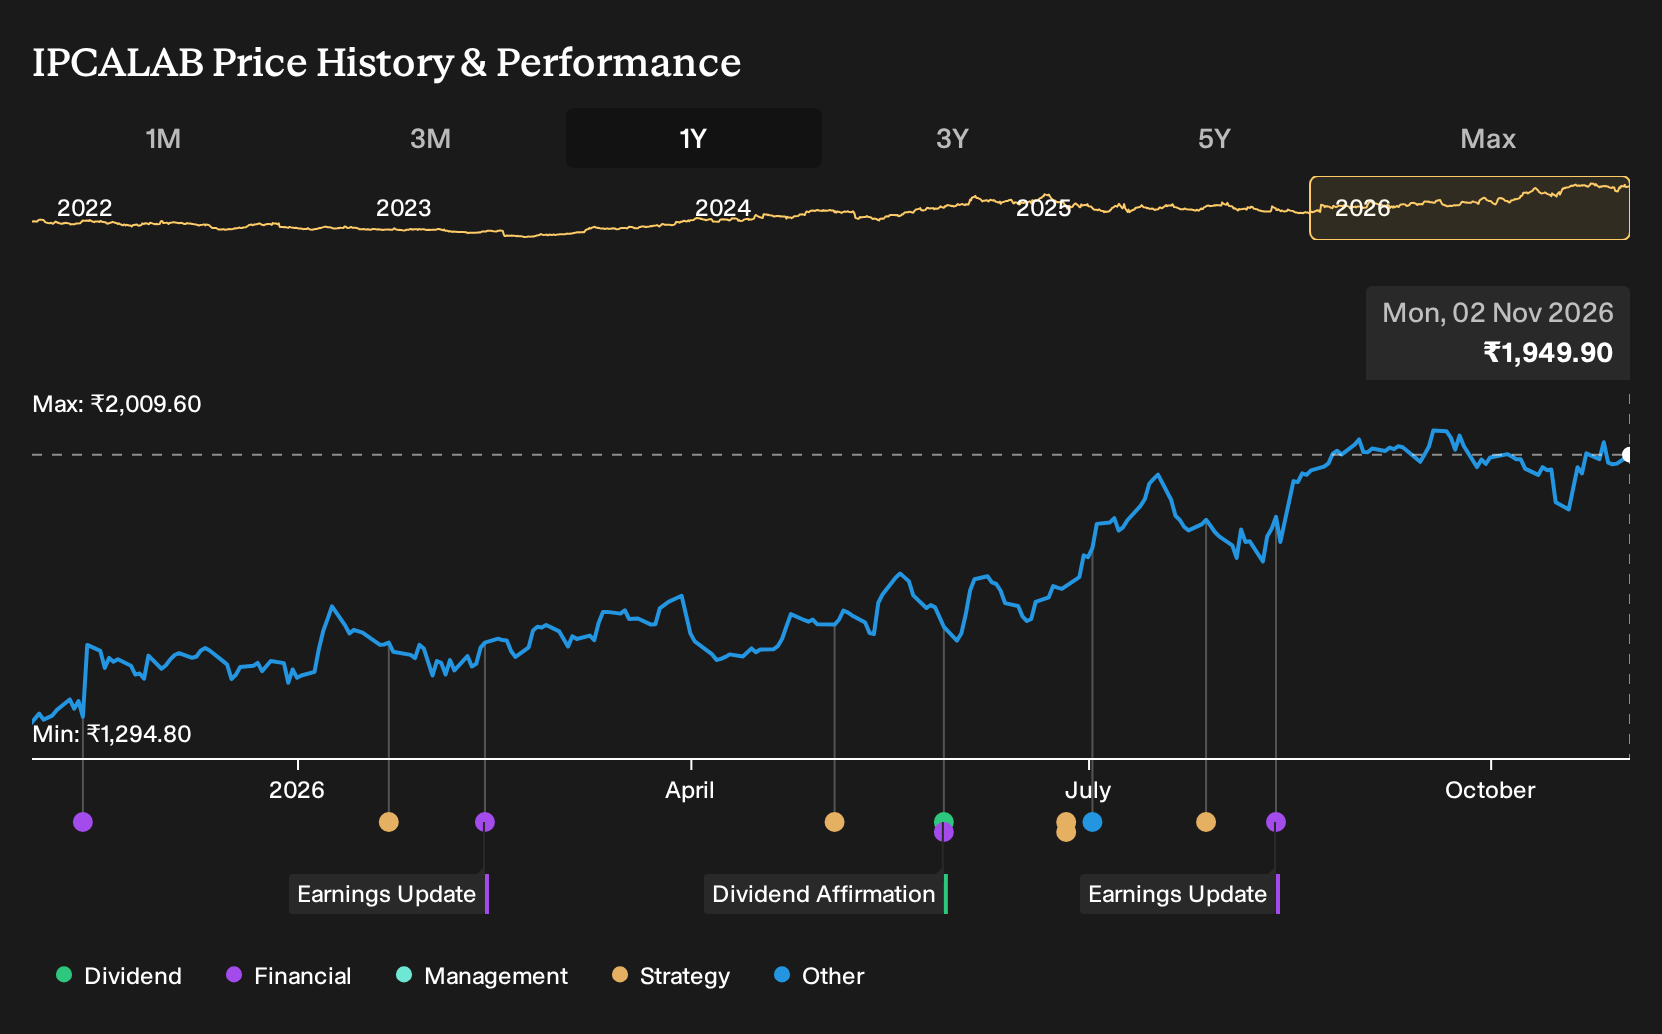
If you had bought Ipca Laboratories on 2 November 2025 and simply sat tight, the result would have been hard to ignore. Holding Ipca Laboratories over the past year would have returned 49.4%, including dividends. That sort of move naturally sends you back to the fork in the road. If you were weighing chronic-focused domestic growth, rising regulatory demands and mixed acquisition stories back then, which of those threads really mattered most for that call?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Ipca Laboratories. Zero in on 201 high quality undervalued stocks for companies trading below our estimates.
The Two Ipca Laboratories Stories Investors Were Debating
The shares cost ₹1,271 at the start of the period, and anyone looking at Ipca Laboratories then had to choose between two very different stories.
The bullish narrative put fair value at ₹1,496 and leaned on chronic therapies and active pharmaceutical ingredient capacity. Supporters focused on domestic chronic demand, more specialized sales teams in areas like cardiovascular and derma, and fresh regulatory filings from facilities such as Dewas.
The bearish view set fair value at ₹1,106 and highlighted regulatory and pricing strain. That camp focused on tighter global oversight lifting compliance costs, generic price pressure weighing on margins, and concentration risk if a key market or contract followed a path similar to South Africa.
What The Results Changed For Ipca Laboratories
The clearest fresh datapoint for Ipca Laboratories was the Q1 2027 result. Revenue was ₹27,881 million and net income was ₹4,018.9 million, compared with ₹23,088.5 million and ₹2,332.1 million a year earlier. Net margin moved from 10.1% to 14.4%. That pattern supported the more optimistic case that focused on chronic therapies, API capacity and better profitability.
The key lesson is simple. When a thesis leans on better earnings quality, treat net margin as the anchor figure and track whether each new result actually shifts that percentage in the claimed direction.
What Ipca Laboratories' Price Already Demands
Ipca Laboratories now trades at ₹1,950 after a 49.4% gain over the past year. This Narrative's Fair Value sitting below that level points to expectations already running high.
The selected Narrative argues that the key tension is whether richer chronic and branded mixes can outrun rising freight, raw material and biotech investment costs. A buyer at today's price would need confidence that new capex and R&D convert into enough profitable chronic and regulated-market revenue to offset those pressures.
"Key Takeaways: Bearish analysts expect Ipca Laboratories to face sustained pressure on growth and profitability as higher freight costs, raw material inflation, and losses at associates keep net margins under strain. The main factor that has to go right is that Ipca Laboratories converts its higher R&D spend, expanding biosimilars work, and ongoing capex into profitable chronic, branded, and regulated market businesses that offset logistics and input cost headwinds."
The price and this Narrative do not agree. → Uncover what this Narrative says Ipca Laboratories is actually worth
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 36% below our estimate - targets supplying high margin AI-focused chips and software to data centres.
- Company 2 - 43% below our estimate - expands higher priced digital forensics subscriptions as agencies adopt upgraded investigative tools.
- Company 3 - 45% below our estimate - increases investment in overseas store openings and digital projects to widen brand reach.
Those are three of them. See the full list of 197 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com