


11% Below Fair Value Following Strong Q3 Results At Eastern Bankshares (EBC)?
Eastern Bankshares (EBC) drew fresh attention after its third quarter update combined higher net interest income and net income with lower loan charge offs, along with ongoing share repurchases and an affirmed quarterly dividend.
At a share price of $22.39, Eastern Bankshares has given investors a year-to-date share price return of 20.77%, while the 1-year total shareholder return of 33.25% and 3-year total shareholder return of 115.26% point to strong momentum building over a longer stretch.
Seize the momentum around Eastern Bankshares, and compare it with other banks focused on solid balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (24 results).Eastern Bankshares has already rewarded holders this year, and the business now pairs that share price run with higher net interest income, positive nine month earnings and active capital returns. Does that mix still offer an appealing entry on valuation?
Most Popular Narrative: 11% Undervalued
Against the latest close at $22.39, the most followed narrative pegs Eastern Bankshares’ fair value at $25.13, suggesting the current price bakes in relatively cautious expectations and puts the emphasis on how loan mix and fee income evolve from here.
The successful merger with Cambridge Trust and the more recent integration work around HarborOne create a broader Eastern Bankshares franchise in Greater Boston, Eastern Massachusetts and New Hampshire. Management now reports this combined business as delivering record operating profitability, which supports the view that further scale benefits could continue to support revenue and earnings.
See why 2 investors see Eastern Bankshares as 11% undervalued.
Result: Fair Value of $25.13 (UNDERVALUED)
Still, the Eastern Bankshares story relies on deposit costs staying manageable and 2026 net interest income targets not slipping further; otherwise, the undervaluation case weakens fast.
Find out about the key risks to this Eastern Bankshares narrative.
Another View: Eastern Bankshares Looks Priced Richly On Earnings
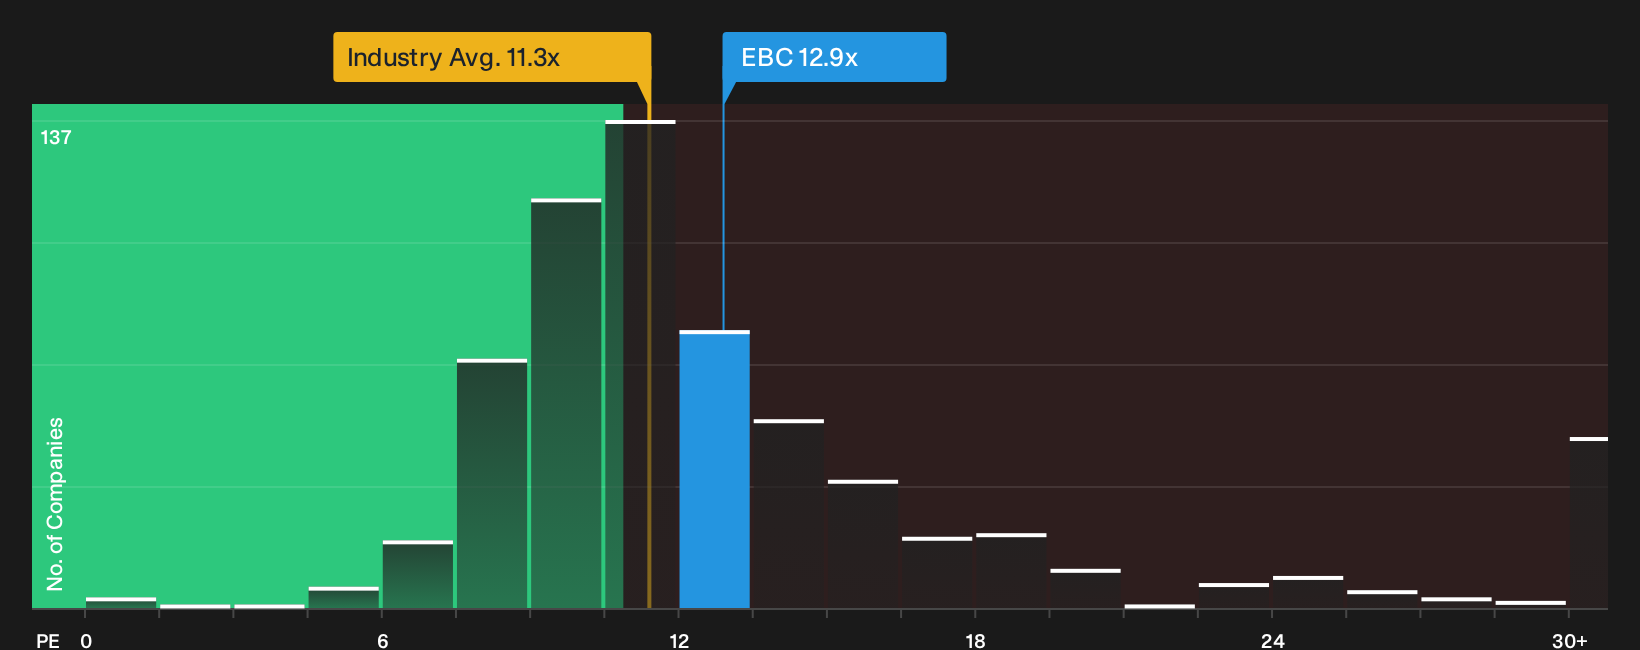
There is a clash between models here. While one framework points to Eastern Bankshares trading below fair value, the simple P/E check paints a tighter picture, with the bank at 12.9x earnings compared with 11.3x for the wider US Banks group, 10.6x for peers and a fair ratio of 12.6x.
That gap is not huge in absolute terms. However, it means anyone buying today is paying more per dollar of earnings than both the sector and close comparables, while only getting a slight cushion versus where the fair ratio suggests the market could move.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Eastern Bankshares is mixed, with clear strengths and real concerns sitting side by side, so consider acting promptly and weigh the evidence yourself by reviewing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Eastern Bankshares?
If Eastern Bankshares has your attention, do not stop here. Use the same disciplined mindset to scan other opportunities that might fit your goals just as well.
- Target companies the market may be overlooking by running your own hunt for value with the 36 high quality undervalued stocks.
- Strengthen your income stream by reviewing resilient payers through the 5 dividend fortresses.
- Prioritise stability first and hunt for potential opportunities in the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com