


US Stock Market Today: S&P 500 Futures Edge Up On Key Manufacturing And Jobs Data
The Morning Bull - US Market Morning Update Monday, Nov, 2 2026
US stocks are set for a cautiously positive open, with futures slightly higher as attention locks onto the week’s heavy US data calendar. The tone feels constructive, but it is entirely data dependent.
The key driver today is the ISM Manufacturing PMI at 3:00 PM, with consensus at 54.6 after a previous 54.5 reading. Alongside that, fresh readings on ISM manufacturing employment will feed directly into how investors think about the Federal Reserve’s next steps.
These surveys shape expectations for growth and policy, which filter straight into borrowing costs across the economy. Firmer manufacturing and hiring data can support earnings expectations, while also keeping pressure on funding costs for more indebted companies and interest rate sensitive sectors.
The open question is whether this week’s US data cluster, from ISM and JOLTS to factory orders and jobs, confirms a still resilient backdrop or hints at cooling momentum that could eventually shift the Fed’s tone.
Stocks to Watch Before the Opening Bell
Lumentum Holdings (LITE)
Lumentum posted first quarter fiscal 2027 results that management described as showing growth across all parts of the business, with pump lasers and optical circuit switches key contributors. The firm also secured a second major NPO or CPO win with purchase commitments above US$5b, and guided to higher Q2 revenue with a projected non GAAP operating margin above 45%.
Tesla (TSLA)
Tesla’s new FSD v14.3.13 software is under scrutiny after user reviews flagged performance regressions and one reported crash during an unprotected left turn. The update is already on more than 30% of the fleet, and Cybertruck owners are also reporting weaker FSD behavior. Watch for any regulatory attention, company communication on fixes, or further telemetry based updates.
Broadridge Financial Solutions (BR)
Broadridge is partnering with the New York Stock Exchange on its tokenized securities platform, adding on chain shareholder governance and digital transfer agency services after regulatory clearance. The NYSE will use Broadridge smart contracts to link tokenized shares with meeting agendas and voting rules. Investors tracking market plumbing and tokenization may treat this as a real world test case.
Top Movers
- Regeneron Pharmaceuticals (REGN) jumped 13.33% after reporting strong Q3 earnings, higher revenue, dividend affirmation, and buyback progress.
- Global Payments (GPN) climbed 12.97% on reports of take-private talks with CD&R and GTCR, including a potential premium.
- Rocket Companies (RKT) advanced 7.38% following Q3 results showing higher revenue and profit, plus mixed but constructive analyst target updates.

Top Losers
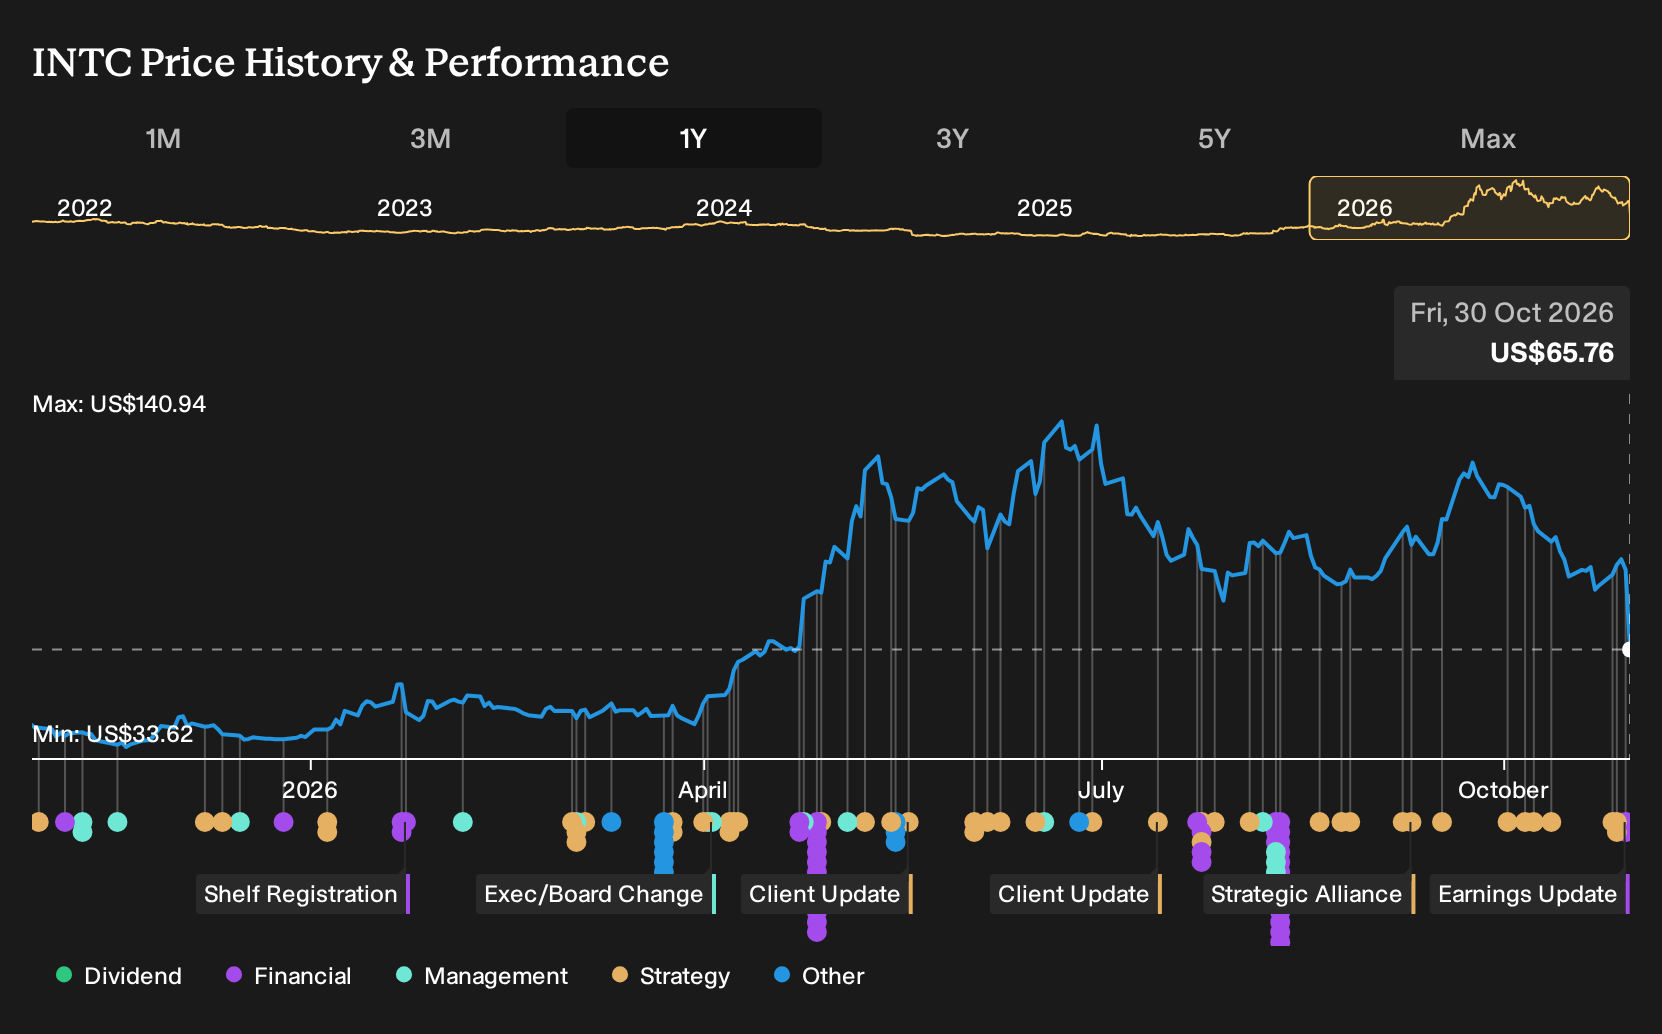
- Intel (INTC) fell 28.58% after weak Q4 guidance, PC market softness, a fab accident, and widespread analyst target cuts.
- Illumina (ILMN) declined 18.64% after Q3 results, the impact of the China Unreliable Entities List, and mixed guidance changes unsettled investors.
- Roblox (RBLX) dropped 18.05% after a cautious holiday bookings outlook, concerns over user trends, and multiple price target reductions from brokers.
On The Radar
US trading revolves around this week’s labour and Fed signals, with a heavy run of payroll data, ISM surveys and high profile earnings all feeding into rate expectations.
- ISM Manufacturing PMI & Employment, US Mon 2 Nov. A manufacturing reading around the 54.6 consensus and employment index near the 53 forecast would point to steady factory activity, which tends to keep borrowing costs and the US dollar under pressure rather than easing.
- JOLTs Job Openings, US Tue 3 Nov. Openings are projected around 7.13m versus the prior 7.079m. Any reading clearly below that range would signal cooler labour demand that can take some heat out of wage pressures and longer dated yields.
- ADP Employment Change, US Wed 4 Nov. Private payrolls are expected at 65k against 90k previously. A softer print would add to the idea of a gentler jobs market, which often helps rate sensitive sectors like housing and utilities.
- Non Farm Payrolls & Unemployment Rate, US Fri 6 Nov. Consensus sits at 65k jobs and a 4.2% jobless rate. A clear upside surprise in hiring or wages would lean toward firmer Fed policy expectations and a stronger US dollar.
- Apple (AAPL) and mega cap earnings cluster Mon 2 Nov to Wed 4 Nov. Results from Apple, AMD, McDonald’s, Qualcomm and Uber put the focus on guidance and revenue across hardware, chips, consumer spending and mobility. These releases often steer the wider US indices on heavy volume days.
Sector & Industry Watch
Tech: AI spending meets political spotlight
Tech has eased over the past week, with a 7 day decline a bit above 2% and a weaker 30 day patch, while 1 year performance is still positive. Heavy AI and data center budgets at Microsoft, Apple and others now run alongside market questions about free cash flow, bond funded projects and fresh election related scrutiny of big platforms.
If a large slice of your portfolio leans on software, cloud or IT infrastructure, today’s ISM Manufacturing PMI is the macro check to watch because a firm reading can keep rate cut hopes subdued, which feeds directly into how investors price long dated AI projects.
Semiconductors: Chip stocks cool after strong run
Semiconductors have softened again, with the group down roughly 2.5% over 7 days on top of a weaker 30 day period, even though year to date and 1 year returns are ahead of the broader US Market. Headlines around Nvidia, Intel and Qualcomm highlight how sensitive chip demand is to AI server orders, export rules and any hint that customers may slow new fab or data center commitments.
If you hold chip ETFs or GPU exposed stocks, Friday’s US Non Farm Payrolls is the key catalyst because a stronger jobs print can keep bond yields firm, which often weighs most on sectors where a lot of the appeal comes from future earnings.
Energy & Oil and Gas: Higher crude keeps cash stories in focus
Energy and Oil and Gas have both edged higher over the past week, with 7 day gains near 1% sitting on top of very strong 12 month returns around the mid 50% area. News around Kosmos Energy’s debt reduction, Venture Global’s LNG start up and OPEC holding output targets, alongside analyst calls for Brent near US$105, keep attention on balance sheets and shareholder payouts rather than fast volume growth.
If you own US producers, refiners or LNG exporters, the single data point to track is Wednesday’s EIA crude inventory report since any sign that US stockpiles are tightening again can influence how comfortable the market feels with current pricing for the sector.
Healthcare & Pharmaceuticals & Biotech: Drug and device data back defensive roles
Healthcare and Pharmaceuticals & Biotech continue to run ahead of the US Market on 7 day, year to date and 1 year returns, with Pharma and Biotech up close to 5% over the week. Fresh clinical results from Abbott, Heartflow, Merck, Johnson & Johnson and others keep the story centered on treatments for heart disease, HIV and complex procedures rather than day to day consumer spending.
If you use these groups as a stabiliser in your portfolio, Thursday’s US Initial Jobless Claims and nonfarm productivity prints matter because they shape how steady employer healthcare budgets and government funding may look heading into the next round of Fed communication.
Consumer Discretionary & Automobiles: Autos bounce but questions linger
Consumer Discretionary has picked up recently, with a 7 day gain just above 1% even though the sector is down around 10% over 12 months, while Automobiles have rebounded more sharply with a roughly 7% 7 day move after a tougher year. Tesla software headlines, strong October delivery updates from XPeng and NIO and new partnerships around AI in vehicles show plenty of activity even as the industry still works through earlier profit pressures.
If you are exposed to car makers or broader discretionary retail, Tuesday’s US JOLTS job openings report is the key release because signs of softer hiring can cool wage growth and borrowing appetite, which directly affects auto financing and big ticket spending.
How To Act On Today's Market
With energy and oil and gas edging higher over the past week and 12 month returns around the mid 50% area, start by comparing your holdings with this list of list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com