


Bristol Myers Squibb Stock: Is Wall Street Bullish or Bearish?
Headquartered in Princeton, New Jersey, Bristol Myers Squibb Company (BMY) is a global biopharmaceutical company that discovers, develops, and commercializes innovative medicines for serious diseases, particularly in oncology, hematology, and neuroscience. The company has a market capitalization of $127.6 billion.
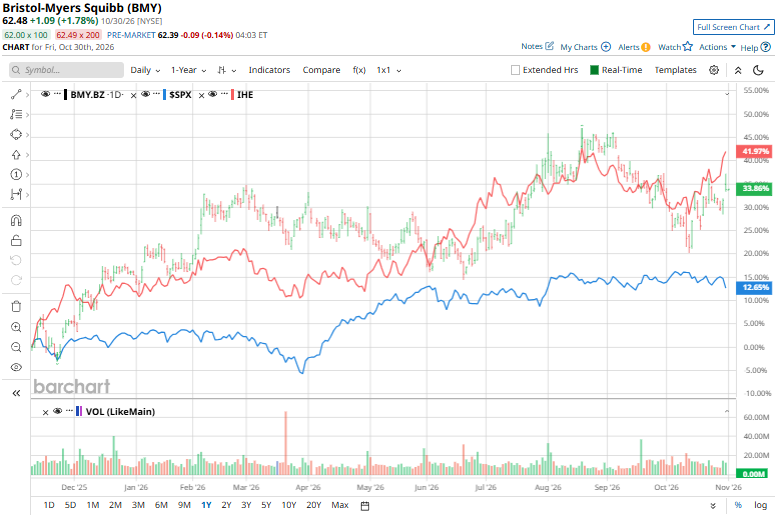
Shares of the biopharmaceutical company have outperformed the broader market over the past year. BMY has gained 37% during this period, compared with an 11.1% advance for the S&P 500 Index ($SPX). The stock has maintained its lead in 2026, gaining 15.8% year-to-date, while the S&P 500 has advanced 10.7% over the same period.
However, BMY has slightly underperformed the iShares U.S. Pharmaceuticals ETF (IHE), which has climbed 43% over the past year and gained 26.9% year to date.
On October 29, Bristol Myers Squibb reported its Q3 2026 earnings, with shares rising 1.4% that day. Revenue increased 6.9% year over year to $13.07 billion, driven by 12% growth in the Growth Portfolio to $7.66 billion, primarily supported by Opdivo Qvantig, Breyanzi, Reblozyl, Camzyos, and Opdualag. Legacy Portfolio revenue grew 1% to $5.42 billion. However, non-GAAP EPS declined 17.2% to $1.35 from $1.63 in the prior-year quarter, while non-GAAP gross margin fell 450 basis points to 68.4%, primarily reflecting a change in product mix and, to a lesser extent, a one-time contract termination charge.
For full-year 2026, Bristol Myers Squibb raised its revenue guidance to $49.75 billion to $50.25 billion from $49 billion to $50 billion. However, it lowered its non-GAAP EPS guidance to $6.35 to $6.55 from $6.75 to $7, reflecting an expected $0.60-per-share net impact from acquired in-process research and development (IPRD) charges and licensing income, compared with $0.02 previously. The company maintained its gross margin guidance of approximately 69% to 70% and operating expense guidance of approximately $16.5 billion, while lowering its expected other expense to approximately $650 million from $700 million.
Beyond its quarterly results, BMY also reported progress in its oncology pipeline. On October 26, 2026, the company and SystImmune announced positive Phase 3 results for investigational cancer drug izalontamab brengitecan (Iza-bren). The treatment doubled median progression-free survival to 11.1 months, compared with 5.7 months for chemotherapy, reducing the risk of disease progression or death by 60%. With clinical benefit demonstrated across five cancer indications, Iza-bren represents a promising pipeline opportunity that could support BMY’s long-term oncology growth.
Analysts expect BMY’s diluted EPS to increase 4.1% year over year to $6.40 for the fiscal year ending in December 2026. Meanwhile, the company has exceeded consensus EPS estimates in each of the past four quarters, reflecting a consistent track record of earnings beats.
Of the 30 analysts covering BMY, the consensus rating is “Moderate Buy.” This assessment comprises 12 “Strong Buy” ratings, one “Moderate Buy” rating, 16 “Hold” ratings, and one “Strong Sell” rating.
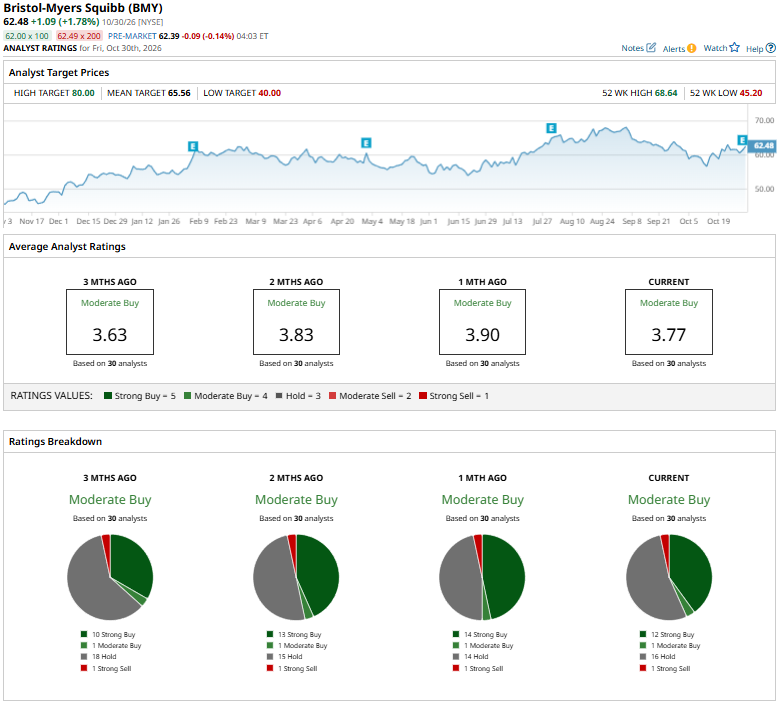
This consensus reflects a more bearish outlook than a month ago, when the stock had 14 “Strong Buy” ratings.
On October 30, 2026, Wells Fargo analyst Mohit Bansal lowered his price target on Bristol Myers Squibb to $60 from $65, while maintaining an “Equal Weight” rating.
Based on analysts’ estimates, the mean price target of $65.56 implies a 4.9% premium to BMY’s current share price, while the Street-high price target of $80 suggests a 28% upside.
On the date of publication, Abhishek Bhuyan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.