


What Investors Overlooked Before Claritev Fell 63%
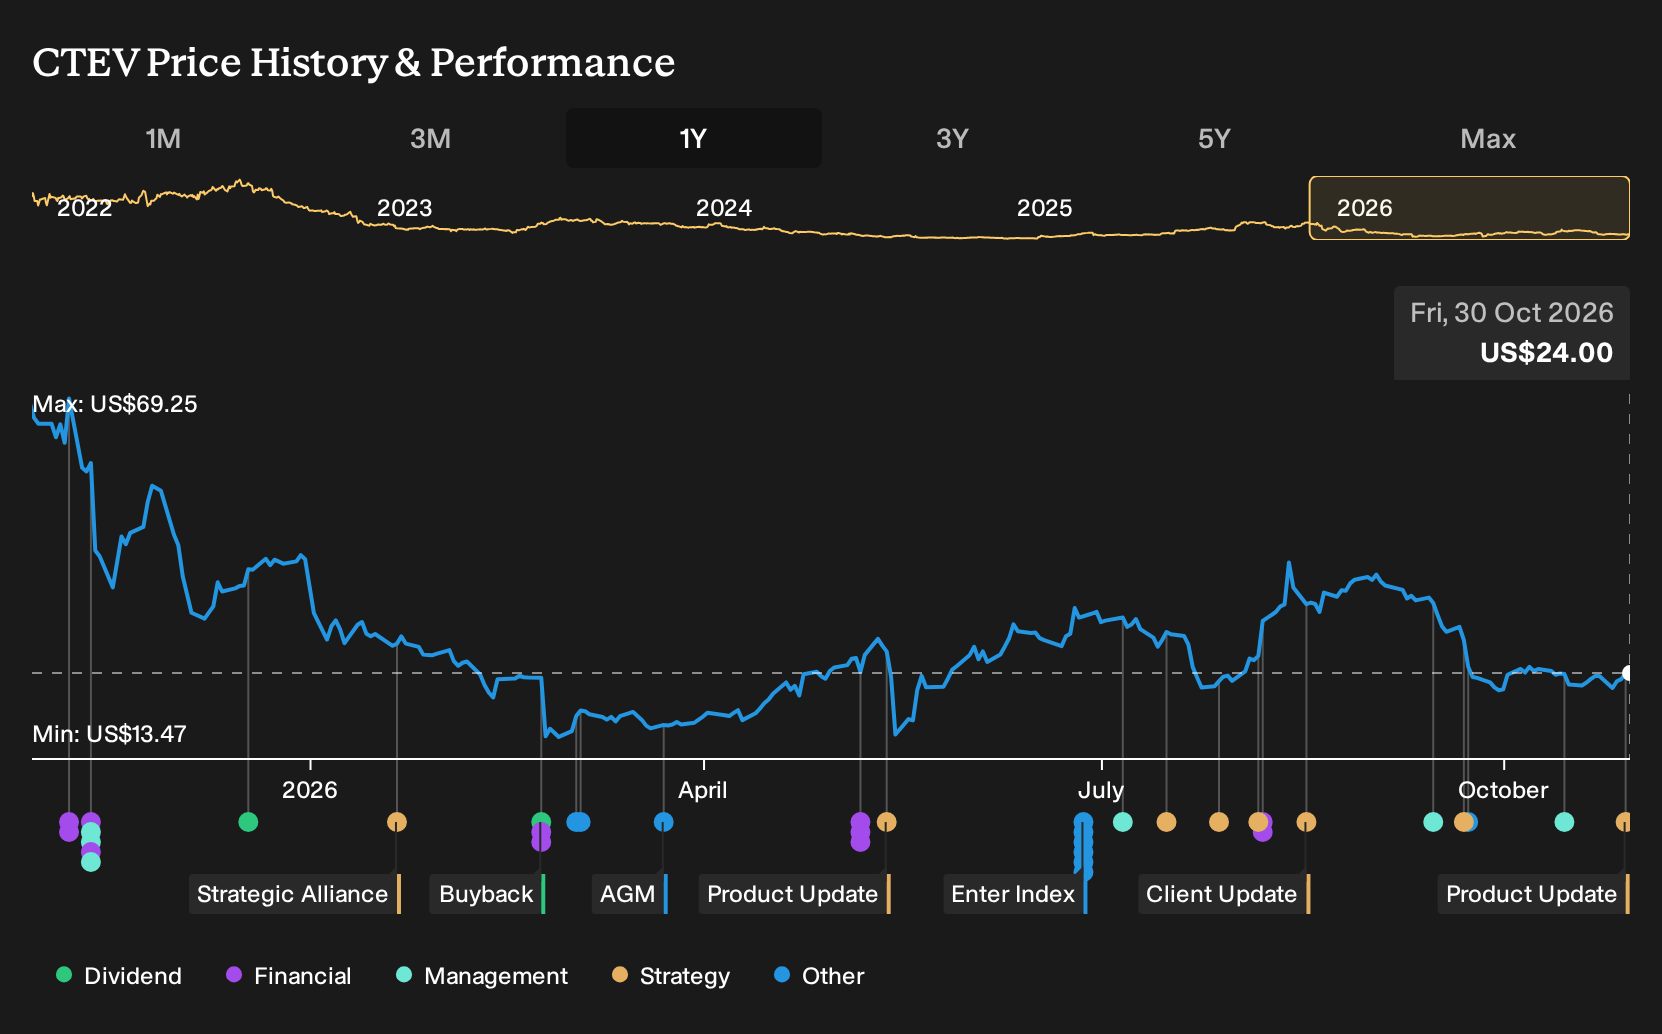
Claritev’s recent launch of its Transparency-Based Pricing solution, using public data and AI inside payer workflows, looked like exactly the kind of product many investors had hoped for when they bought in. Investors who held Claritev over the past year are down 63.1%, including dividends. If you had committed fresh capital back in October 2025, how should this mix of new products and still loss-making results change what you expect next?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Claritev has already moved. Pinpoint other ways to investigate the theme among 33 healthcare AI stocks.
The Two Claritev Stories Investors Had To Weigh
The shares cost US$66.06 at the start of the period, so any thesis on Claritev had to earn its way against that entry price.
The optimistic narrative pointed to a fair value of US$70.50, built on annual revenue growth of 3.1% and an assumed profit margin rising to 8.8% within three years.
The more cautious script put fair value at US$55.00, with a 3.4% revenue growth assumption but concern that rising regulatory and compliance costs would strain margins.
What The Evidence Did To The Claritev Argument
Claritev’s launch of its Transparency-Based Pricing tool gave the optimistic case something concrete, since it put AI and public data to work inside existing claims workflows. Reported Q2 2026 figures added only modest comfort. Revenue and profit both rose against Q2 2025 and the net margin improved from a loss of 25.9% to a loss of 23.0%, so profitability ambitions remained unproven. Overall, the evidence cut both ways.
The episode turned on whether better tools would translate into healthier economics. For a different stock, you would test that same claim by watching reported net margin alongside product rollouts rather than assuming new launches alone justify the thesis.
Claritev: What The Fall To US$24 Really Asks You
Claritev now trades at US$24, and the selected Narrative places its Fair Value above that level based on a business case that leans on cloud and AI modernization plus expanding NSA driven offerings.
For the drop over the past year to look like an opening rather than a warning, a buyer would need confidence that heavy technology and go to market spending genuinely converts into the cost savings and productivity gains this Narrative describes.
"The main factor that has to go right is that Claritev’s multi year cloud and AI modernization delivers the planned cost structure reduction and productivity gains, while its expanded NSA, TPA, and public sector offerings continue to support record ACV bookings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 47% below our estimate - sells flash controllers as more customers outsource storage component design.
- Company 2 - 38% below our estimate - turns lidar pilot programs into broader deployments with increasing production scale.
- Company 3 - 20% below our estimate - scales a teahouse network as overseas outlets shift mix toward new regions.
Three companies from the same screener. Open the full list of 36 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com