


LGI Homes (LGIH), Why Is Attention Building Ahead Of Its Latest Update?
Earnings countdown refocuses attention on LGI Homes
LGI Homes (LGIH) reports earnings this Tuesday before the opening bell, with investors watching for the expected 9.2% revenue increase after last year's 39.2% decline and relatively steady analyst forecasts over the past month.
Recent trading tells a mixed story for LGI Homes. The share price has climbed 1.44% over the last day and 5.29% across the past week, yet it is still down 27.81% over 90 days and the three year total shareholder return has declined 59.39%. Short term momentum has picked up while longer term performance remains weak.
Scan how LGI Homes compares with other builders, where expectations and recent moves are starting to shift, by reviewing our curated list of 36 high quality undervalued stocks.
LGI Homes runs a focused, profitable homebuilding operation, yet the share price has fallen hard over the past three years while ticking up into this earnings print. Are you looking at a solid builder that is still mispriced?
Most Popular Narrative: 52% Undervalued
At a last close of $44.37 versus a narrative fair value of $93, LGI Homes screens as heavily discounted on this widely followed framework, putting the focus on whether its lot economics can defend margins.
The main thing that has to go right is that LGI Homes maintains margin resilience through its self-developed land, owned lot base and controlled construction costs, despite pressure on entry-level buyers and potential cost inflation.
The current narrative that LGI Homes is undervalued implies that the share price does not fully reflect its owned land position, backlog of contracted homes and guidance for homebuilding gross margins and community growth.
See why 7 investors see LGI Homes as 52% undervalued.
Result: Fair Value of $93 (UNDERVALUED)
Still, rising cancellation rates and potential increases in building material costs could quickly challenge the LGI Homes undervalued narrative if they squeeze margins that are already thin.
Find out about the key risks to this LGI Homes narrative.
Another View on LGI Homes' Valuation
The fair value narrative at $93 points to upside for LGI Homes, yet the SWS DCF model suggests a different story. On that cash flow view, LGIH at $44.37 sits above an estimated future cash flow value of $26.04, which screens as overvalued on this method. Which framework fits your own assumptions about margins and housing demand?
Look into how the SWS DCF model arrives at its fair value.
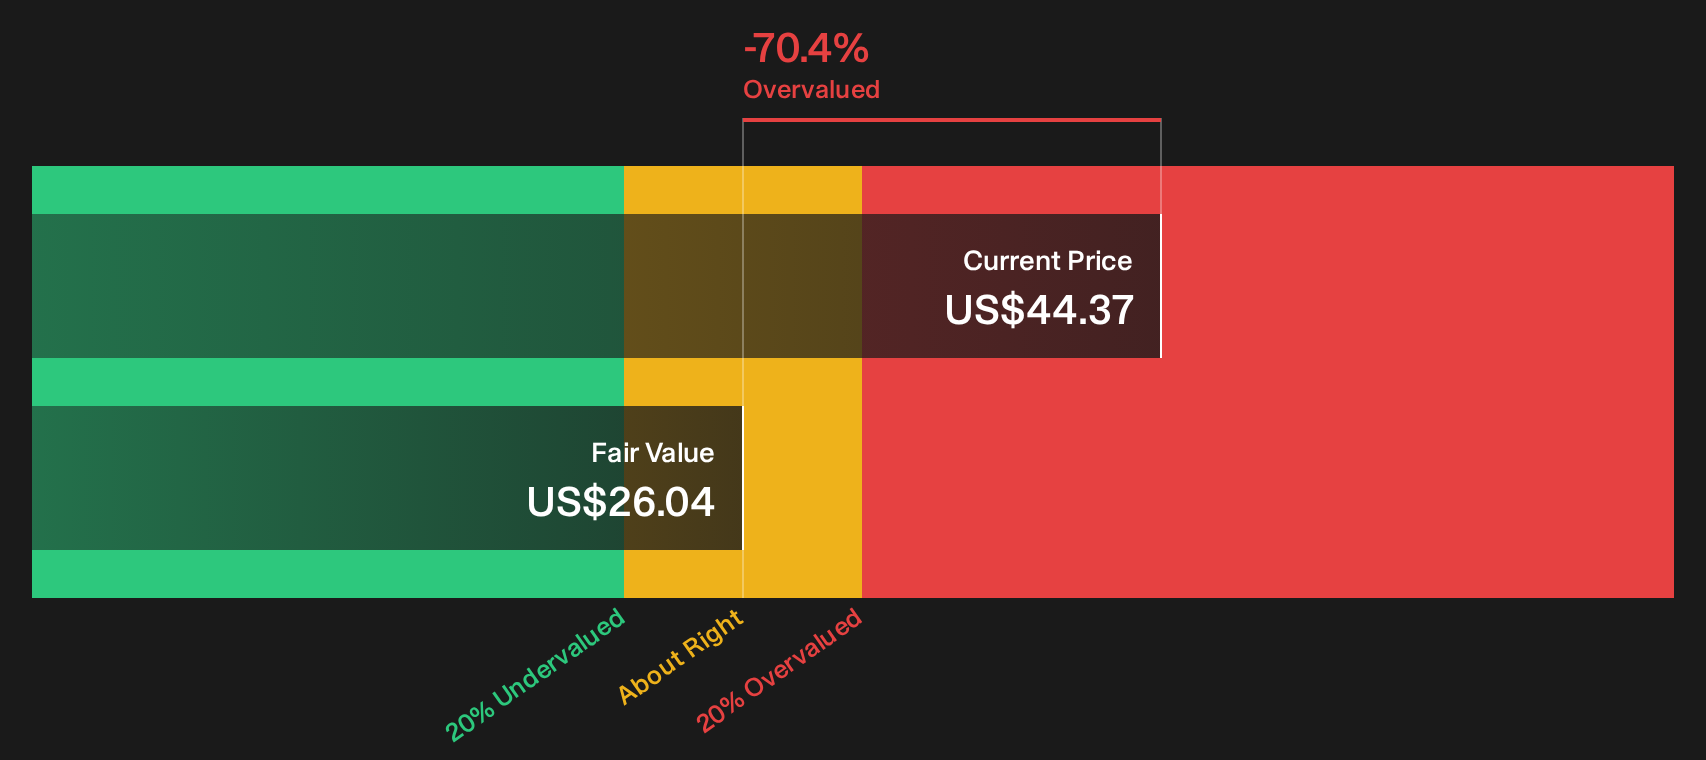
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LGI Homes for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on LGI Homes' value story. If you want a clear stance, act promptly and weigh the potential upside against the concerns by reviewing the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond LGI Homes?
Do not stop with one builder. If you want stronger context for LGI Homes, compare it with other opportunities that match your own risk and return preferences.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies with cash and fundamentals front and center.
- Hunt for mispriced quality and put together a watchlist from a curated 36 high quality undervalued stocks that highlights stocks where fundamentals and price look out of sync.
- Get ahead of the crowd by reviewing a 19 high quality undiscovered gems that focuses on lesser known businesses with strong financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com