


Abbott Laboratories (ABT) Posts Positive SonicForce Trial Data, Is The Stock A Bargain?
How the SonicForce trial update frames Abbott Laboratories stock
Abbott Laboratories (ABT) just reported positive month results from its TECTONIC study of the investigational SonicForce Coronary Intravascular Lithotripsy System, meeting safety and effectiveness goals for patients with severe coronary calcification.
The trial showed a 97% procedural success rate, with SonicForce used to treat complex coronary artery disease. For shareholders, that places fresh attention on Abbott Laboratories and its broader pipeline of heart devices.
Recent trading tells a mixed story for Abbott Laboratories. The 30-day share price return of 8.92% points to building short term momentum, yet the year to date share price return is down 14.49% and the 1 year total shareholder return has declined 12.11%. At the same time, the business is rolling out new heart devices, cancer diagnostics and a planned Nutrition spin off that continue to reshape the long term narrative around risk and opportunity.
Scan how Abbott Laboratories stacks up against other heart and diagnostics players by reviewing the curated 34 healthcare AI stocks that are already drawing fresh attention from investors.
Abbott Laboratories shares have bounced in the past month, yet analyst targets and intrinsic value estimates still span a wide range. Where does a fair price really line up in that spread?
Most Popular Narrative: 12% Undervalued
On the most widely followed view, Abbott Laboratories carries a fair value of $120.26 against a last close of $106.20. This frames SonicForce as one more data point in a broader device and diagnostics story that still is not fully reflected in the price.
The main thing that has to go right is that Abbott Laboratories continues to convert its medical technology pipeline in areas like continuous glucose monitoring, electrophysiology and cancer diagnostics into sustained sales growth and margin expansion, while managing Nutrition legal and regulatory risks.
The current valuation implies the market is treating Abbott Laboratories as a steady healthcare compounder, rather than fully pricing in the earnings contribution suggested by raised 2026 EPS guidance, margin progress and growth investments in Libre, electrophysiology and Cancer Diagnostics, which this narrative views as too low.
See why 192 investors see Abbott Laboratories as 12% undervalued.
Result: Fair Value of $120.26 (UNDERVALUED)
Still, the Abbott Laboratories story can change quickly if Nutrition legal costs flare up again, or if Libre manufacturing investments weigh more heavily on profit margins.
Find out about the key risks to this Abbott Laboratories narrative.
Another View: What Abbott Laboratories’ P/E Is Telling You
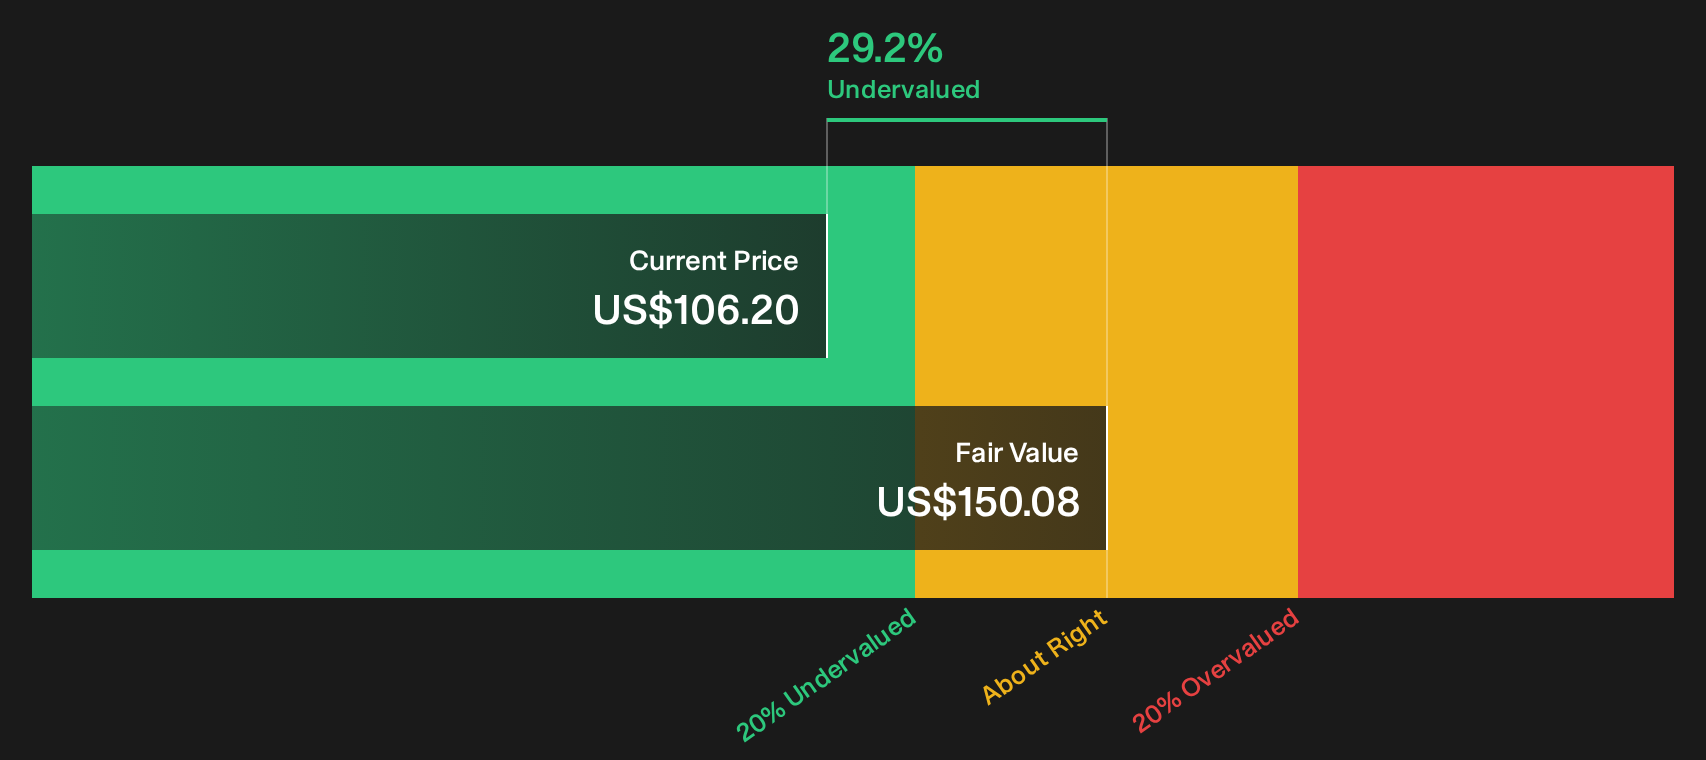
The SWS DCF model points to a fair value of $150.08 for Abbott Laboratories, which sits well above the recent $106.20 share price and supports an undervalued label. Yet the stock also trades on a rich 39.3x P/E. How comfortable are you with paying that multiple for this cash flow profile?
For readers who want to see exactly how that cash flow estimate was built, and how sensitive it is to different scenarios, Look into how the SWS DCF model arrives at its fair value..
Next Steps
Mixed signals on Abbott Laboratories so far, right? Use that tension as a prompt to move quickly, review the full set of data, and weigh the balance of risks and upsides for yourself through the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Abbott Laboratories?
Do not stop your research with Abbott Laboratories. Fresh opportunities often appear where fundamentals, value and resilience quietly line up before the wider market pays attention.
- Target potential mispricing by scanning a curated 36 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Secure income-focused opportunities by reviewing a hand picked 5 dividend fortresses that highlights companies combining higher yields with underlying business strength.
- Prioritize resilience by checking a refined 29 resilient stocks with low risk scores that spotlights businesses with sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com