


What Cathay General Bancorp (CATY)'s Stronger Third Quarter Earnings Means For Shareholders
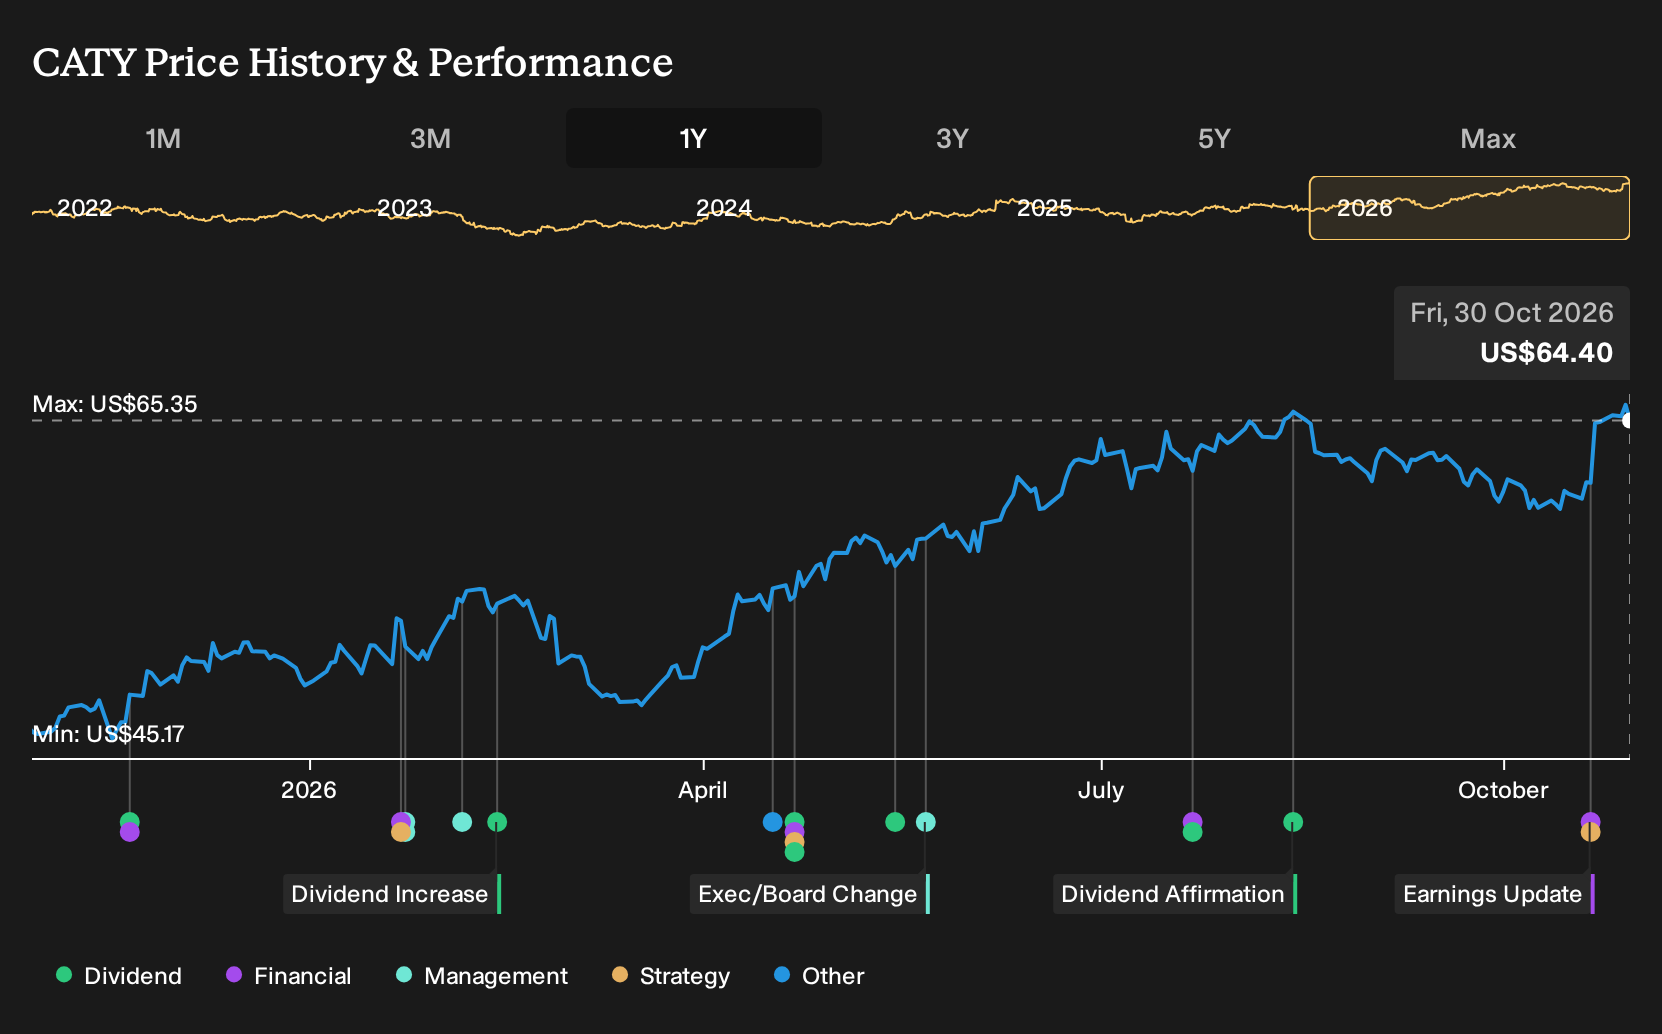
- Cathay General Bancorp reported third quarter 2026 net interest income of US$211.88 million and net income of US$95.17 million, with both quarterly and nine month earnings per share from continuing operations above the prior year period.
- Stronger profitability came alongside higher net charge offs of US$25.29 million for the quarter, which highlights a trade off between earnings strength and rising credit costs that investors need to weigh.
- This article examines how Cathay General Bancorp’s investment narrative is influenced by higher earnings alongside rising net charge offs.
Scan how Cathay General Bancorp’s credit costs compare with peers and spot other banks balancing earnings strength with risk using our hand picked 29 resilient stocks with low risk scores for context.
Cathay General Bancorp Investment Narrative Recap
To own Cathay General Bancorp, you need to be comfortable with a bank that relies more on net interest income and efficiency than on rapid expansion. The latest quarter points to stronger earnings power, which supports that thesis in the near term. The bigger short-term swing factor remains credit quality in commercial real estate rather than pure growth.
Rising net charge-offs of US$25.29 million for the quarter put the focus squarely on how Cathay General Bancorp manages stressed borrowers. If credit costs stay elevated, they can offset some of the benefit from higher net interest income, and that is the key risk investors are likely to watch right now.
The third quarter earnings announcement is the clearest reference point. Net interest income of US$211.88 million and net income of US$95.17 million for the period indicate that the franchise continues to generate solid profitability even as credit costs move higher. That combination matters if you care about dividend sustainability and capital return alongside risk.
Over nine months, Cathay General Bancorp reported US$606.94 million of net interest income and US$274.27 million of net income, with earnings per share from continuing operations above the prior year period on both a basic and diluted basis. Those figures frame the current earnings base that needs to absorb higher net charge-offs and any potential pressure from commercial real estate exposures or funding costs.
Cathay General Bancorp’s current analyst narrative points to revenues of US$1.0b and earnings of US$421.3 million by 2029. This outlook is anchored on 8.8% yearly revenue growth and an earnings increase of about US$74.0 million from US$347.3 million today.
Uncover why Cathay General Bancorp's fair value indicates that earnings expectations are roughly in line with its current price.
Exploring Other Perspectives
One alternate view focuses less on credit losses and more on funding pressure. The most pessimistic analysts were assuming revenue growth of about 6.6% a year and earnings of roughly US$409.3 million by 2029, which is a cooler outlook than the consensus. That camp sees Cathay General Bancorp’s higher deposit costs as a ceiling on upside, and this latest earnings and net charge off news could easily push those expectations in either direction once forecasts are updated.
Explore 2 other Cathay General Bancorp fair value estimates, including one that suggests it could be worth just $65.00.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cathay General Bancorp research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cathay General Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cathay General Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cathay General Bancorp?
Cathay General Bancorp may be on your radar right now, but your watchlist will usually be stronger when you compare it with a few very different opportunities side by side. Use the Simply Wall St Screener to quickly scan other companies that match the mix of quality, income, and risk that fits you best.
- If you want a shortlist of companies that pair financial resilience with low perceived risk, start with this curated 29 resilient stocks with low risk scores and see which businesses clear the bar on both fronts.
- For investors who care most about sturdy finances and clean balance sheets, filter for firms that match that profile using our focused list of solid balance sheet and fundamentals (24 results).
- When you are hunting for overlooked opportunities with stronger fundamentals than their visibility suggests, scan the hand picked 19 high quality undiscovered gems and compare their traits with what you see at Cathay General Bancorp.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com