


H2O America (HTO) Composite Units Deal Puts Its Valuation Back In Focus
H2O America (HTO) has just closed a composite units offering of 6,500,000 units at about US$50 each, raising roughly US$325 million and reshaping the utility's capital structure in a single move.
For context, H2O America shares now trade at US$59.74, with a 1 day share price return of 2.0% and year to date share price return of 21.3%. The 1 year total shareholder return of 33.36% points to momentum that has strengthened over the past year, even though the 5 year total shareholder return is slightly down.
The recent composite units offering, together with October's third quarter earnings update and the latest dividend affirmation, has focused attention on how H2O America is balancing growth plans, funding costs and income for long term holders. This helps explain why recent price moves hint at investors reassessing both future potential and risk.
Spot 29 resilient stocks with low risk scores that, like H2O America after this composite units deal, pairs essential services with balance sheets designed to handle funding shifts without shocking long term holders.The composite units priced at about US$50 and H2O America now changing hands near US$60 puts you at a clear fork: step in after the raise, or wait and hope for a cheaper reset as the valuation section spells out next.
Most Popular Narrative: 10.8% Undervalued
Against the last close at $59.74, the most followed narrative for H2O America points to a fair value of $67.00. The framing now hinges on whether its long term capital plan and Texas expansion actually deliver the earnings path embedded in that gap.
The build out of Quadvest, Cibolo Valley and Hill Country systems in Texas, with active Quadvest connections moving above 59,800 by mid 2026 and a contracted pipeline of roughly 99,000 connections that is expected to help take Texas from 8% to 26% of the customer base by 2029, sets up a multi year increase in customer driven revenue and potential earnings contribution.
See why 7 investors see H2O America as 11% undervalued.
Result: Fair Value of $67.00 (UNDERVALUED)
Still, the H2O America story can unravel if rising California wholesale water charges continue to outpace bill relief or if regulators continue to trim requested revenue increases.
Find out about the key risks to this H2O America narrative.
Another View: What Multiples Say About H2O America
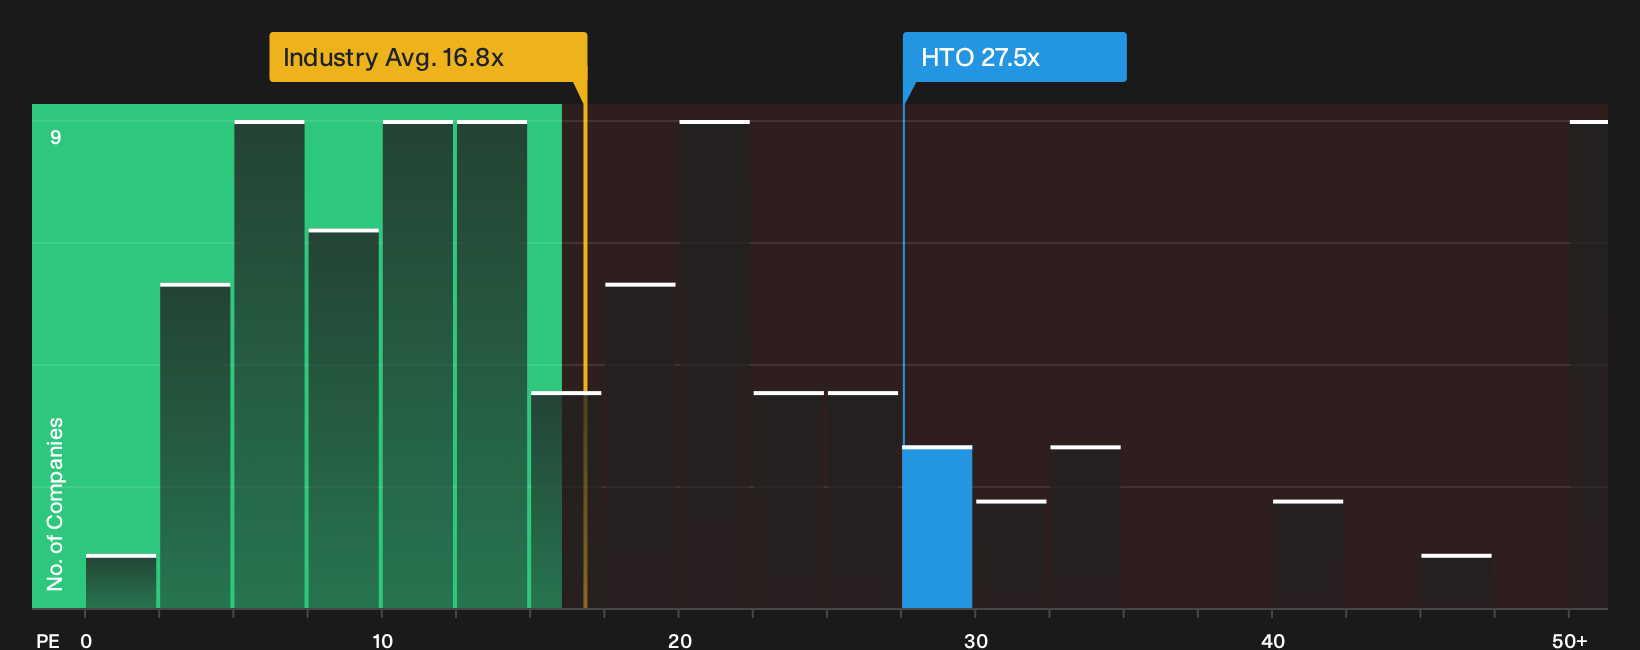
Analyst narratives frame H2O America as about 10.8% undervalued with a fair value of $67. Yet the current P/E of 27.5x sits well above the fair ratio of 21.2x, the global water utilities average of 16.8x and the 22.3x peer group level. That stretch in the multiple points to less margin for error if earnings or regulation disappoint. Which signal do you trust more: the story of future growth, or the price you are paying today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The outlook for H2O America appears mixed so far. For a clearer perspective, consider weighing the potential advantages and disadvantages by starting with 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond H2O America?
If H2O America has sharpened your focus, do not stop here. Broader research gives you more choices, more context and better odds of finding what fits.
- Target steadier growth prospects by reviewing companies flagged in the 19 high quality undiscovered gems that pair resilient operations with room for the story to develop.
- Boost your hunt for present value by scanning the 33 high quality undervalued stocks where pricing and fundamentals line up in a way that rewards disciplined entry points.
- Strengthen the income corner of your portfolio by using the 5 dividend fortresses focused on payouts that aim to compensate you for staying invested.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com