


How Investors May Respond To Encompass Health (EHC) Raised 2026 Revenue Guidance
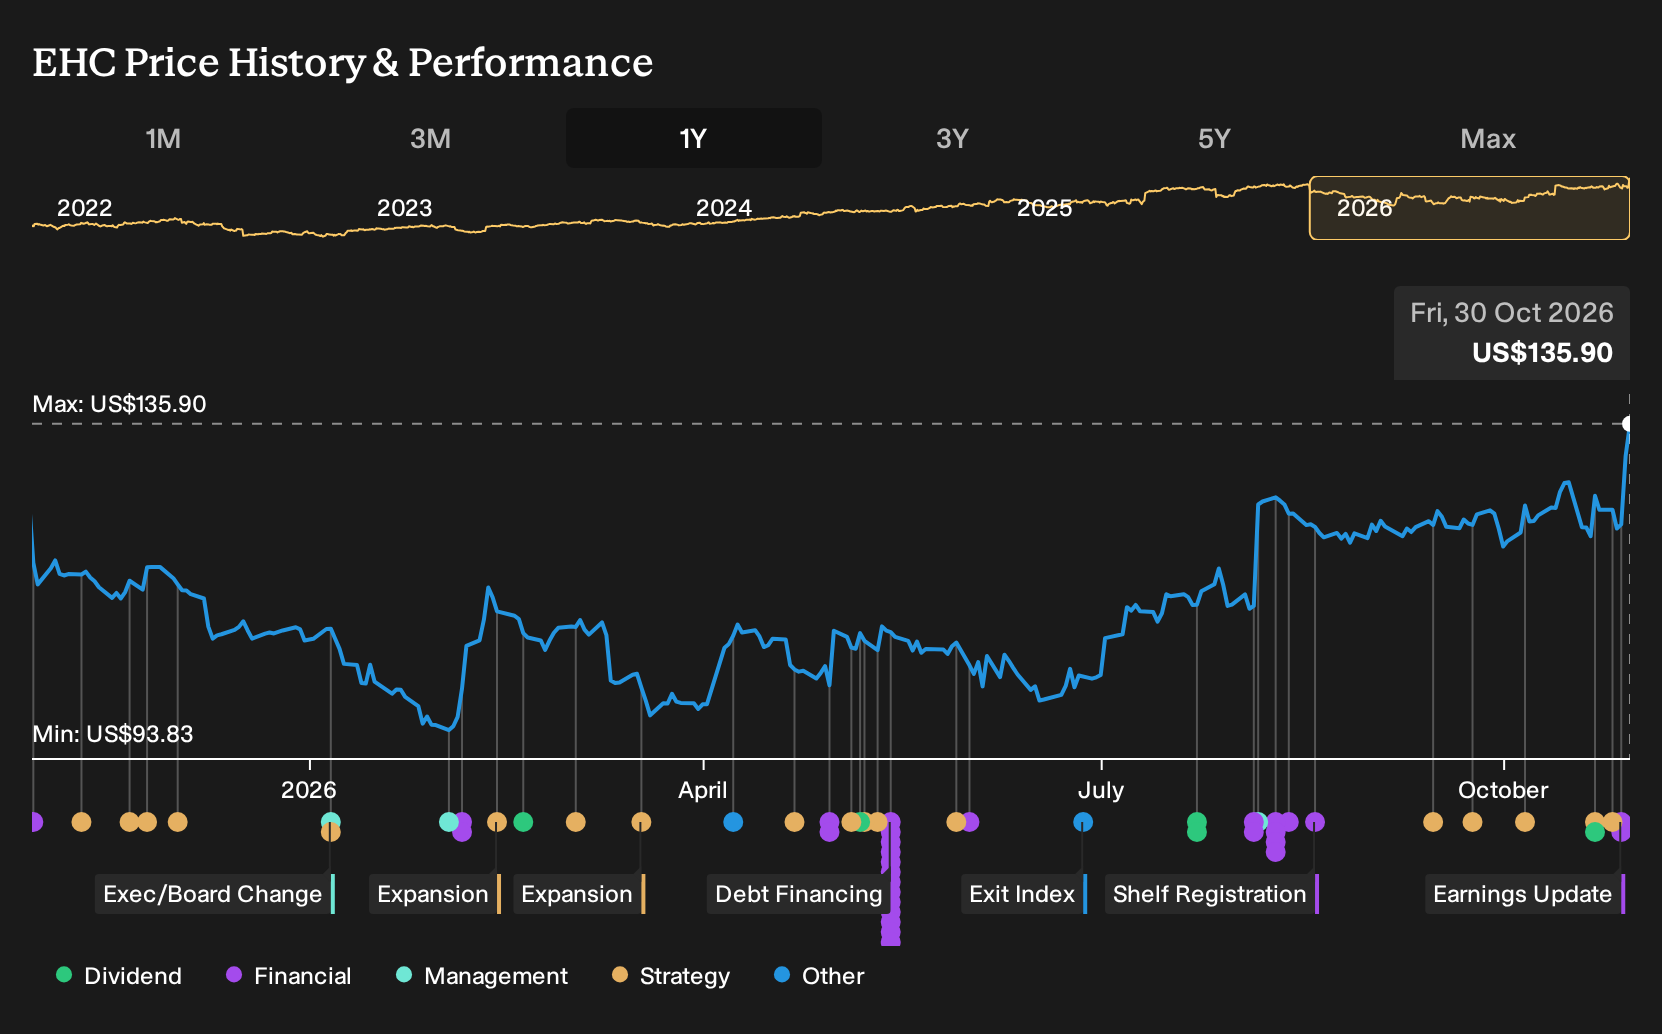
- Encompass Health reported Q3 2026 sales of US$1,609.5 million and net income of US$149.9 million, alongside raised full year 2026 net operating revenue guidance to US$6,450 million to US$6,500 million.
- The company combined stronger earnings, a higher full year revenue outlook, continued hospital expansion in Texas and an affirmed US$0.21 quarterly dividend. Together, these factors highlight an emphasis on both capacity growth and ongoing cash returns to shareholders.
- Now the focus shifts to how Encompass Health's higher 2026 revenue guidance could reshape its investment narrative and risk reward profile.
Compare Encompass Health's latest earnings and expansion story with hand picked hospital and care providers in our list of solid balance sheet and fundamentals (24 results) to see how balance sheet strength and fundamentals line up.
What Is Encompass Health's Investment Narrative?
To own Encompass Health, you need to buy into a fairly clear story. This is an inpatient rehabilitation operator that leans on steady demand for stroke and injury recovery, relatively supportive Medicare reimbursement, and disciplined build out of new beds. The latest quarter fits that script. Q3 2026 brought higher sales and net income year on year, alongside improved basic and diluted EPS from continuing operations. Management then nudged full year 2026 net operating revenue guidance higher and still kept cash flowing out through a US$0.21 quarterly dividend.
In the short term, the operational catalysts are about execution on volume and pricing in existing hospitals and getting Texas capacity such as Westover Hills ramped efficiently, while planning the Richmond small format site for 2028. Those projects keep capital intensity front and center, which matters for a business that already carries a high level of debt and funds itself entirely with higher risk borrowing. Encompass Health’s P/E of 21.4x sits above peer averages but below the broader US Healthcare group, and some intrinsic value models still flag upside, so the news flow has tended to support the current narrative rather than change it.
That said, the cleaner headline story around higher guidance and hospital expansion still runs into one uncomfortable pressure point once you consider ...
There's only one way to know the right time to buy, sell or hold Encompass Health. Head to Simply Wall St's company report for the latest analysis of Encompass Health's Fair Value.
Exploring Other Perspectives
Fair value estimates for Encompass Health from four Simply Wall St Community members range from US$99.17 to US$243.28, so private investors are clearly not aligned. That spread sits next to fresh information on higher 2026 revenue guidance, hospital openings in Texas and an affirmed dividend, which could all reshape how you weigh those competing views.
Explore 3 other Encompass Health fair value estimates, including one that suggests as much as 27% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Encompass Health research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Encompass Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Encompass Health's overall financial health at a glance.
Looking For More Investment Ideas Beyond Encompass Health?
If Encompass Health has put the hospital and care sector on your radar, it can help to compare it with a wider field of potential opportunities using the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, start with companies filtered by valuation and fundamentals through the 33 high quality undervalued stocks.
- If steady income is a priority, focus on stocks with higher yields and robust payout support using the 5 dividend fortresses.
- For those who care most about resilience, narrow your watchlist to businesses with healthier finances and lower risk scores with the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com