


Standex International (SXI) Could Be 28% Undervalued After Record Results And Higher Guidance
Standex International (SXI) just paired record fiscal Q1 2027 results with higher full year sales and earnings guidance, plus a fresh US$100 million buyback authorization and upcoming leadership changes that sharpen investor focus.
The share price reaction has been choppy. Standex International is trading at US$243.55 after sliding 15.6% on a 30 day share price return and 24.5% over 90 days, even though the year to date share price return is up 8.3% and the 5 year total shareholder return is 113.2%. This points to long term momentum but fading short term enthusiasm as investors reassess growth expectations and risk after the new guidance, buyback plan and leadership changes.
Scan beyond Standex International and compare how other quality industrials with steady balance sheets and earnings power are pricing in expectations using our curated 29 resilient stocks with low risk scores today.
The setup is simple. Standex International just reported record earnings, raised guidance and confirmed more buybacks, yet the stock has dropped hard in recent months. Is that a business problem, or a sentiment reset that reshapes value?
Most Popular Narrative: 28% Undervalued
On the prevailing narrative, Standex International’s most followed fair value estimate of $338.40 sits well above the last close of $243.55. This puts the recent share price pullback against a backdrop of longer term grid and aerospace growth plans that many investors are still watching closely.
The main thing that has to go right is successful execution of Standex International’s shift toward higher margin engineered components and grid capacity expansion. This includes delivering on targeted grid sales of roughly US$340 million to US$440 million by fiscal 2030, while sustaining new product launches and margin expansion.
See why 1 investors see Standex International as 28% undervalued.
The most tracked narrative uses an 8.79% discount rate to bring those future cash flows and margin goals back to today and arrives at a fair value of $338.40. This implies a material gap to the current $243.55 share price and frames the recent slide as a question of execution risk rather than a settled verdict on the business.
Result: Fair Value of $338.40 (UNDERVALUED)
Still, that bullish fair value story can unravel quickly if Standex International’s planned grid capacity additions underperform or if organic growth in Electronics and Aerospace & Defense slows sharply.
Find out about the key risks to this Standex International narrative.
Another View: What Standex International’s Price Multiple Signals
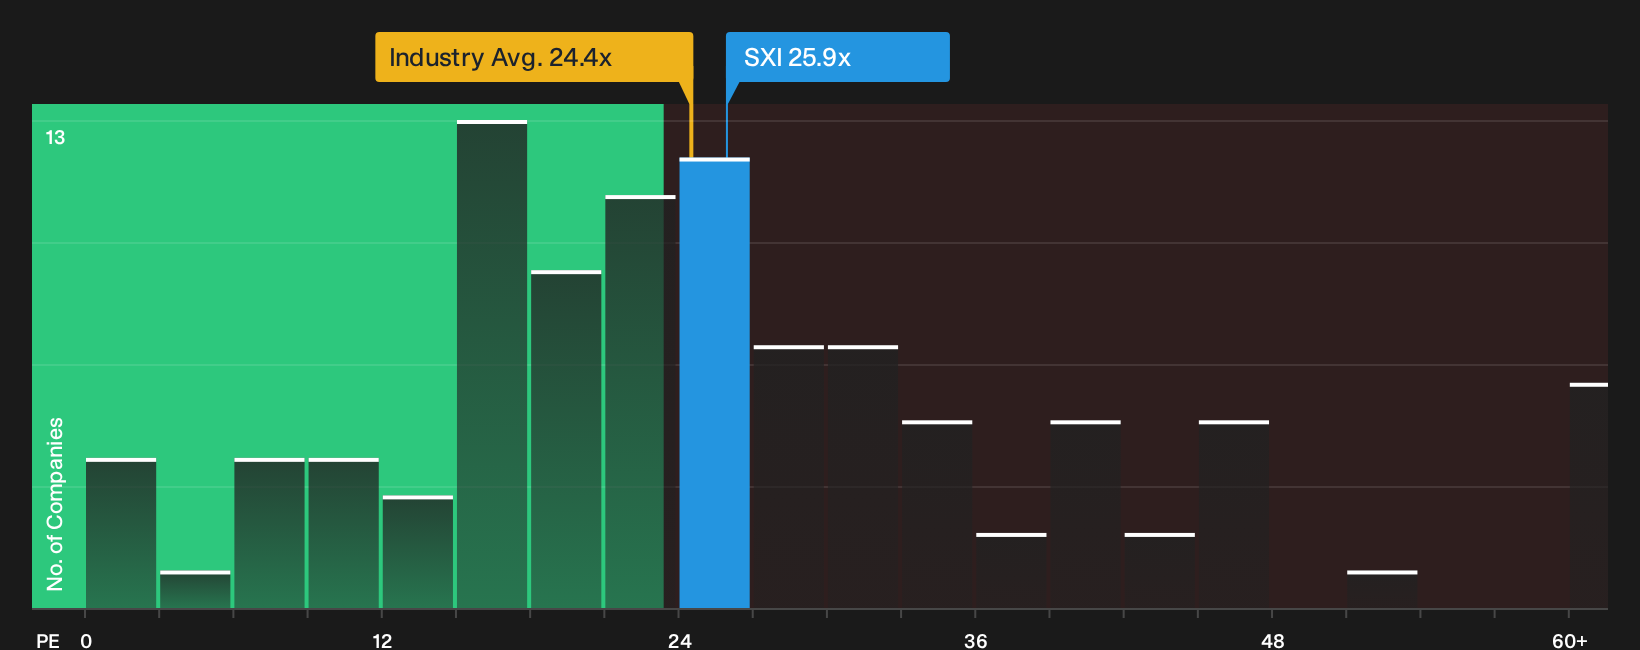
On a simple earnings multiple, Standex International looks less forgiving. The stock trades on a P/E of 25.9x, above the US Machinery industry at 24.4x and well ahead of the peer average at 17.5x, while the fair ratio is 19.6x. That gap suggests less margin for error if the bullish growth path slips.
See what the numbers say about this price: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the short term may signal a reset that opens up a better entry point for Standex International. To weigh those risks against the potential upside yourself, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Standex International?
If you only focus on Standex International, you could miss other opportunities that match your risk, income, and value goals across the wider market.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through the 33 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that feature robust payout profiles and yields in the 5 dividend fortresses.
- Lower portfolio shock by filtering for resilient businesses that score well on financial stability in the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com