


3 U.S. Cyclical Stocks Breaking Away From Mega Cap Tech Selloff
Tech giants and AI chip leaders have just shed roughly US$5t in value while smaller economically sensitive stocks quietly trade through election season, oil spikes and shifting Fed expectations. That mix can create pockets of mispricing that do not stay open for long. This piece walks through three U.S. small and mid cap cyclical stocks that appear especially exposed to this news and explains why each one may deserve a closer look at this time.
The three stocks below are just a starting sample, and the full screen surfaced 46 more U.S. small and mid cap cyclicals with equally compelling stories that are not covered here.
To go beyond this short list, head straight into the U.S. Small- and Mid-Cap Cyclical Stocks (Non-Mega-Cap Tech) screener to identify, filter and analyze the highest conviction ideas that fit your own risk and cycle views.
Tutor Perini (TPC)
Tutor Perini is a mid-cap construction contractor tied directly to U.S. infrastructure and building cycles. This makes it a relatively clean way to get cyclical exposure beyond mega-cap tech in this screener.
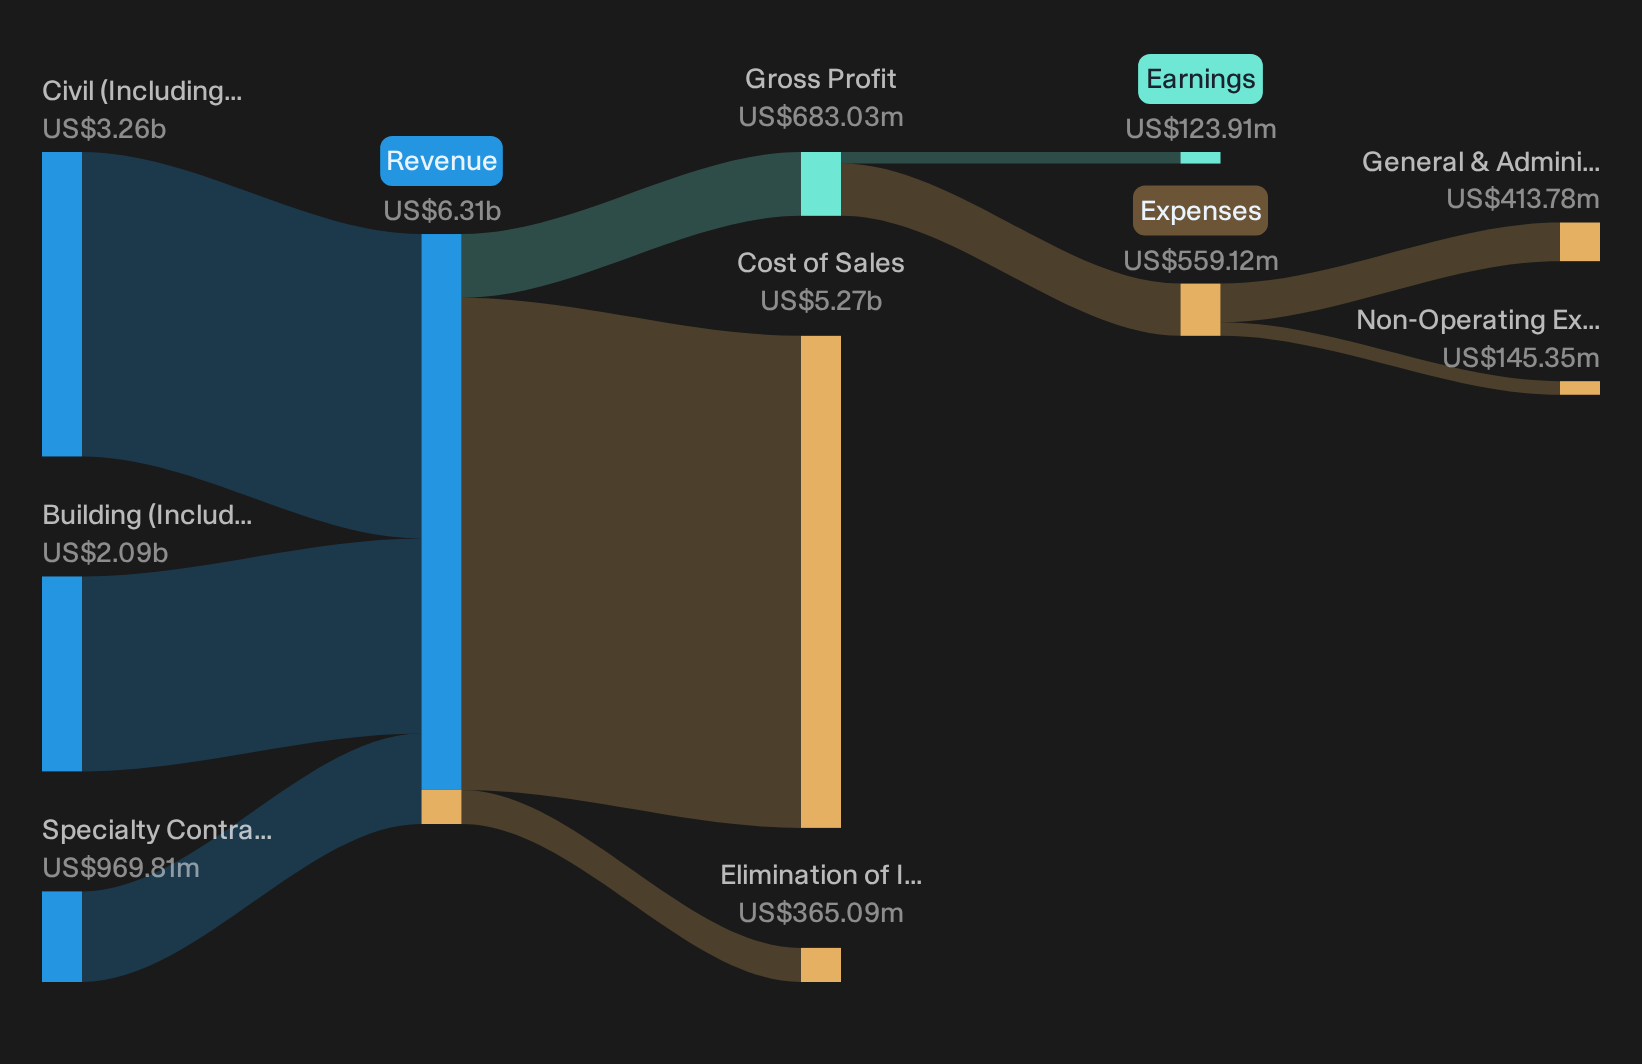
Tutor Perini runs a broad contracting business across civil infrastructure, large buildings and specialty trades. Civil contributed about US$3.3b of revenue, Building about US$2.1b and Specialty Contractors about US$1.0b after intersegment eliminations. The stock carries a market value of roughly US$4.2b.
For investors watching how capital rotates from mega-cap tech into economically sensitive projects, Tutor Perini offers a direct test case of what that shift can mean for a construction-focused mid-cap.
Although Tutor Perini highlights nine large projects totaling about US$16b with better contractual terms and higher expected margins, the July 2026 US$42.4m judgment tied to the W and Element hotels shows that legacy disputes can still absorb cash from this mega project shift and could weigh on net margins and earnings quality as these projects ramp.
What happens to those future margins depends heavily on how one lingering pressure on cash flow plays out over the next few years.
As that cash squeeze plays out, the real story sits inside the full narrative for Tutor Perini, where contract mix, dispute timing and project execution could be quietly decoupling.
Titan International (TWI)
Titan International gives you pure cyclical exposure to off highway equipment, tying your portfolio to real world spending on farms, construction sites and mines rather than mega cap tech headlines.
Anticipated resolution and consistent application of global trade policies and tariffs are expected to create a more level playing field, reducing competitive pressures from low cost imports and supporting higher pricing power and improved net margins for Titan International.
What happens to earnings power from here depends heavily on how one quiet shift in Titan International's end market mix plays out over the next few years.
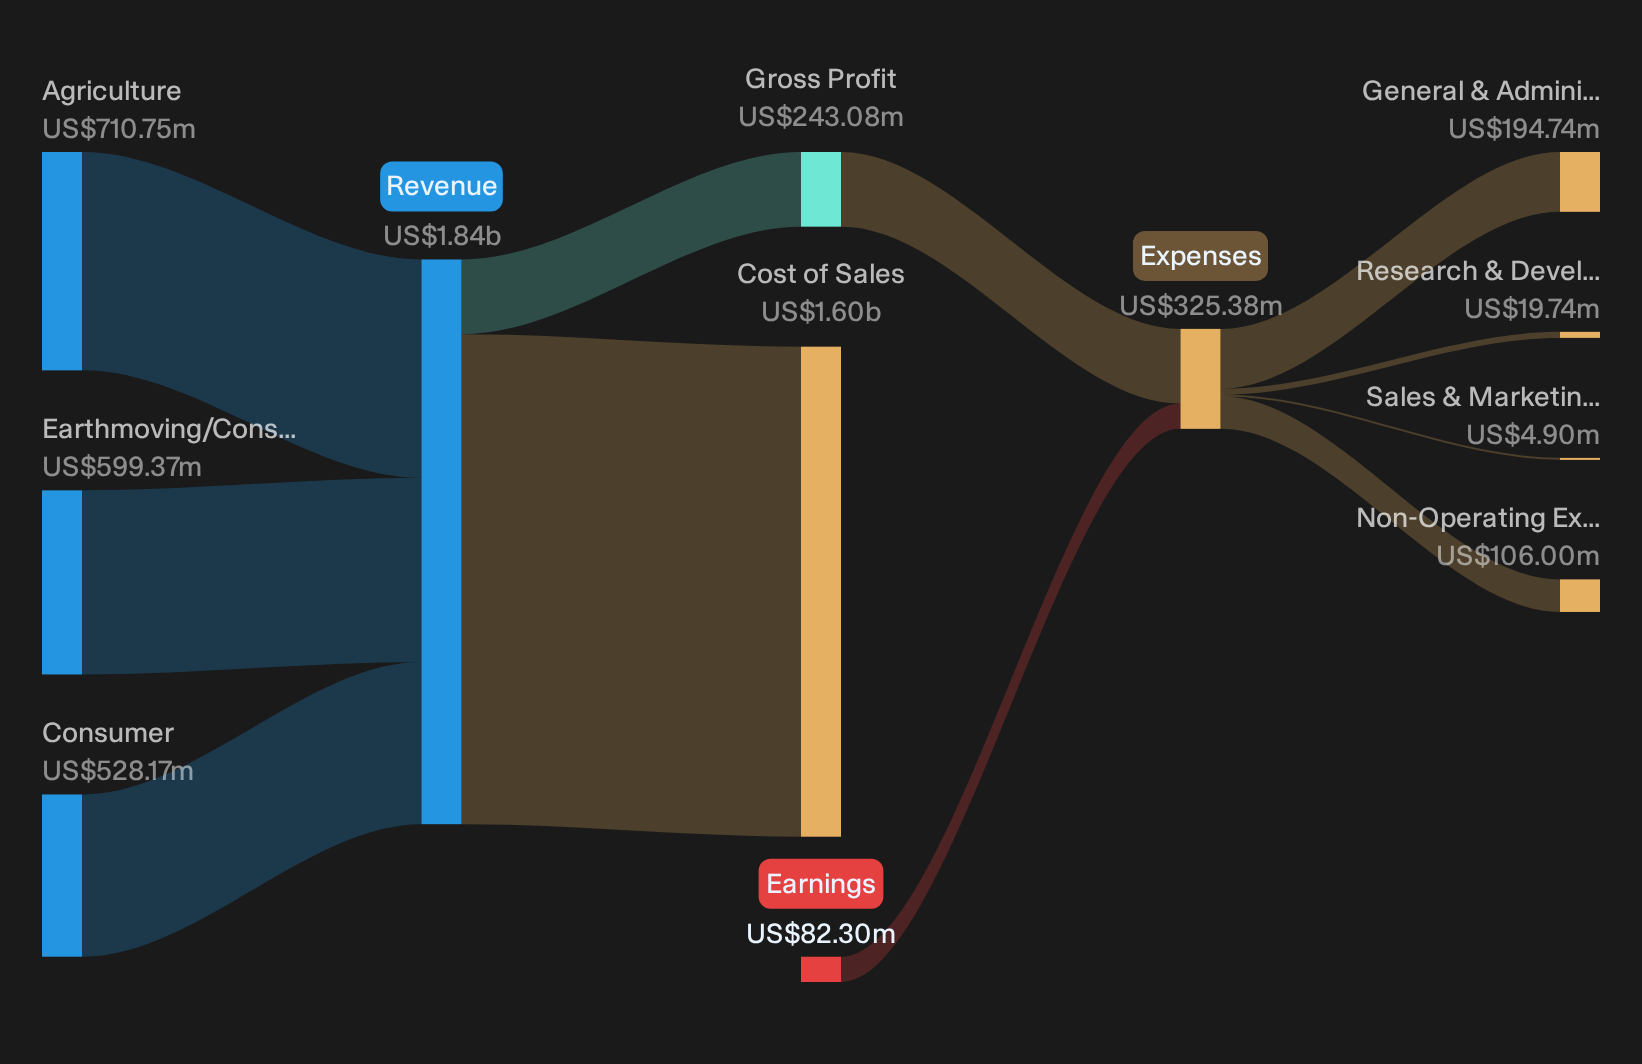
Titan International manufactures off highway wheels, tires and undercarriage components across agriculture, construction, mining and consumer equipment. This plugs directly into this screener's economically sensitive industrial theme. Revenue is spread across Agriculture at about US$711 million, Earthmoving and Construction at roughly US$599 million, and Consumer at around US$528 million, supported by both OEM and aftermarket channels. The stock carries a market value near US$300 million, which keeps it firmly in the small cap camp.
As that mix shift unfolds, head into the full narrative for Titan International to see how trade policy, pricing power and end market exposure could be quietly accelerating Titan International's next chapter.
ArcBest (ARCB)
ArcBest ties this screener theme together by giving you mid-cap, higher beta exposure to freight volumes as goods movement steps back into focus outside mega-cap tech.
ArcBest is an integrated logistics group that runs less than truckload hauling and asset light brokerage, warehousing and managed transportation services, generating about US$2.8b from Asset Based operations and roughly US$1.5b from Asset Light activities, with a market value near US$2.8b.
ArcBest’s restructuring program, which includes brand consolidation, terminal closures, workforce reductions and an expected US$40 million in annual run rate savings by early 2027, creates room for a step up in operating leverage that could support higher net margins and earnings power than current models assume once freight volumes normalize.
What investors really need to watch is how one quiet shift in the mix of higher margin services ultimately shapes those future freight economics.
If that mix shift in higher margin freight services is what you are watching, read the full narrative for ArcBest to see how restructuring could be masking ArcBest’s next leg of earnings power.

Seeking Fresh Alternatives Beyond Tech?
Fresh breakouts rarely stay hidden. Momentum shifts fast, and by the time headlines catch up, the easy entry points can be gone. Review these ideas before the broader market and consider them while they are still less widely followed.
- Consider durable income streams while prices still look reasonable by checking a curated set of income ideas inside the 5 dividend fortresses.
- Look for early movers in automation and industrial efficiency by reviewing hand picked opportunities in the 94 robotics and automation stocks.
- Explore infrastructure and electrification opportunities by scanning the curated 42 power grid technology and infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com