


Happen (HAPN) Stock May Be Undervalued Following Raised EPS Guidance
Happen has been a volatile ride for shareholders, with a sharp multi year rebound alongside more recent weakness. This naturally raises the question of whether the current US$15.53 share price is still in line with what its earnings can justify.
- Over the past 3 years the stock has gained 161.0%, which puts pressure on the earnings story to support that kind of long term rerating.
- Recent profit strength and higher earnings expectations put the focus on whether that improved profitability can be sustained without requiring heavier investment or reducing future returns.
- Your read on Happen is one view; the desks covering it have another. See what analysts think Happen's shares could be worth.
The issue now is whether Happen's current valuation is adequately backed by its earnings power today and over the coming years.
If you want to test the same earnings based valuation question across a wider field, compare Happen with the 33 high quality undervalued stocks.
Is Happen Still Cheap on Earnings?
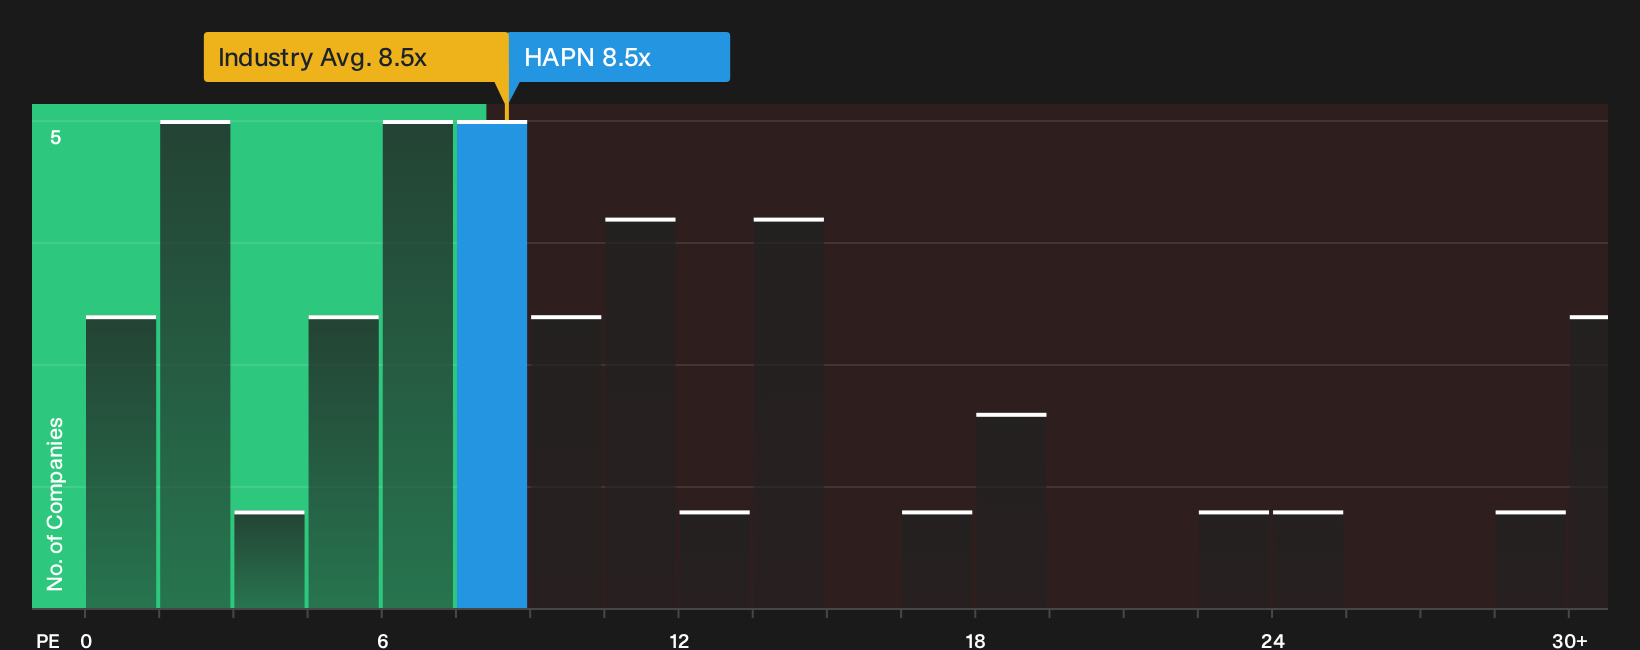
The P/E ratio fits Happen because earnings are now a key focus for how investors judge the digital banking model. On this metric, the stock trades on roughly 8.5x earnings, which is very close to the Consumer Finance sector average of about 8.5x and only slightly below peers at around 9.5x. That cluster of figures points to a valuation that tracks broad sector sentiment more than a company specific story.
Because the fair P/E level implied by Happen’s own profitability profile and risk inputs sits above the current 8.5x, the shares screen as undervalued on this framework rather than stretched. The raised full year EPS guidance from 2026 adds context, because it means the market is assigning a sector like multiple despite stronger profit commentary. For anyone weighing whether that gap is justified, the key question is how durable those earnings prove to be relative to what the model assumes over time. Explore the numbers behind Happen's P/E valuation.
The Happen Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Happen pick up where the P/E debate leaves off by spelling out which combinations of future growth, margins and earnings would need to play out for the stock to look meaningfully mispriced in either direction at today's level. Each idea links its number to a specific view on how Happen's growth, profitability and risk profile might evolve, giving you something concrete to track as fresh information comes through.
One of the top community narratives on Happen: 37% undervalued
"The main thing that has to go right is that Happen maintains its credit and underwriting edge while scaling marketplace funding..."
Discover why this Narrative puts Happen at 37% undervalued.
One last Happen check that sits beside the earnings multiple
Price and current earnings only tell part of the story, because professional coverage also sketches out where this business might be a few years from now and that extra lens can sharpen how you read today’s valuation. Explore where analysts expect Happen to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com