


How Investors May Respond To Huntington Ingalls Industries Stock Record Q3 Results
- Huntington Ingalls Industries reported third quarter 2026 revenue of US$3,537 million and net income of US$217 million, with contract awards of over US$32 billion expanding its backlog to US$86.2 billion and supported by new Navy work in submarines, carriers and unmanned surface vessels.
- The business is tying record quarterly results directly to operational execution on long duration Navy programs and growing autonomous maritime systems, indicating that contract visibility and program performance are central to how Huntington Ingalls Industries generates and stabilises its earnings profile.
- We will now look at how Huntington Ingalls Industries' investment narrative could be shaped by record third quarter results and an expanding Navy backlog.
Scan beyond Huntington Ingalls Industries and compare its defense and shipbuilding exposure with other contractors riding similar contract momentum using our hand picked 29 resilient stocks with low risk scores
Huntington Ingalls Industries Investment Narrative Recap
To own Huntington Ingalls Industries, you need to believe its long duration Navy programs and growing unmanned systems work can translate into steadier margins and reliable cash conversion. Record Q3 revenue of US$3,537 million and net income of US$217 million point to solid execution, but management still has to deliver on a back end weighted free cash flow profile.
The most important near term catalyst is throughput and margin delivery on the large submarine, carrier and ROMULUS contracts sitting inside a US$86.2b backlog. The biggest risk remains execution volatility on complex carrier programs and any shortfall against the US$500 million to US$600 million free cash flow ambition for 2026.
The dividend increase to US$1.41 per share per quarter, up from US$1.38, is the announcement that most directly tests this earnings quality story. The board appears comfortable nudging shareholder payouts higher while Huntington Ingalls Industries is still investing heavily in automation, workforce expansion and its Mission Technologies segment.
For investors, that dividend change sits alongside record Q3 earnings per share of US$5.48 on a diluted basis and a large pipeline of funded Navy work. The key question is whether carrier execution issues, high debt levels and the timing of contract advances will allow the business to support both a growing payout and the throughput and margin gains that analysts are watching.
Huntington Ingalls Industries is currently modeled on consensus assumptions that revenue will grow by 5.2% per year, reaching US$15.3b of revenue and US$965.0 million of earnings by 2029, compared with earnings today of US$661.0 million. This implies an earnings increase of about US$304 million over that period.
Uncover why Huntington Ingalls Industries' fair value indicates a 12% potential upside to its current price that could narrow quickly.
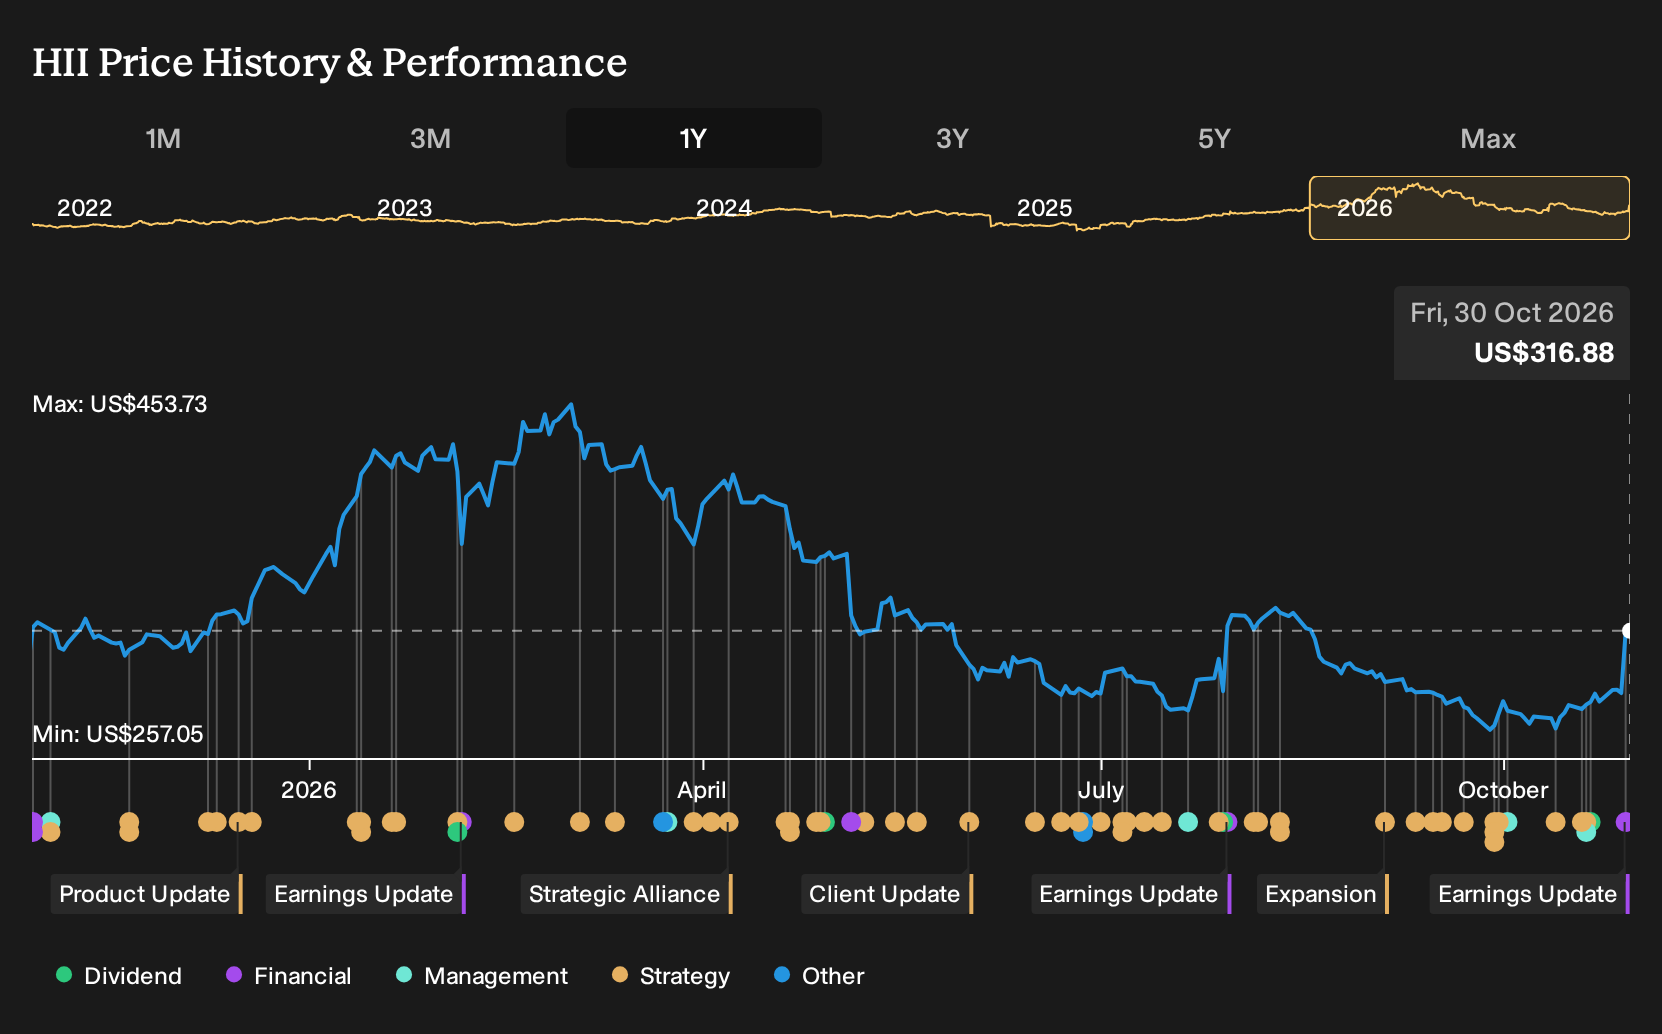
Exploring Other Perspectives
Not every analyst sees the Huntington Ingalls Industries story through the same lens. Some of the most cautious voices focus on management execution and culture risk, especially around leadership changes such as the new HR chief and a recent board appointment. Those bearish forecasts pencilled in about US$15.3b of 2029 revenue and roughly US$896.1 million of earnings before this quarter's news, so expectations and narratives may shift as you review different viewpoints.
Explore 4 other Huntington Ingalls Industries fair value estimates, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Huntington Ingalls Industries research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Huntington Ingalls Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huntington Ingalls Industries' overall financial health at a glance.
Looking for more investment ideas beyond Huntington Ingalls Industries?
If the Huntington Ingalls Industries story has sharpened your sense of what you want in a portfolio holding, you can use that clarity to scan a wider field of potential opportunities with the Simply Wall St Screener. Filter for the traits that matter most to you and let the data surface candidates that match your own criteria rather than someone else's hot list.
- If capital preservation and steadier profiles are high on your list, you can start with a curated 29 resilient stocks with low risk scores that focuses on companies scoring well on Simply Wall St's internal risk metrics.
- Income focused investors who care about compounding dividends over time can review a targeted 5 dividend fortresses that concentrates on higher yield payers with supporting fundamentals.
- For those hunting for mispriced quality, a hand picked 33 high quality undervalued stocks can highlight businesses where fundamentals and valuation checklists currently line up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com