


Is ePlus (PLUS) Stock Near Fair Value On Earnings?
ePlus has rewarded patient shareholders over the past few years, which puts extra focus on whether the current share price lines up with the earnings that support it. With the stock not far removed from a strong multi year run, the key issue now is how much of the business outlook is already reflected in that valuation.
- Over the past 5 years the stock has gained 54.2%, which raises the question of how closely that performance tracks the company’s underlying earnings power.
- The business leans heavily on converting technology solutions into consistent profit, so the resilience of its margins and cash generation can shape how much investors are willing to pay for each dollar of earnings.
- There is a second opinion on ePlus worth weighing. See what analysts think ePlus's shares could be worth.
For investors, the debate is whether ePlus's recent share price level is fully supported by its current and expected earnings or whether expectations have moved ahead of what the business is likely to deliver.
If you want extra context on whether ePlus's earnings based valuation feels rich or reasonable, it can help to compare it with 33 high quality undervalued stocks.
Where Does ePlus Sit on Earnings?
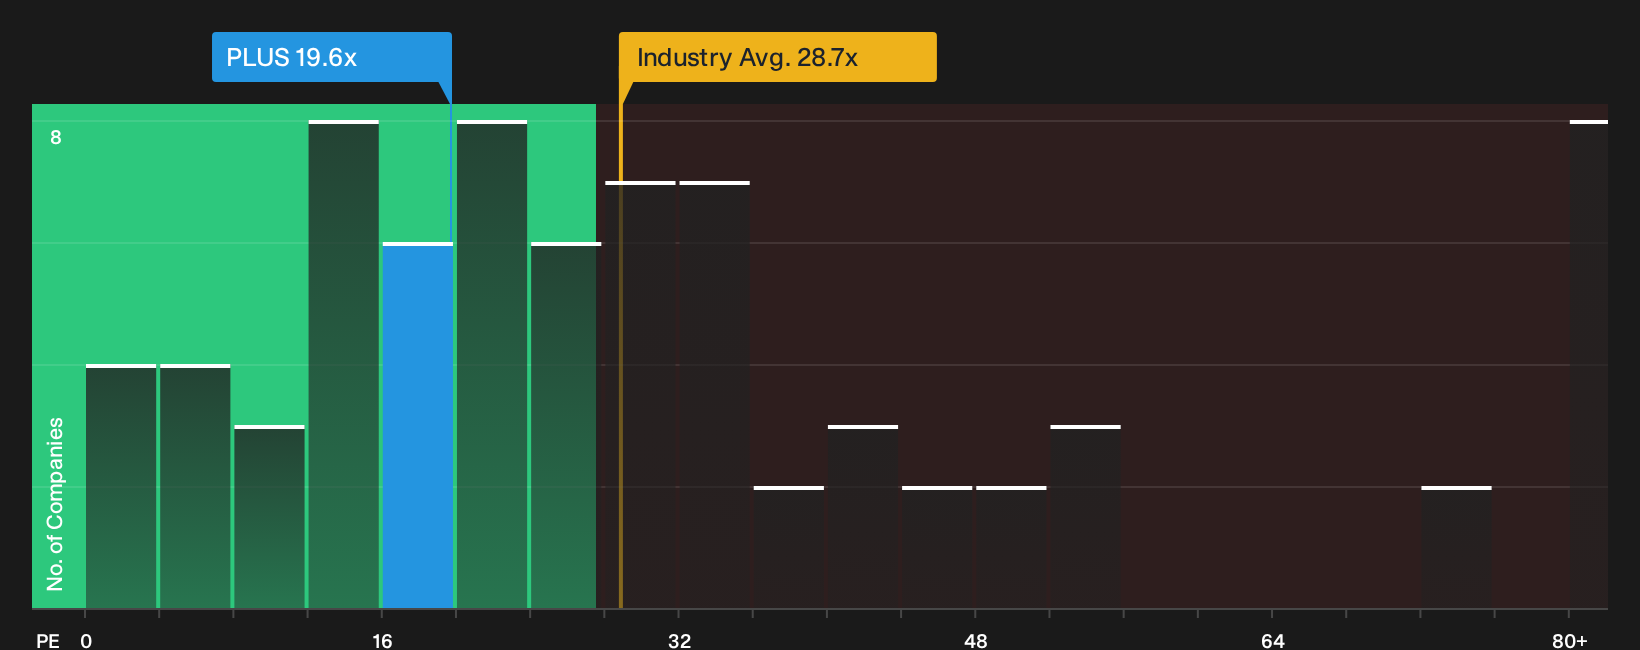
The P/E ratio works well for ePlus because investors focus closely on how efficiently it converts its technology solutions into earnings. On this measure, the stock trades on roughly 19.6x earnings, which is below both the broader Electronic industry average of about 28.7x and the peer group near 22.9x. That gap suggests the market is not assigning ePlus the same valuation as many similar businesses, even though they share the same broad sector label.
The Fair Ratio points to the kind of P/E you might expect for ePlus once its own profitability profile, risk and size are factored in, and the current 19.6x level sits close to that mark. For a reader, that means the multiple does not clearly signal a stretched or depressed price on this framework, so the more interesting questions become how durable you consider its earnings mix and how comfortable you are with the cash flows behind them. Explore the numbers behind ePlus's P/E valuation.
The ePlus Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the ePlus valuation puzzle leaves off, by spelling out which assumptions on growth, profitability and earnings strength would need to hold for the current share price to look materially higher or lower over time, and they sit on the stock's Community page rather than in a model output. Each narrative treats fair value as a thesis about ePlus' business that can be tracked as new information comes through, instead of a one off snapshot.
One of the top community narratives on ePlus: 16% undervalued
"The main factor that has to go right is that ePlus converts its growing managed services and security billings into a larger, higher margin recurring mix..."
Discover why this Narrative puts ePlus at 16% undervalued.
One more ePlus checkpoint before you move on
Price tells you what investors pay for ePlus today, yet analyst outlooks sketch where those same professionals currently expect the business to be a few years from now. This gives you a different lens to compare with today's multiple. Explore where analysts expect ePlus to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com