


Sabra Health Care REIT (SBRA) Stock Still Looks Pricey Against Its Earnings
Sabra Health Care REIT has delivered a strong share price run in recent years, and that kind of climb naturally invites closer scrutiny of what investors are paying for its earnings today. With the units recently closing at US$19.74, the key issue for holders and potential buyers alike is how that price lines up with the real estate investment trust's underlying profit power.
- Over the past 5 years the stock has returned 96.3%, which puts real money behind the question of whether the current valuation can still be grounded in its earnings profile.
- The business model depends on turning rental income from healthcare properties into steady distributable profit, so any change in operating efficiency or funding costs may affect how comfortably earnings cover the current price tag.
- There is a second opinion on Sabra Health Care REIT worth weighing. See what analysts think Sabra Health Care REIT's shares could be worth.
The issue now is whether the earnings that Sabra Health Care REIT generates are enough to justify where the stock trades today.
If you want a broader watchlist of income focused real estate ideas alongside Sabra Health Care REIT, a focused stock screen is a useful next step, starting with 5 dividend fortresses.
Does Sabra Health Care REIT Look Pricey on Earnings?
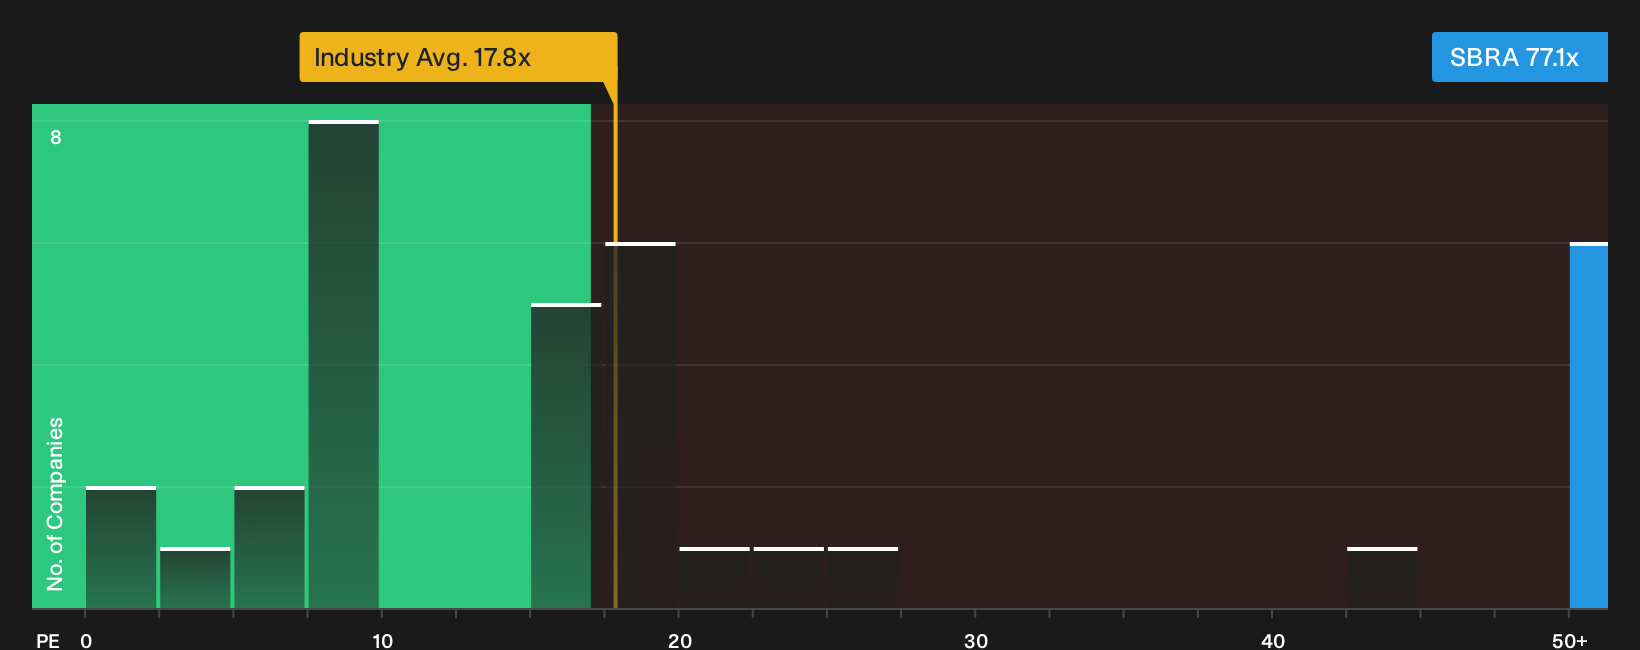
The P/E ratio is a useful lens for Sabra Health Care REIT because investors often anchor on earnings when weighing income focused property trusts. On this measure, the stock trades on a P/E of 77.1x, which is well above both the Health Care REITs industry average of 17.8x and the peer group average of 48.5x. That kind of gap means each dollar of Sabra Health Care REIT earnings is being priced far more richly than many sector alternatives.
The fair value framework, which adjusts for factors such as growth expectations, profitability and risk, points to a lower P/E as more typical for this business profile. As a result, the current 77.1x reading screens as overvalued on this model. For a holder or prospective buyer, the key question is whether Sabra Health Care REIT can deliver an earnings path that makes this premium feel more like a reasonable entry toll rather than a stretched starting point over time. Explore the numbers behind Sabra Health Care REIT's P/E valuation.
The Sabra Health Care REIT Narrative: What Would Justify Today's Price?
Sabra Health Care REIT’s current P/E gap raises a clear question for anyone holding or watching the units. Narratives on Simply Wall St’s Community page connect that valuation puzzle to concrete assumptions on future growth, margins and earnings, and each one treats the implied fair value as a thesis about Sabra Health Care REIT's business that you can track over time instead of a one off snapshot.
One of the top community narratives on Sabra Health Care REIT: 13% undervalued
"The main factor that has to go as planned is that Sabra successfully executes on SHOP expansion and portfolio recycling so that occupancy, RevPOR, margins, and rent resets translate into internal cash flow growth…"
Discover why this Narrative puts Sabra Health Care REIT at 13% undervalued.
Sabra Health Care REIT’s valuation still hinges on who is in charge
Price tags tell only part of the story for Sabra Health Care REIT, because the people setting priorities and the way their pay packets are structured can quietly tilt outcomes for years. See who runs Sabra Health Care REIT and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com