


Scatec (OB:SCATC) Cuts Guidance As Q3 Losses Deepen While Undervalued View Holds
Scatec (OB:SCATC) just posted third quarter 2026 results that combined higher sales with a much wider loss, after weaker power production, tariff delays, and grid connection lags prompted management to cut full year EBITDA guidance.
Scatec’s share price tells a mixed story, with a 7 day share price return of 5.02% after the Q3 release, yet down 17.90% over 30 days and 21.55% year to date. The 3 year total shareholder return of 27.87% contrasts with a 46.52% decline over five years, which points to weaker long term momentum.
Compare Scatec's setback with other renewable players and review a hand picked group of utilities facing fewer earnings shocks through the list of solid balance sheet and fundamentals (199 results)
Scatec is growing its renewable footprint while reporting deep losses and a cut to Power Production EBITDA guidance. After the recent share price rebound, is that mix of scale and volatility actually priced fairly today?
Most Popular Narrative: 35% Undervalued
On the most followed view, Scatec’s fair value sits at NOK130.38, comfortably above the NOK84.65 last close. This puts execution of its project pipeline in the spotlight for anyone weighing that gap.
Scatec’s 12.3 GW generation and 6.8 GWh storage near term portfolio, which management aims to realize over the next 2 to 3 years, gives the company multiple levers to convert contracted and merchant projects into additional revenue and EBITDA as these assets move from backlog and construction into operation.
See why 14 investors see Scatec as 35% undervalued.
Result: Fair Value of NOK130.38 (UNDERVALUED)
Still, Scatec’s story can change quickly if currency swings, geopolitical shocks or weaker power production further pressure EBITDA and delay any improvement in net losses.
Find out about the key risks to this Scatec narrative.
Another View: DCF Points The Other Way
There is a very different message coming from the SWS DCF model. On this approach, Scatec’s estimated future cash flow value is NOK19.49 per share, far below the NOK84.65 market price today. This frames the stock as overvalued rather than undervalued. Which set of assumptions do you trust more?
For a closer look at how that cash flow outlook is built up, and how sensitive it is to the inputs you agree or disagree with, Look into how the SWS DCF model arrives at its fair value.
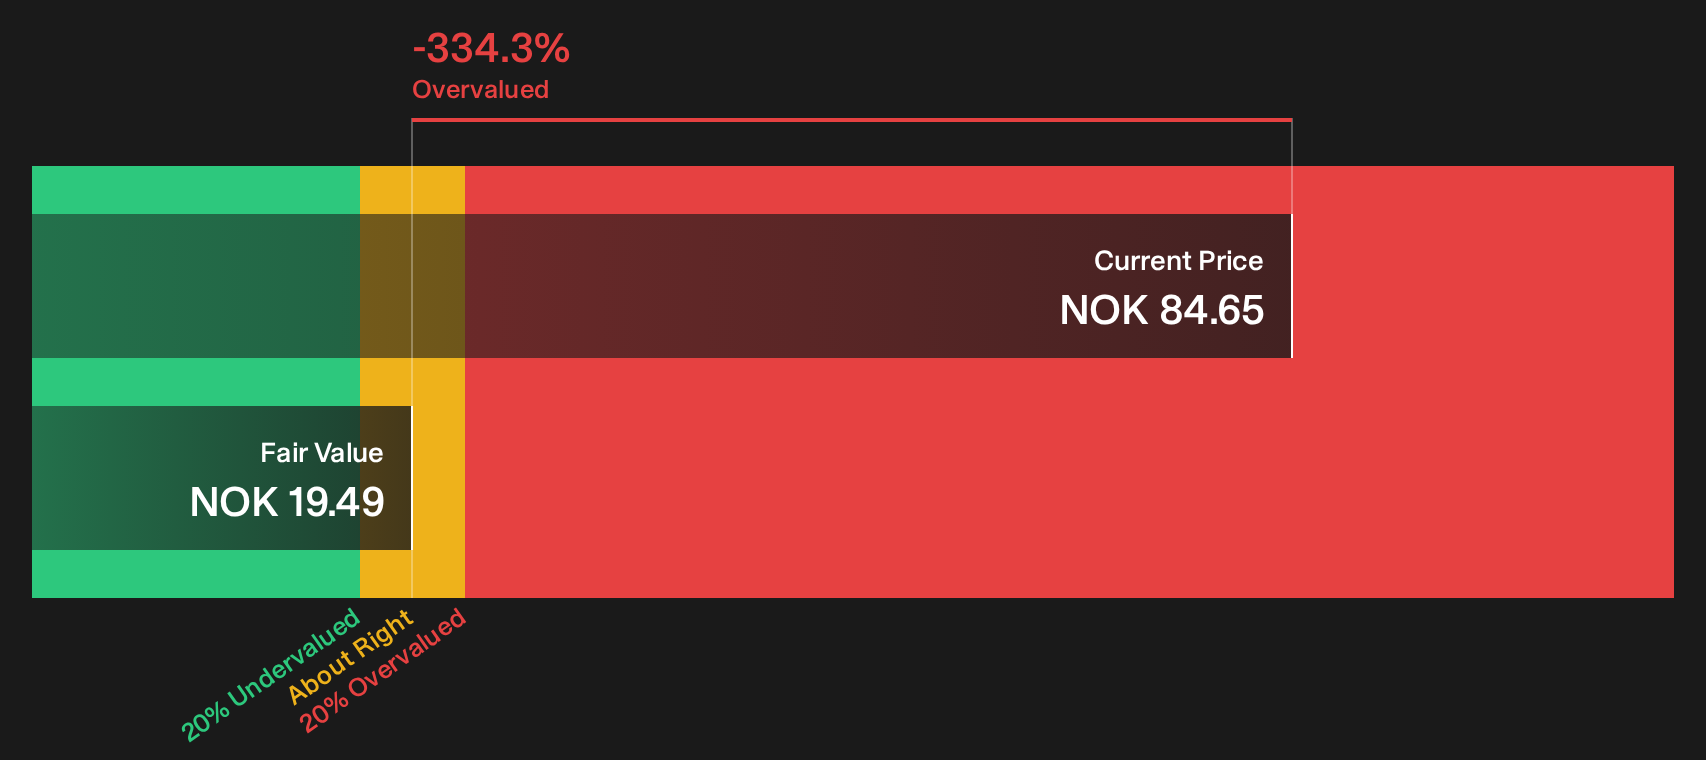
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scatec for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like these rarely feel comfortable, yet they are exactly when your own homework matters most. Move quickly and weigh both sides with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Scatec?
If Scatec has you thinking harder about risk, reward, and valuation, do not stop there. Cast the net wider and pressure test your next moves with fresh ideas.
- Target quality at a discount by scanning companies that combine strong fundamentals with appealing pricing through the 196 high quality undervalued stocks.
- Prioritise resilience by reviewing a 217 resilient stocks with low risk scores that can help steady your portfolio when individual positions feel volatile.
- Get ahead of the crowd by checking a 609 high quality undiscovered gems before those opportunities are widely on the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com