


LyondellBasell Stock Eyes Earnings Rebound After Houston Refinery Site Sale
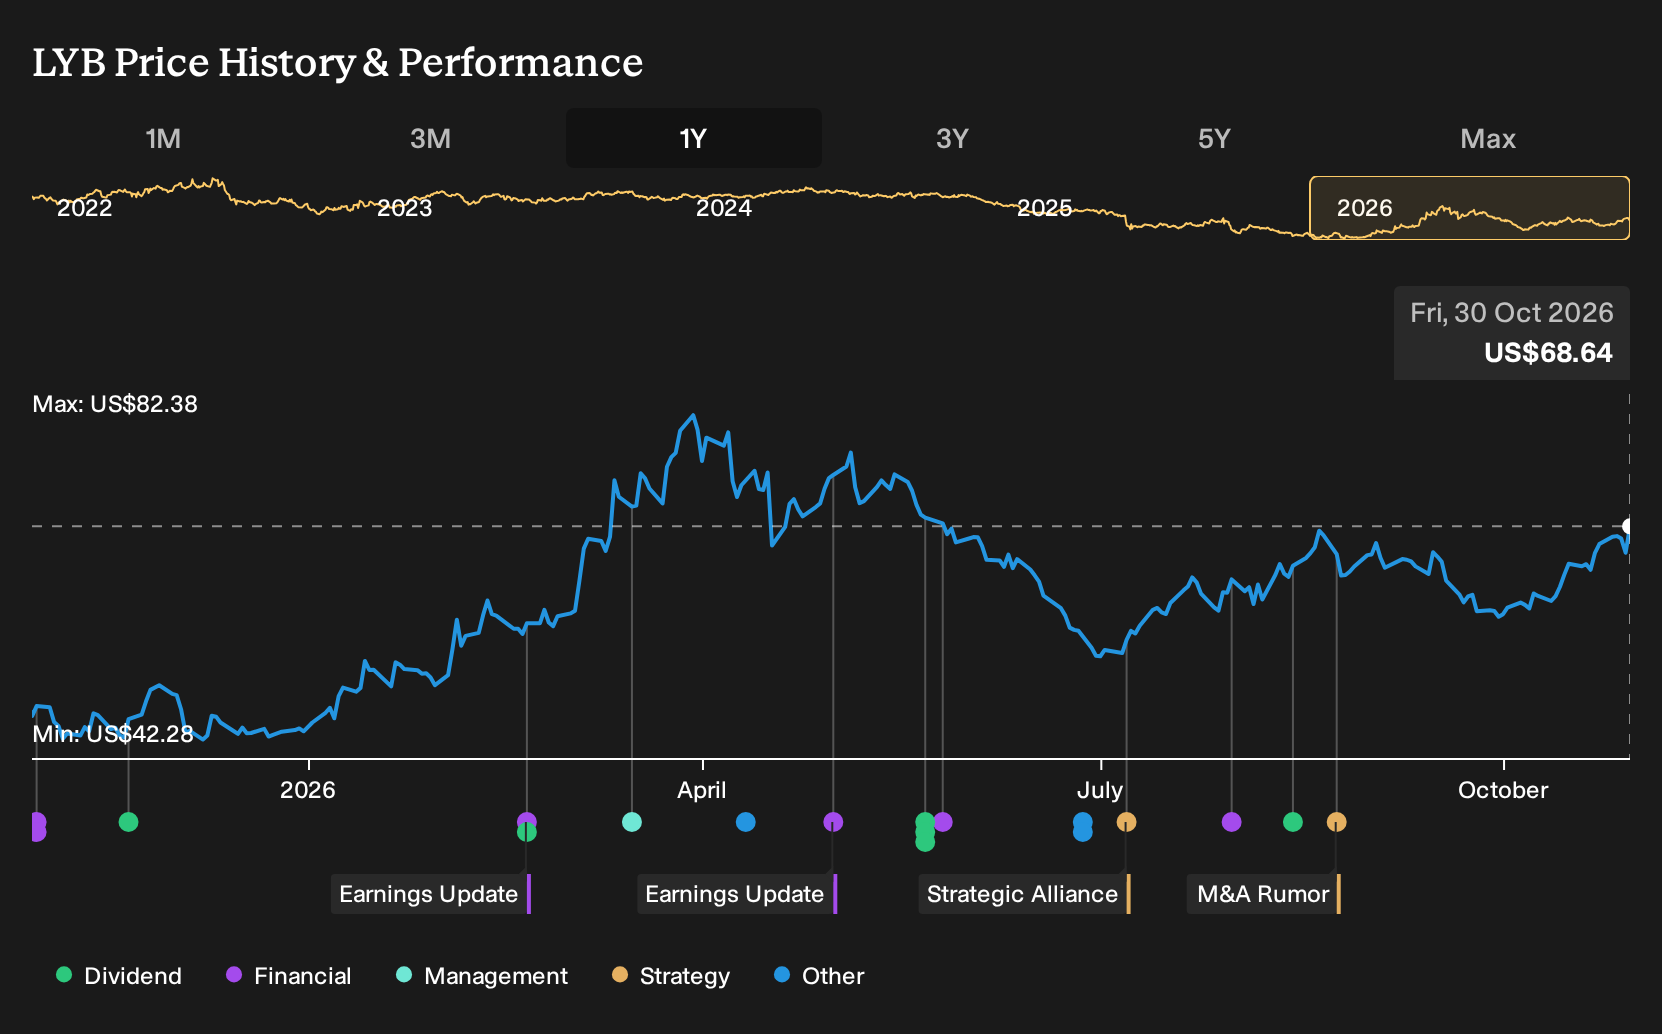
- LyondellBasell Industries reported third quarter 2026 revenue of US$8,499 million and net income of US$756 million, a return to profit compared with a net loss in the same period a year earlier.
- The sale of the former Houston refinery site for US$320.5 million removes a non core, higher risk asset and channels more of LyondellBasell Industries’ cash generation toward its core petrochemicals portfolio and cost reduction plans.
- We will now look at how LyondellBasell Industries’ return to profitability could influence the longer term investment narrative around the business.
LyondellBasell Industries Investment Narrative Recap
LyondellBasell Industries now asks shareholders to believe that a leaner petrochemicals portfolio and cost cuts can translate into steadier cash generation through cycles. The return to profit in Q3 2026 and positive earnings over the first nine months support that story at the operating level. The near term swing factor remains execution on cost savings and asset rationalisation, not just headline earnings prints.
The biggest current risk sits in two places. A loosening petrochemical market could pressure pricing power. Operational reliability issues, as seen earlier in 2026, could also resurface and absorb much of the earnings benefit from recent restructuring and cash improvement work.
The most relevant update for this story is LyondellBasell Industries’ Q3 2026 report, with US$8,499 million of revenue and net income of US$756 million. Over the first nine months, management reported US$24,873 million of revenue and US$1,437 million of net profit. That shift back into the black is what gives the current cash focused plan more credibility.
This profitability recovery intersects directly with the key catalysts investors watch. Cost reduction, portfolio reshaping and circular projects already in motion rely on internal cash generation rather than heavier borrowing. At the same time, any slip in operational reliability or weaker petrochemical conditions could again compress margins and make those self funded plans harder to deliver.
LyondellBasell Industries’ narrative projects US$34.1b revenue and US$2.4b earnings by 2029. This assumes 3.0% yearly revenue growth and an earnings increase of about US$2.7b from current earnings of a US$265.0m loss.
Uncover why LyondellBasell Industries' fair value indicates a valuation that is in line with its current price.
Exploring Other Perspectives
One alternate view leans heavily on MoReTec 1 as a catalyst. Bullish analysts were already penciling in revenue of about US$37.5b and earnings of roughly US$3.3b by 2029. Those forecasts came before this LyondellBasell Industries earnings beat and refinery sale, so you may see those optimistic cash flow stories shift again.
Explore 6 other LyondellBasell Industries fair value estimates, including one that suggests as much as 127% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your LyondellBasell Industries research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for LyondellBasell Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LyondellBasell Industries' overall financial health at a glance.
Looking for more investment ideas beyond LyondellBasell Industries?
If this LyondellBasell Industries update has sharpened your process, you can use that same lens on a wider watchlist. The Simply Wall St Screener lets you filter for financial quality, balance sheet strength, and income potential so you are not relying on a single story.
- For investors who care most about financial resilience and low downside risk, start with companies that score well on stability using the 29 resilient stocks with low risk scores.
- If income is a priority and you want candidates with higher yields and an emphasis on consistent payouts, scan through the 5 dividend fortresses.
- When you want to widen your radar to lesser known opportunities backed by strong fundamentals, work through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com