


How Investors May Respond To Colgate Stock After Raised Earnings Guidance
- Colgate-Palmolive reported third quarter 2026 sales of US$5,369 million and net income of US$751 million, then raised full year 2026 guidance with expected net sales growth of 4% to 5%, higher gross profit margin on a GAAP basis and double digit earnings per share growth.
- The updated outlook pairs tighter cost discipline with increased advertising spend as a share of net sales, which suggests management is leaning on brand support rather than pulling back on growth investment to protect profitability.
- Attention now turns to how Colgate-Palmolive's higher 2026 earnings guidance, including a stronger gross margin outlook, could reshape the longer term investment narrative.
See how Colgate-Palmolive's tighter cost control and higher earnings outlook compare with other branded consumer stocks by checking our hand-picked 33 high quality undervalued stocks.
Colgate-Palmolive Investment Narrative Recap
To hold Colgate-Palmolive, you need to believe the premium oral care, emerging market exposure and Hill’s Pet Nutrition portfolio can keep earnings growing even when categories slow. The raised 2026 outlook points to better gross margin and disciplined costs, which supports that earnings story rather than reinventing it.
In the short term, the key swing factor is whether North America and pet food categories stabilize while higher advertising spend actually converts into volume and mix. The biggest risk still sits in weak demand in core markets and the recyclability class action, and the latest guidance update does not materially change those pressure points.
The most relevant fresh data point is the Q3 2026 result that sat behind the guidance lift. Colgate-Palmolive reported US$5,369 million in quarterly sales and US$751 million in net income, alongside basic EPS of US$0.94. Those figures, plus nine month numbers, gave management enough confidence to tighten full year expectations.
For you, that links directly back to the catalysts. Premium products, cost programs and tech driven execution are showing up in margins strongly enough for the company to steer toward higher 2026 earnings, even while U.S. oral care, pet food and legal costs remain watch items that could cap how far that improvement runs.
What The Colgate-Palmolive 2029 Consensus Is Pricing In
Colgate-Palmolive's sell side narrative now anchors around a 2029 destination that ties directly back to the higher 2026 guidance investors are reacting to today. Analysts are effectively sketching out what the business would need to look like a few years beyond the current outlook for the present share price and target prices to make sense.
On the top line, the consensus framework leans on 3.2% annual revenue growth over the next three years, with the forecast pointing to US$23.1b of sales by 2029. That profile lines up with the idea of Colgate-Palmolive as a steady, branded consumer products group. In this narrative, pricing, premium tiers and emerging market penetration do more of the lifting than large category volume surges.
Profitability assumptions carry even more weight. Analysts are building in an increase in profit margins from 9.7% today to 14.8% in around three years, which aligns with the current focus on mix upgrades, productivity and SGPP savings. If those numbers eventuate, the earnings engine implied by Hill’s Pet Nutrition, premium oral care and an emerging market skew appears stronger than what the current margin base alone might suggest.
The earnings bridge is central to that story. Forecast consensus calls for earnings to reach US$3.4b by about September 2029, up from US$2.0b today, with more cautious forecasts closer to US$2.9b. That is roughly a US$1.4b uplift from current earnings at the midpoint. Investors can treat this as a way to frame how much confidence they have in Colgate-Palmolive's ability to convert higher gross margin and tighter costs into sustainably higher profit rather than just a short period of operating leverage.
Valuation assumptions knit those building blocks together. For the analyst price targets to line up with those earnings forecasts, Colgate-Palmolive would need to be trading on a P/E of 27.5x in 2029 based on US$3.4b of earnings, compared with about 34.2x today and above the current 22.9x P/E for the broader US household products industry. That multiple path effectively asks whether a premium to the sector remains justified if margins climb as projected but the top line stays in low single digit growth territory.
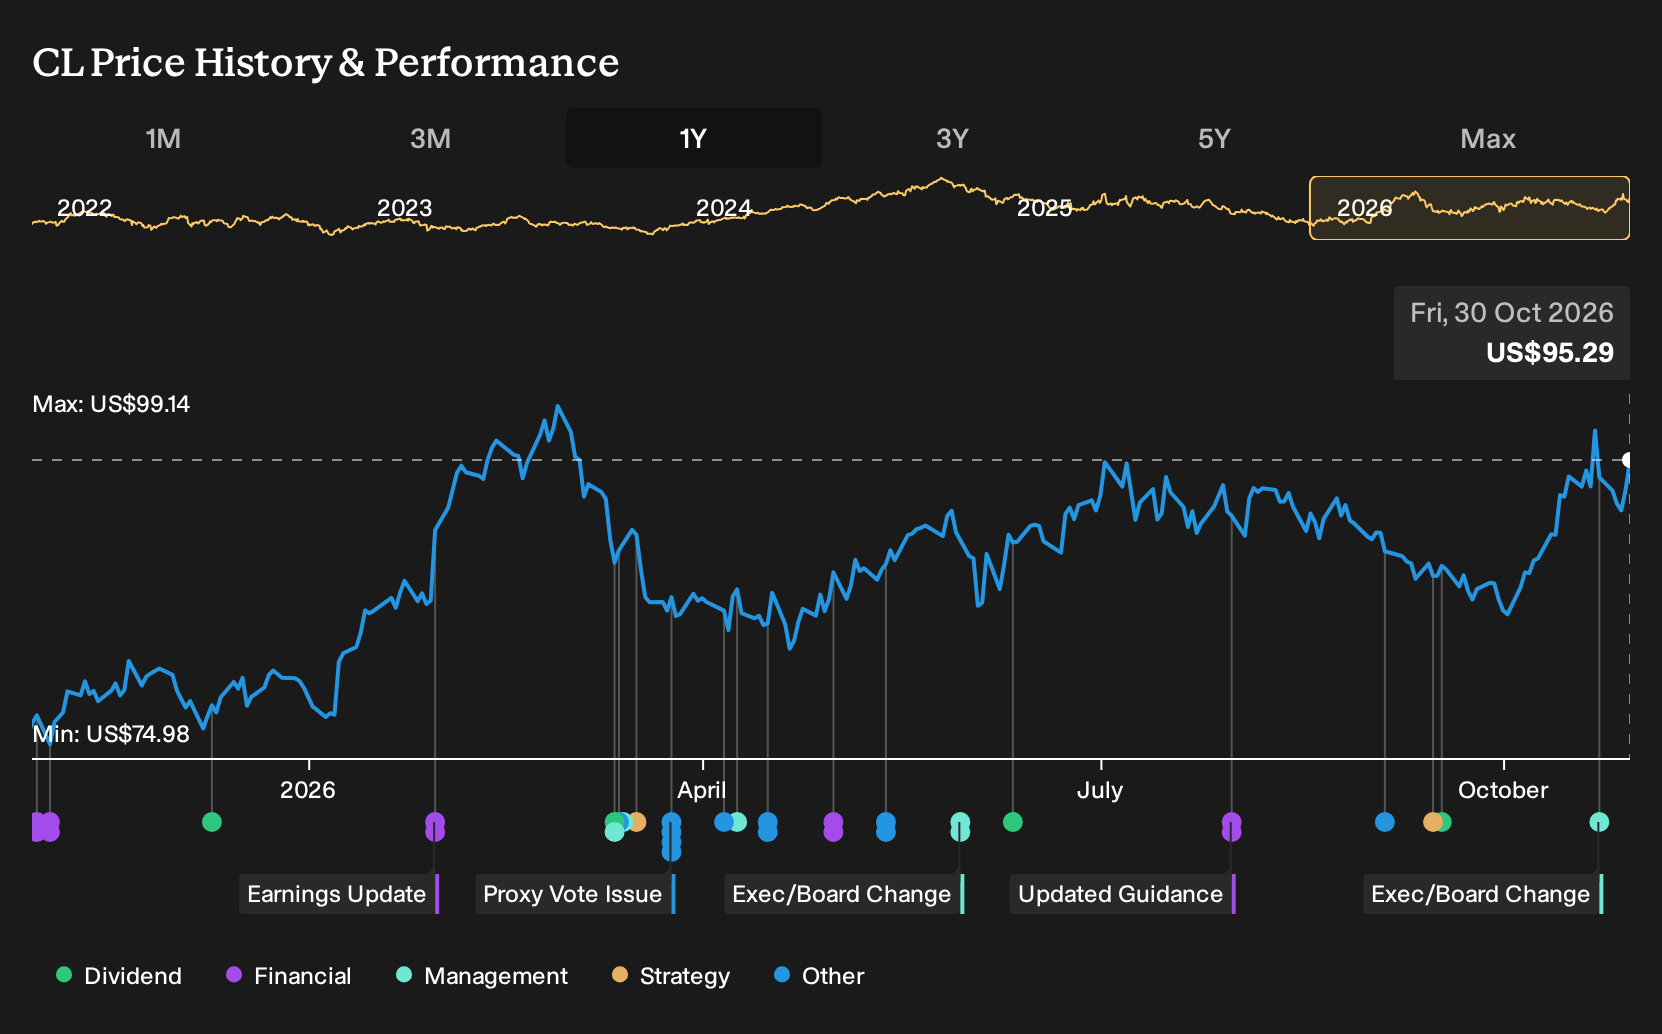
The consensus price target sits at US$98.80 per share, with the most optimistic analyst at US$110.00 and the most cautious at US$87.00, against a current share price cited at US$87.47. That spread reflects different views on how far premiumization, SGPP savings and pet food mix can stretch earnings, and how much legal and category risk investors might factor in when they consider where Colgate-Palmolive could trade on a P/E basis in a few years.
Colgate-Palmolive's narrative projects US$23.1b revenue and US$3.4b earnings by 2029. This requires 3.2% yearly revenue growth and about US$1.4b earnings increase from US$2.0b today.
Uncover why Colgate-Palmolive's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$86 to US$129 per share, which means some retail investors see Colgate-Palmolive as close to fairly priced, while others project a far richer outcome. Set those opinions against the higher 2026 guidance, the marketing leadership change in India, and the ongoing legal and category risks, and you get a wide debate about how resilient Colgate-Palmolive earnings could be. Use that spread to test your own expectations and explore alternative viewpoints before leaning on any single forecast.
Explore 3 other Colgate-Palmolive fair value estimates, including one that suggests up to 9% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Colgate-Palmolive research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Colgate-Palmolive. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easier to evaluate Colgate-Palmolive's overall financial health at a glance.
Looking For More Colgate-Palmolive Style Ideas?
If you like the mix of resilience and earnings focus that Colgate-Palmolive offers, it can help to widen the lens and compare it with other businesses that share some of those traits. The Simply Wall St Screener gives you a way to filter for fundamentals that match your own risk appetite instead of relying on one stock or one storyline.
- If capital preservation comes first for you, start with companies that our models flag as relatively resilient by reviewing 29 resilient stocks with low risk scores.
- For investors who care most about a strong financial base, focus on businesses with cleaner balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (24 results).
- If you like finding opportunities before they are widely talked about, scan through a 19 high quality undiscovered gems that couples quality metrics with less analyst coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com