


Why Otsuka (TSE:4768) Is Getting Attention Right Now
Fresh earnings put Otsuka in focus
Otsuka (TSE:4768) just posted nine month results to September 30, 2026, reporting higher sales, net income, and earnings per share compared with the same period a year earlier.
The earnings release follows a sharp rise in Otsuka’s share price, with a 30 day share price return of 18.42% and a 90 day gain of 35.20%. The 1 year total shareholder return of 47.61% suggests that momentum has been building rather than fading.
Compare Otsuka's momentum with other Japanese tech and software players by scanning our hand picked list of 71 high quality undiscovered gems for potential next ideas.
After a move like this, the real issue is whether Otsuka’s recent strength justifies paying up now or waiting to see if enthusiasm cools and the valuation does the same.
Price-to-earnings of 24.4x for Otsuka: Is it justified?
On simple earnings terms, Otsuka trades on a P/E of 24.4x, which prices the shares above the broader JP IT industry average of 16.1x, even though the stock has already enjoyed a strong run to ¥4,352.
The P/E ratio compares the current share price to earnings per share and gives you a quick sense of how much investors are willing to pay for each unit of profit. For a software and IT services group like Otsuka, this often reflects expectations for steady cash generation and the perceived reliability of those profits rather than explosive expansion.
That context matters. Earnings are forecast to grow at around 8.4% per year, while revenue is expected to advance about 5.7% annually, both slower than the wider JP market. Against that growth profile, the market is still assigning Otsuka a P/E that is higher than the JP IT industry average, although it is slightly below an estimated fair P/E of 25.1x that the market could move towards if sentiment stays supportive.
Relative pricing is even starker when you look at peers, since similar companies trade on an average P/E of 58.8x and Otsuka screens as good value on that comparison. At the same time, the SWS DCF model points to a future cash flow value of about ¥3,545.92 per share, below the current price, which suggests the market is paying a premium over that cash flow based estimate and may be rewarding the group for what are assessed as high quality earnings.
Explore the SWS fair ratio for Otsuka.
Result: Price-to-earnings of 24.4x (ABOUT RIGHT)
Still, Otsuka’s premium P/E and the intrinsic value estimate below the current ¥4,352 price leave the story exposed to any disappointment in earnings quality or IT spending demand.
Find out about the key risks to this Otsuka narrative.
Another view on Otsuka’s value
On a cash flow lens, the SWS DCF model points to a future value of about ¥3,545.92 per share, which sits below Otsuka’s recent ¥4,352 price. That gap suggests investors are paying up for qualities the model does not fully capture. The question is how comfortable you are owning that premium.
Look into how the SWS DCF model arrives at its fair value.
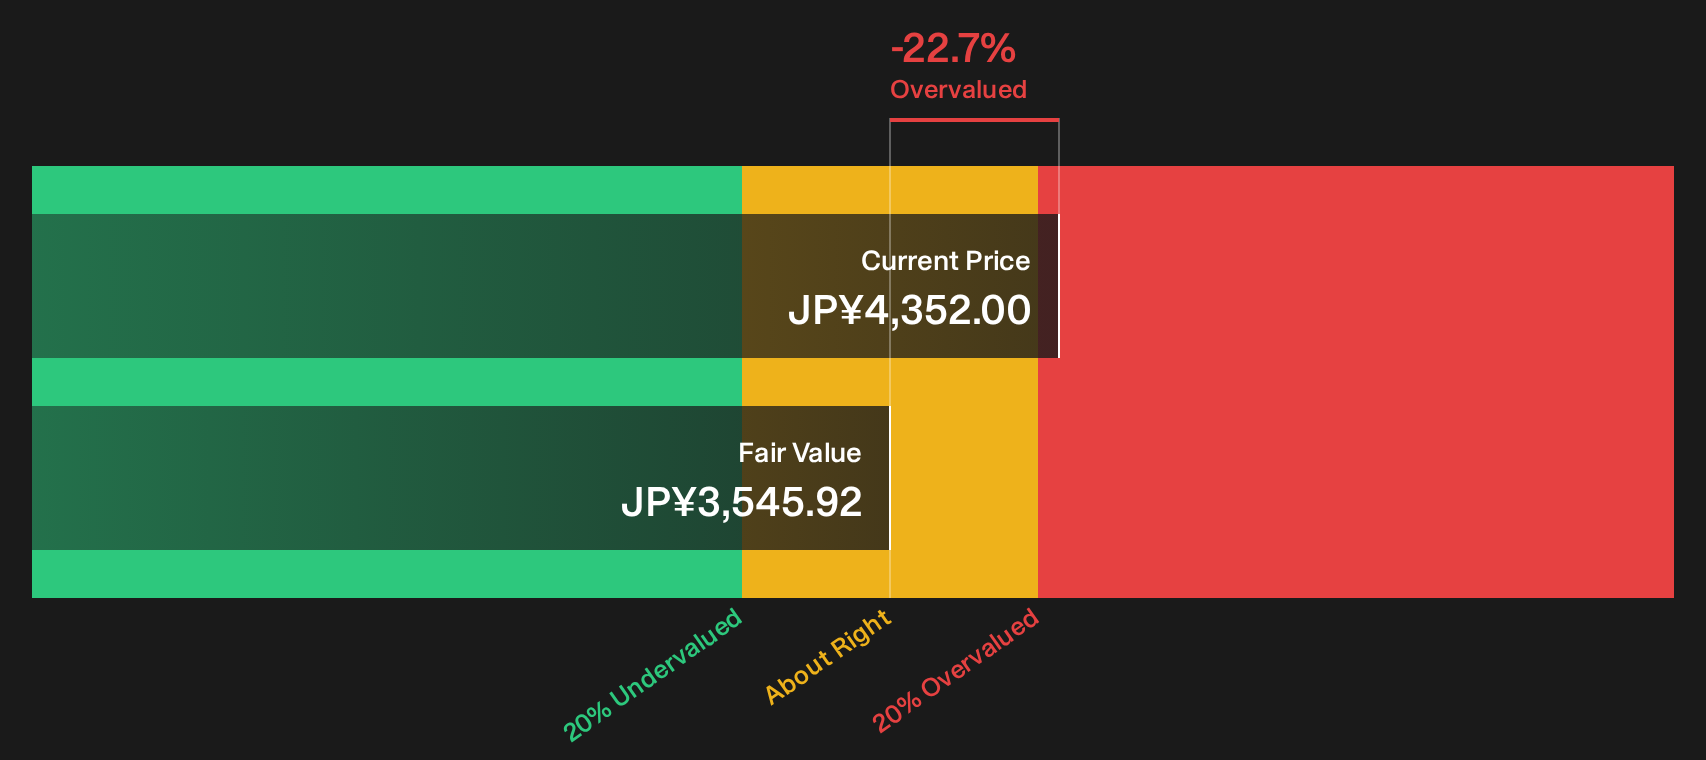
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Otsuka for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings about Otsuka’s premium price and its fundamentals are natural. Move quickly, review the full data, and weigh both sides with the 2 key rewards and 1 important warning sign.
Ready for more ideas beyond Otsuka?
Momentum around Otsuka is a useful signal, but the real edge comes from lining up a watchlist of strong alternatives before the crowd gets interested.
- Target resilient balance sheets and consistent fundamentals by scanning a focused list of solid balance sheet and fundamentals (22 results) that filters for financial strength first.
- Hunt for quality companies that may trade below their assessed worth by working through a curated 14 high quality undervalued stocks built around fundamentals, not hype.
- Stack potential income and capital return together by reviewing a hand picked 30 dividend fortresses that screens for higher yields and sturdier payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com