


Ameris Bancorp (ABCB) Reports Higher Quarterly Profit, Is The Stock Fully Valued?
Ameris Bancorp (ABCB) just released third quarter 2026 results, reporting higher quarterly net interest income and net income than a year earlier, along with increased net charge-offs for the same period.
Ameris Bancorp’s share price closed at $82.42 on 22 October 2026, with the stock up 1.20% over the past month but down 6.54% across three months. The 1-year total shareholder return of 16.23% and 3-year total shareholder return of 103.80% point to stronger longer term momentum.
Spot similar regional banks that combine earnings momentum with tighter credit costs by scanning our hand picked 29 resilient stocks with low risk scores aligned with Ameris Bancorp’s profile.Ameris Bancorp has moved higher over the past year, yet the share price still sits below both analyst targets and implied fair value estimates. Does that gap signal lingering caution or room for re rating as the valuation work starts?
Most Popular Narrative: 12% Undervalued
Ameris Bancorp’s most followed narrative pegs fair value at about $94.17 per share, compared with the recent $82.42 close. This frames a modest valuation gap that leans on deposit mix, efficiency and credit discipline rather than a simple rerating story.
The main thing that has to go right is that Ameris continues to fund loan growth with granular core and noninterest-bearing deposits while holding efficiency near the low 50% range and keeping credit losses within the guided 20 to 25 basis point band.
The current valuation implies that the market is discounting the combination of strong profitability metrics, conservative credit and capital positions, and active share repurchases, which together support the view that Ameris Bancorp is undervalued.
See why 2 investors see Ameris Bancorp as 12% undervalued.
Result: Fair Value of $94.17 (UNDERVALUED)
Still, the Ameris Bancorp story could be tested if the US$82.5 million litigation accrual grows further or if rising deposit costs compress net interest margin faster than expected.
Find out about the key risks to this Ameris Bancorp narrative.
Another View: Ameris Bancorp On Earnings Multiples
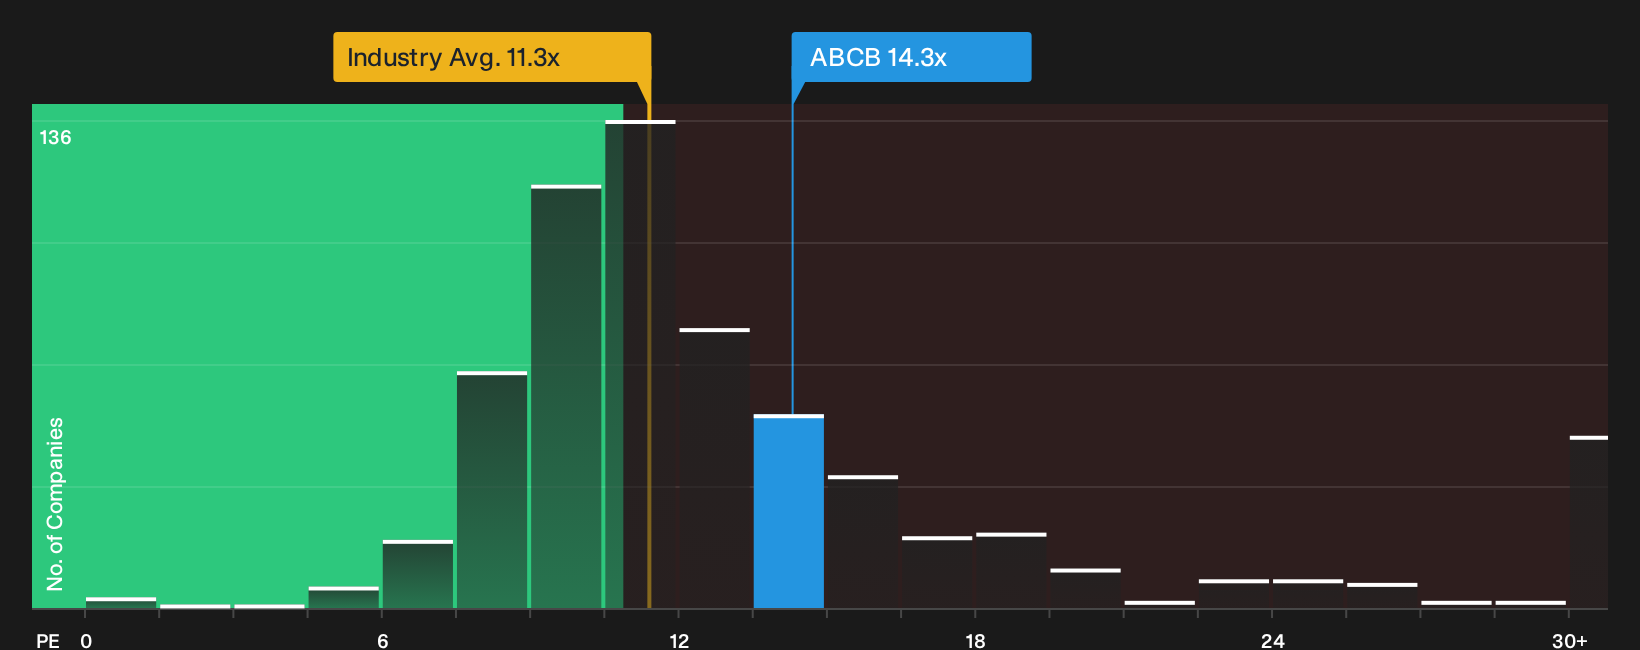
The story changes when you look at Ameris Bancorp through its P/E. The shares trade on 14.3x earnings, compared with about 11.4x for the US Banks industry, 11x for peers, and a fair ratio estimate of 12.8x. That richer tag shifts the question to valuation risk rather than pure upside.
It raises a simple dilemma for investors: Is the current premium a fair price for Ameris Bancorp’s profile, or does it leave less room for error if earnings or credit trends soften from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Ameris Bancorp is mixed, so this is a moment to move quickly and stress test the story against your own criteria. To see why some investors still focus on potential upside drivers, review the 2 key rewards
Looking for more Ameris Bancorp style investment ideas?
If you stop with Ameris Bancorp, you risk missing opportunities that better match your goals, risk limits, and income needs across the rest of your portfolio.
- Target potential mispricings by reviewing companies flagged as 33 high quality undervalued stocks that pair solid fundamentals with valuations that differ from current market expectations.
- Strengthen portfolio resilience by focusing on businesses screened for robust finances through our curated list of solid balance sheet and fundamentals (24 results).
- Hunt for off-the-radar opportunities by scanning a focused list of 19 high quality undiscovered gems that combine quality metrics with lower investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com