


LIXIL (TSE:5938) Q2 Results Deepen Margin Strain After EPS Loss
LIXIL walked into its Q2 2027 earnings with the stock down over the past week and quarter, closing at ¥1,662.5 on the day of the release. The headline result was harsh on the surface. The company reported another quarterly loss, with basic earnings per share of ¥3.76 in the red and net income excluding one offs also in the red at ¥1.1b.
That backdrop feeds a sentiment reckoning. Recent share price drift looks modest compared with the scale of earnings pressure, which suggests investors are either numb to bad news or placing more weight on the longer term recovery story than on this quarter’s profit squeeze.
Like the turnaround angle at LIXIL but worried about another quarterly loss and red ink on earnings per share? Benchmark that story against companies already pairing solid fundamentals with cleaner financials in our list of solid balance sheet and fundamentals stocks (22 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥383,249m vs. ¥371,262m (top line was broadly steady with a modest year on year uplift)
- Net Income/Loss, Excl. Extra Items (Q2 2027 vs. Q2 2026): loss of ¥1,082m vs. profit of ¥4,264m (swung from black to red at the bottom line)
- Basic EPS (Q2 2027 vs. Q2 2026): loss of ¥3.76 per share vs. earnings of ¥14.83 per share (moved from positive to negative earnings per share)
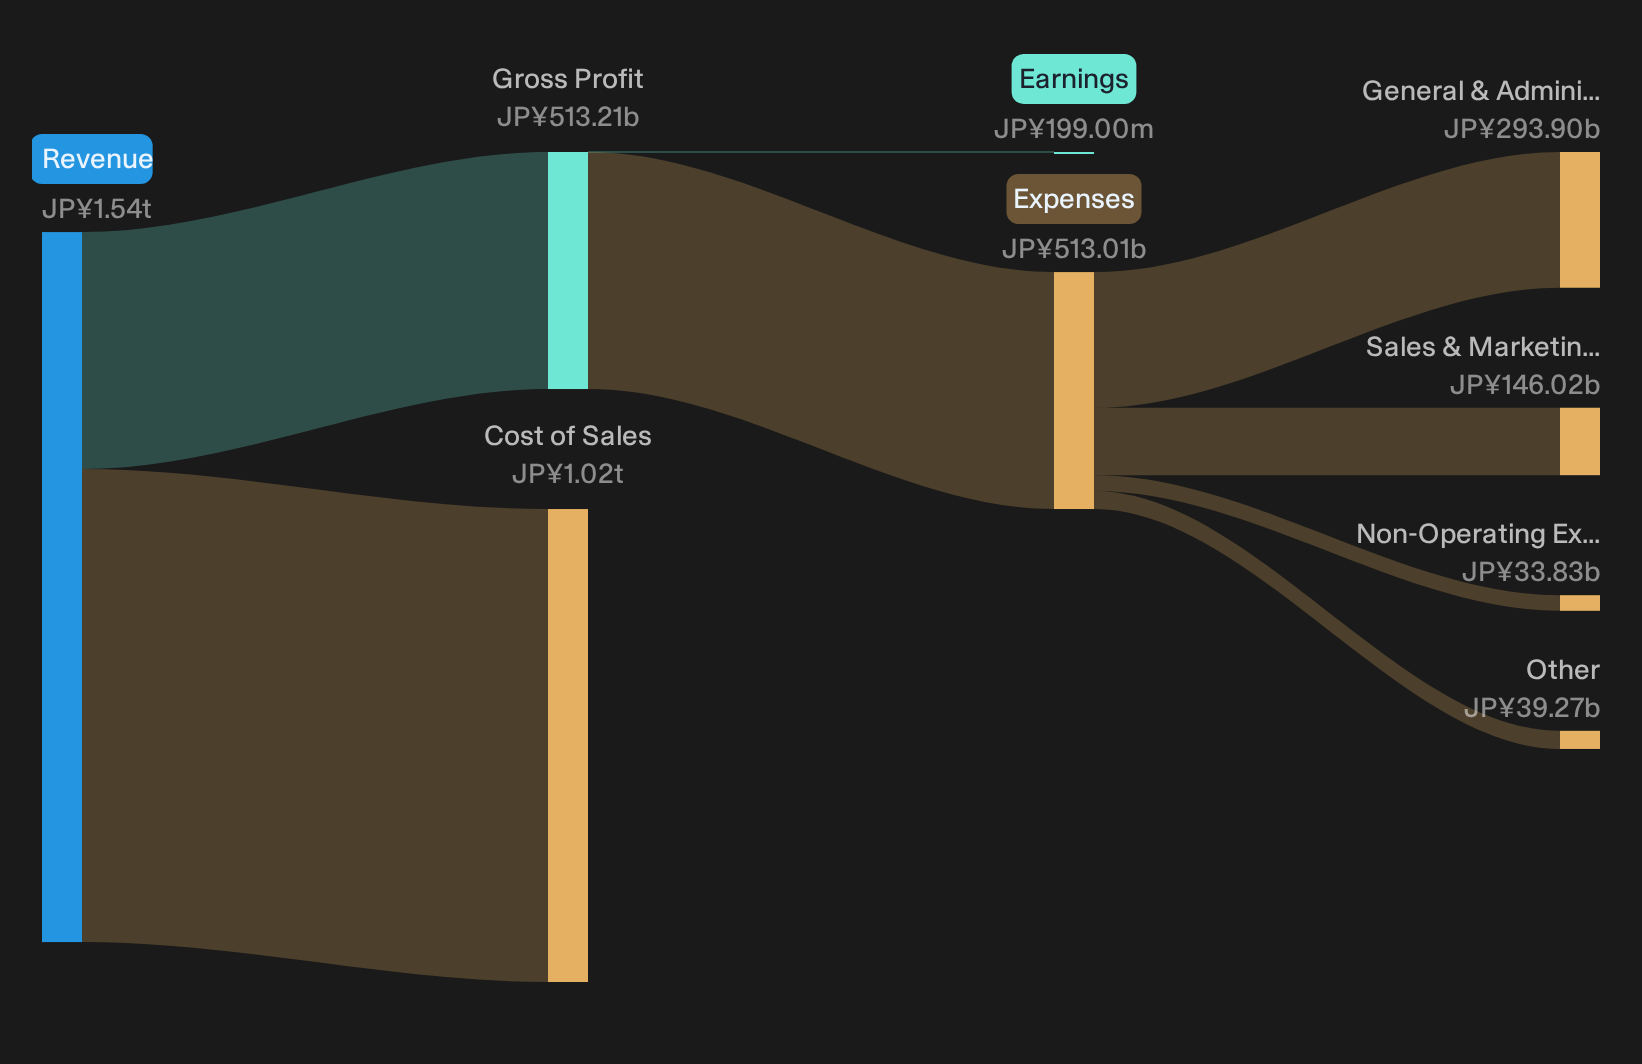
- Trailing 12-month Net Income, Excl. Extra Items (TTM to Q2 2027 vs. TTM to Q2 2026): ¥199m vs. ¥9,354m (full year profitability was sharply weaker than the prior 12 months)
LIXIL pricing and local supply plan meets first hurdles
The bullish story depends on LIXIL turning pricing power and local supply into better profitability rather than just talking about them.
"The main thing that has to go right is that LIXIL successfully passes through more than ¥30b of input cost increases while executing plant closures, supply chain localization and Americas and regional portfolio reforms without renewed earnings drag."
The latest quarter shows that goal only partially in sight. Domestic water products saw better profit after summer price moves, and U.S. structural reforms reduced losses, which aligns with the thesis. Yet group core earnings suffered, LHT margins were hit by earlier aluminum spikes, and free cash flow weakened as working capital rose.
The price and this Narrative do not agree. → Uncover what this Narrative says LIXIL is actually worth.
LIXIL bear case on margins still largely intact
Bearish investors worry that LIXIL’s cost shocks keep outrunning its fix-it plan. The concern is blunt.
"Despite plans to offset more than JPY 30b of petrochemical, aluminum, fuel and copper cost headwinds through price revisions, hedging and logistics rationalization, current estimates of roughly JPY 49.2b of additional material and logistics cost increases versus plan highlight a risk that input cost volatility absorbs much of the expected pricing benefit and keeps gross margins under pressure."
Q2 results lean toward that caution. Revenue was steady, yet core earnings weakened and the quarter landed in a loss. LHT profits were hit as aluminum and logistics costs bit before October price rises. Domestic water products and U.S. restructuring helped, but not enough to show clear margin repair.
Hunt For Cleaner Balance Sheets
LIXIL just showed how a difficult quarter can leave the equity story feeling unfinished. The real opportunity sits in finding stocks that could have cleaner balance sheets before the market closes that gap.
- Company 1 - 45% below our estimate - uses AI and cloud investment to deepen subscription security tools within key customer workflows.
- Company 2 - 35% below our estimate - monetizes digital matching by charging for sponsored placements and transaction-linked access across hiring and local services.
- Company 3 - 18% below our estimate - adds focused sales capacity to secure maintenance agreements and capture modernization projects on installed equipment.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com