


Mitsui DM Sugar (TSE:2109) Stock Faces Margin Squeeze After Q2 Results
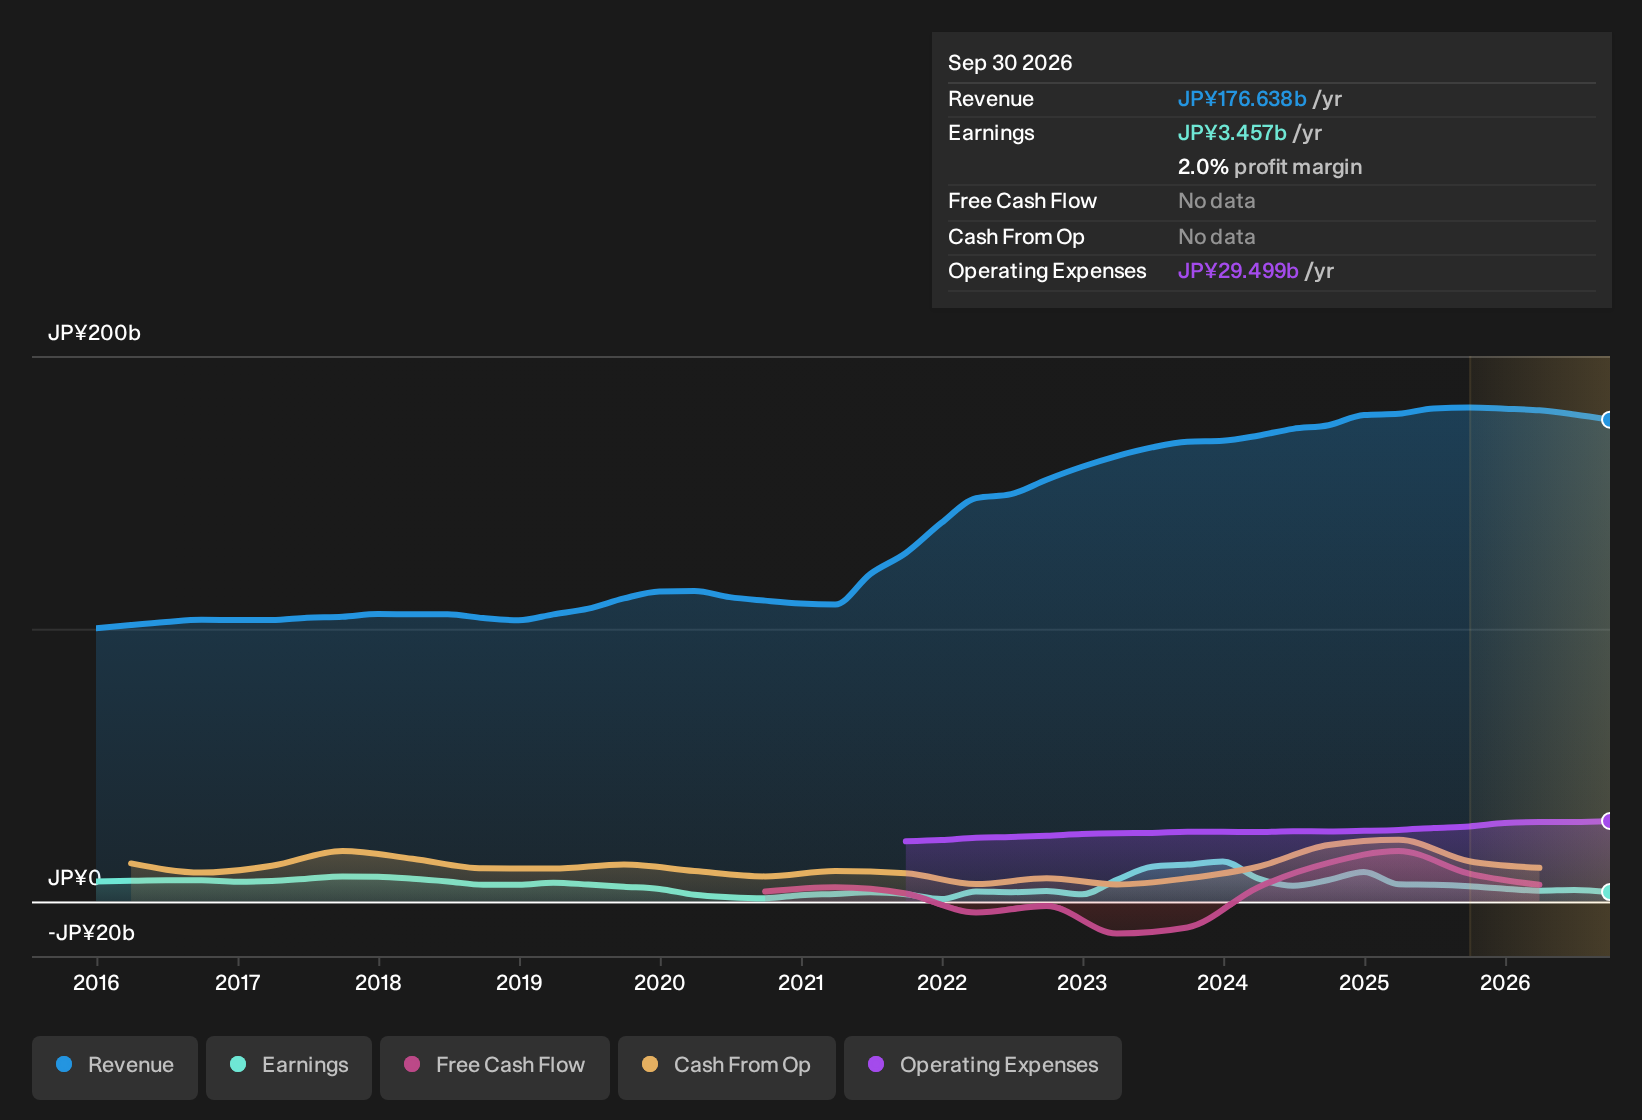
Mitsui DM Sugar came into this Q2 2027 report with its stock under a cloud, down over 5% across both the past week and month and trading on a rich 32.2x P/E despite thin 2% trailing net margins. The new quarterly print shows revenue of ¥41,567m and basic earnings per share of ¥41.49, and that mix is what investors are now weighing against a share price of ¥3,575 that already reflects recent weakness. For you, the key question is how much pressure that slim profitability puts on the long term thesis from here.
Like the underlying Mitsui DM Sugar business but uncomfortable with thin 2% net margins sitting against a 32.2x P/E? Set a higher bar for balance sheet strength and earnings quality by comparing it with our list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Mitsui DM Sugar Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥41,567m vs. ¥43,489m (down 4.4%)
- Net Income (Excl. Extra Items, Q2 2027 vs Q2 2026): ¥1,291m vs. ¥2,056m (down 37.2%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥41.49 vs. ¥66.09 (down 37.3%)
- Trailing Net Profit Margin (Last 12 Months vs Prior 12 Months): 2.0% vs. 3.1% (margin compressed, indicating weaker profitability)
Ask Charlie what Mitsui DM Sugar’s big write-off means for earnings.
Mitsui DM Sugar: Testing The Defensive Story
For anyone leaning on Mitsui DM Sugar as a resilient, staples style play, the latest figures make that case harder. Revenue slipped 4.4% year on year while net income excluding one offs fell 37.2%, which pulled basic EPS down to ¥41.49. Trailing net margin moved from 3.1% to 2.0%, so the cushion on each yen of sales has thinned. That pattern sits awkwardly with a pure defence narrative built on steady cash generation from sugar and real estate.
Profit Squeeze Puts Bearish Concerns In Focus
Bears worried about margin pressure and limited pricing power will see this quarter as supporting evidence. A 4.4% top line decline turned into a much sharper 37.2% drop in underlying profit, pointing to rising costs or weaker mix that Mitsui DM Sugar has not offset. The trailing net margin compression to 2.0% reinforces that concern. Recent share price weakness over the past week and month suggests investors are already wrestling with these pressures rather than dismissing them as a one off blip.
After a 4.4% revenue decline turned into a 37.2% fall in underlying profit and thinner 2.0% margins, it is fair to ask whether Mitsui DM Sugar is just dealing with a rough quarter or revealing a deeper earnings quality problem. Before you assume the pressure stops here, review the independent risk analysis for Mitsui DM SugarLtd which shows 3 important warning signsHunt Stronger Balance Sheets Quietly
Mitsui DM SugarLtd just showed how quickly thin margins can compress when costs bite. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 35% below our estimate - builds AI driven hiring and local services platforms tying fees to successful matches and transaction volumes.
- Company 2 - 18% below our estimate - expands its salesforce to win maintenance contracts that feed higher margin modernization work.
- Company 3 - 45% below our estimate - shifts its security business toward AI native platforms and subscriptions raising recurring revenue from protection services.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com