


Tsubakimoto Kogyo (TSE:8052) Stock Lacks Urgency After Q2 Earnings Strength
Tsubakimoto Kogyo walked into this Q2 2027 print with a reputation for steady, workmanlike execution and a stock priced at ¥2,967 that had drifted slightly over the past month but still delivered a solid 90 day gain. The fresh quarter did not rewrite the story; it quietly reinforced it. Revenue reached ¥35,416m and basic earnings per share came in at ¥88.75, helping lift trailing earnings and keeping the P/E multiple around 10x. The share price move looks muted next to those numbers, which matters for anyone weighing a business with profit growth against a market that already looks cautious.
If you appreciate the steady earnings at Tsubakimoto Kogyo and are looking for more ideas where reasonable P/E multiples align with proven profitability and balance sheet strength, take a look at the list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥35,416m vs. ¥34,324m (up about 3.2%)
- Net Income, Excl. Extra Items (Q2 2027 vs. Q2 2026): ¥1,632m vs. ¥1,107m (up about 47.4%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥88.75 vs. ¥60.27 (up about 47.2%)
- Trailing 12 Month Basic EPS (Q2 2027 TTM vs. Q2 2026 TTM): ¥295.30 vs. ¥278.00 (up about 6.2%)
Prefer clean, visual charts over another wall of earnings tables and footnotes? See Tsubakimoto Kogyo’s full financial picture, including how the valuation lines up with its recent profit performance, in the interactive company report for Tsubakimoto Kogyo.
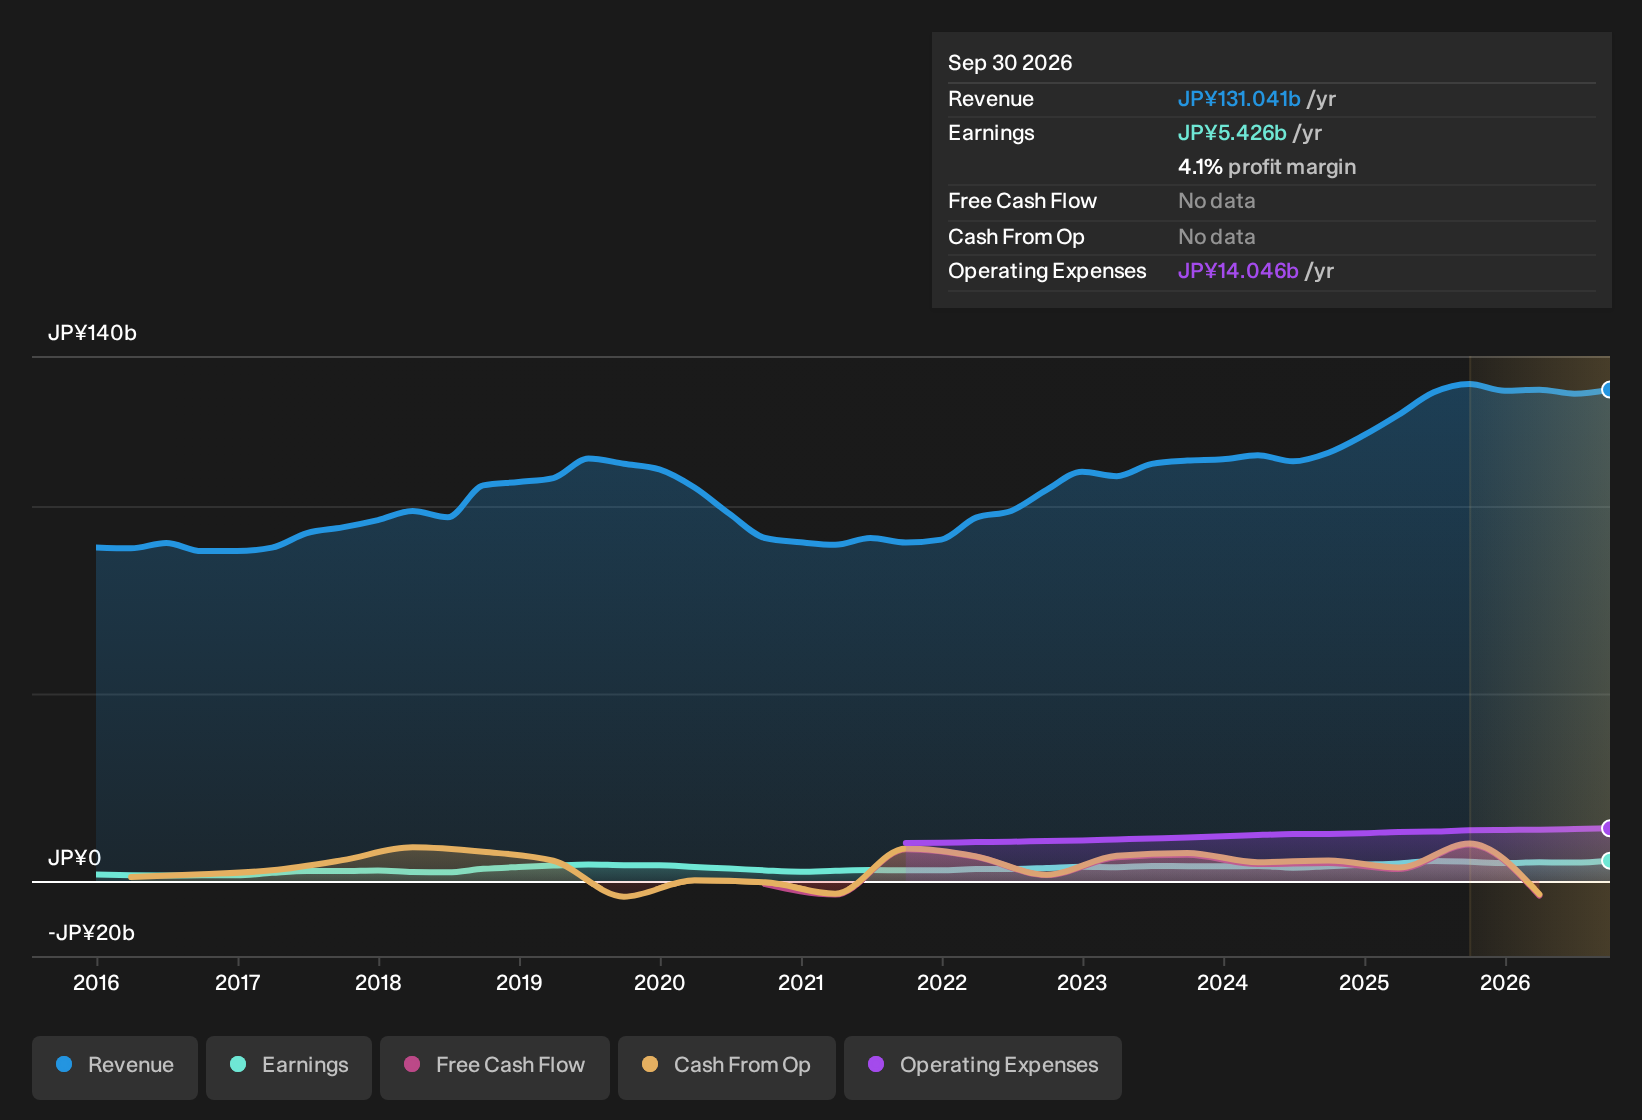
Stronger earnings keep Tsubakimoto Kogyo thesis intact
For investors who see Tsubakimoto Kogyo as a steady industrial backbone, these results generally point in the right direction. Revenue in Q2 2027 moved ahead while net income excluding extras and basic EPS rose much faster, which hints at firmer underlying profitability rather than just top line support. Trailing 12 month EPS also stepped up, so you are not looking at a one quarter blip. With the newly announced share buyback program added to the mix, the overall picture is of a quietly confident, cash generative industrial distributor.
Short term softness leaves room for caution
There is still a cautious side to the story. The share price has drifted slightly over 7 and 30 days even as earnings improved, which suggests investors are not rushing to re-rate Tsubakimoto Kogyo on these numbers alone. Industrial exposure across many end markets also keeps the business tied to capital spending cycles, so the stronger profit print and buyback help offset, but do not remove, those cyclical concerns. The result is a company that appears solid on recent figures while sentiment remains measured rather than euphoric.
After a cash funded dividend that is not well covered by free cash flows, you might ask whether this is an isolated pressure point or a clue to broader balance sheet strain. Scan the independent risk analysis for Tsubakimoto Kogyo which shows 1 important warning sign.Hunt For Quiet Balance Sheet Strength
Tsubakimoto Kogyo recently reported firmer earnings while the share price remained muted. The real opportunity is in stocks that could be low debt before the market recognizes their balance sheet strength.
- Company 1 - 45% below our estimate - targets higher subscription revenue by linking security workloads and digital life services into a unified AI-focused platform.
- Company 2 - 35% below our estimate - pushes AI-driven tools that align hiring budgets and marketing spend directly to candidates and local service providers.
- Company 3 - 18% below our estimate - adds more salespeople to sign maintenance contracts that deepen service density around existing elevator and modernization projects.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com