


Kohsoku (TSE:7504) Stock Price Faces A Q2 Earnings Valuation Check
Kohsoku walked into this Q2 2027 earnings print priced for excellence. The packaging specialist traded at a P/E near 23x, well above sector averages, after a strong 30 day share price gain of about 14.9% into the ¥5,180 close on 30 October.
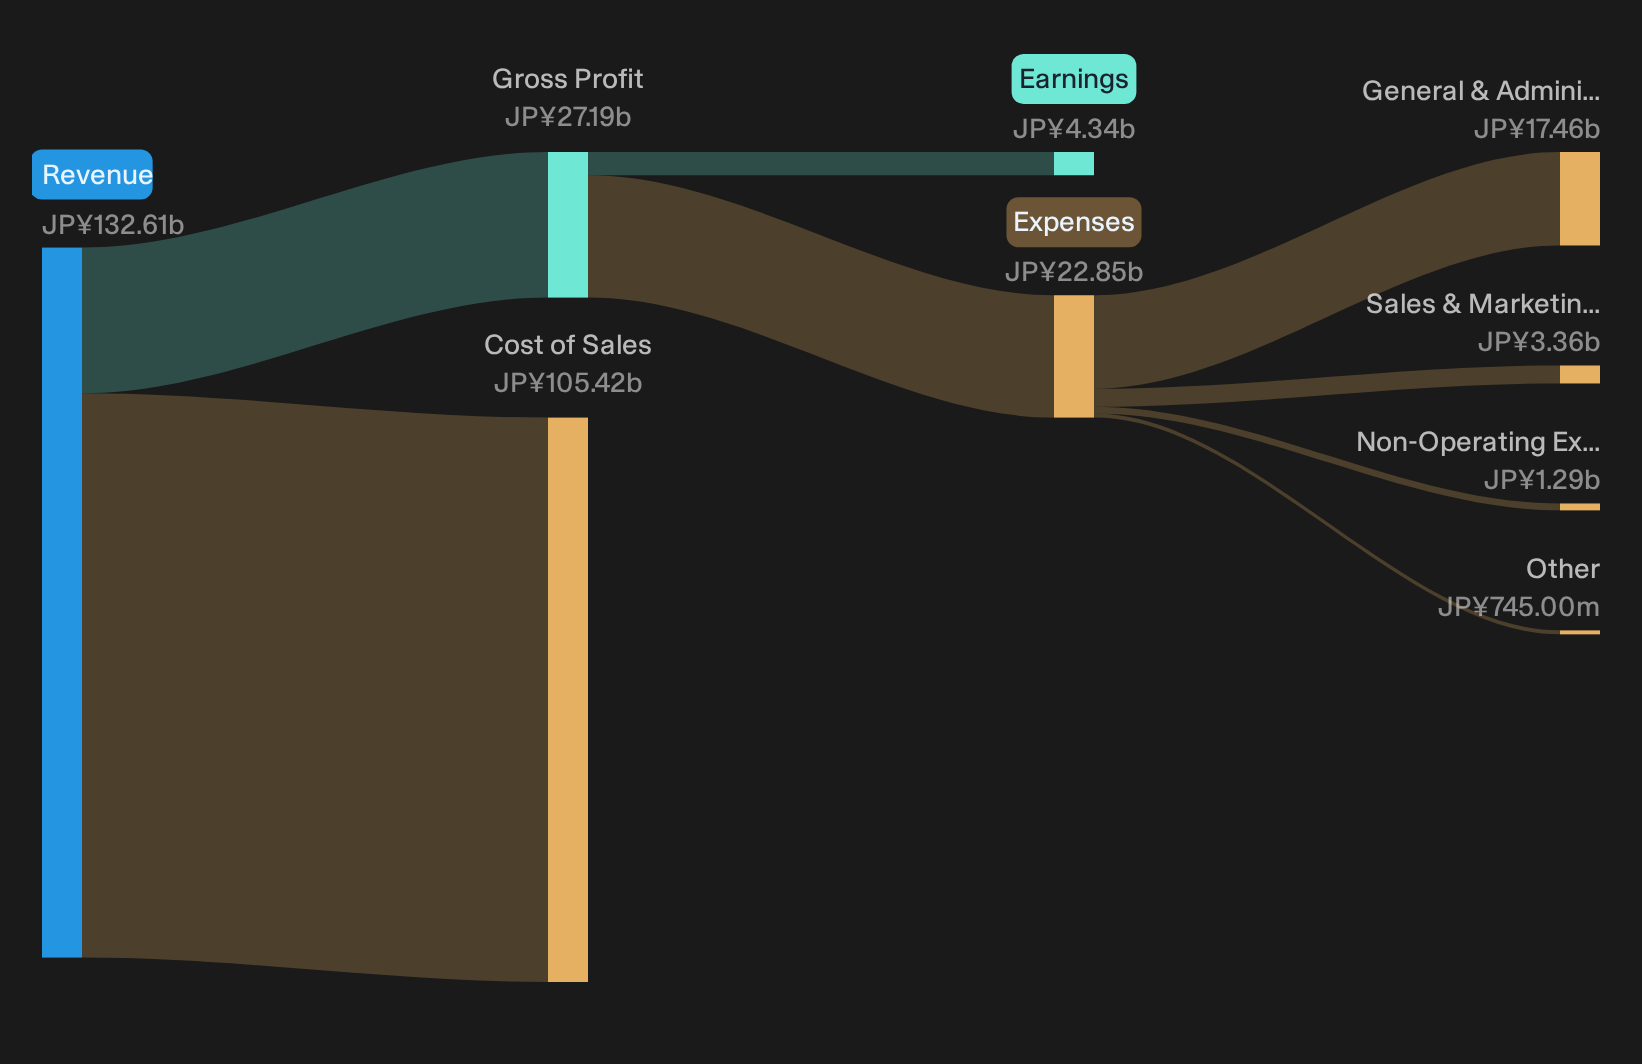
The headline result is clean. Quarterly revenue reached ¥36,169m and basic earnings per share came in at ¥60.63, both consistent with the previously stated pace of earnings growth of 20.5% over the past year. Any short term price swing now pits that rich valuation against a solid yet tightly priced growth story.
Love Kohsoku’s clean earnings print but wary of paying up at a 23x P/E for tightly priced growth. See our shortlist of stocks that pair solid fundamentals with more grounded valuations in the 14 high quality undervalued stocks
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥36,169m vs. ¥30,943.629m (around 16.9% higher)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥1,178m vs. ¥1,004.536m (around 17.3% higher)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥60.63 vs. ¥51.45 (around 17.9% higher)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 3.3% vs. 2.9% (moderately stronger profitability on recent earnings)
Kohsoku’s growth is strong but the stock looks pricey. Ask Charlie what makes Kohsoku worth a premium price.
Kohsoku earnings support a resilient defence story
Kohsoku looks like a textbook defensive food packaging business here. Revenue of ¥36,169m versus ¥30,943.629m and basic EPS of ¥60.63 versus ¥51.45 both point in the same direction as the sector narrative of steady demand from everyday consumption. Net profit margin at 3.3% versus 2.9% on a trailing basis backs that up. The equity market has already been rewarding this consistency, with roughly 15% and 9% share price gains over 30 and 90 days. This fits a slow burn, earnings led optimism rather than a speculative story.
Risks look contained but pricing power still key
Bears often worry about margin pressure from input costs in packaging. Kohsoku’s trend from a 2.9% to 3.3% trailing net margin runs against that concern and hints at at least some cost discipline or pricing power. Profit of ¥1,178m versus ¥1,004.536m on an ex items basis moves in the same direction. Shorter term share performance, up about 4% over 7 days, also suggests investors are not treating these results as a warning signal. Longer term structural risks around regulation and materials mix remain unanswered here.
After a margin story like this, the real question is whether softer free cash cover and share price swings hint at deeper fragility. Review our independent risk analysis for Kohsoku which shows 2 important warning signsHunt For Stronger Balance Sheets
Kohsoku just showed how clean earnings can still sit against a full valuation story. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 18% below our estimate - builds a larger sales force to win long term maintenance contracts and deepen route density.
- Company 2 - 45% below our estimate - shifts customers onto an AI focused security platform that converts one off licenses into expanding subscription agreements.
- Company 3 - 35% below our estimate - links hiring budgets and marketing spend to AI driven job and service matching tools tied to actual transaction volume.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com