


Sankyu (TSE:9065) Stock Q2 Earnings Hint At Margin Strength
Traders barely flinched at Sankyu on results day. The stock closed at ¥1,652 after Q2 2027 figures hit the tape, a level that already reflects a modest 30 day gain and a weaker 90 day patch. The fresh report told a quieter story on the surface with quarterly revenue near ¥154,165m and net income of ¥8,634m. Yet the real action sat in the trailing picture.
Sankyu’s earnings over the last twelve months and the improved profit margin now frame the debate. Short term price noise is bumping up against multi year earnings power and valuation gaps that are hard to ignore.
Like the earnings profile at Sankyu but unsure how to value a quieter revenue line beside stronger trailing profits? Benchmark it against 14 high quality undervalued stocks to see how other solid operators with possible valuation gaps line up.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥154,165 million vs. ¥161,585 million (directional decline)
- Net Income, Excl. Extra Items (Q2 2027 vs. Q2 2026): ¥8,634 million vs. ¥7,211 million (up about 19.7%)
- Basic EPS (Q2 2027 vs. Q2 2026): Data for Q2 2027 not disclosed vs. ¥27.92 in Q2 2026 (comparison not available)
- Trailing 12 Month Net Profit Margin (TTM to Q2 2027 vs. TTM to Q2 2026): 5.7% vs. 5.0% (improved profitability)
Sankyu’s profits are rising faster than its revenue. Ask Charlie what makes Sankyu’s earnings grow faster than sales.
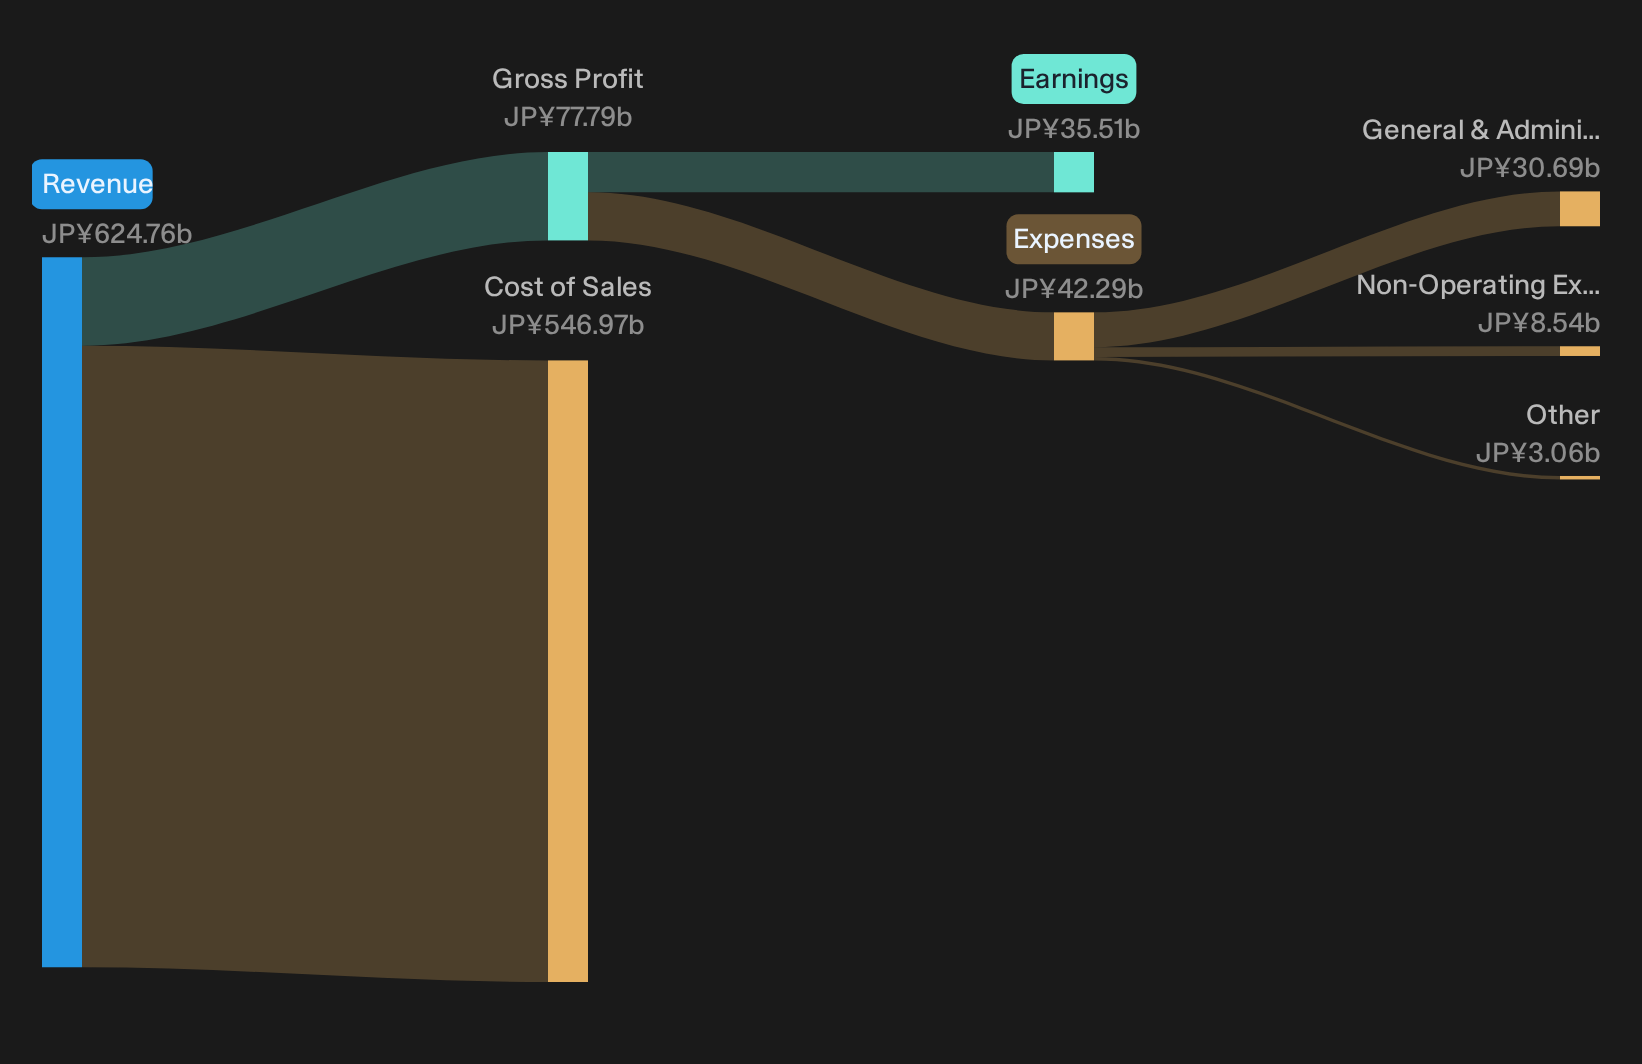
Sankyu earnings, steadier margins, cautious optimism
Sankyu now shows a mix of softer sales and firmer profitability. Revenue in Q2 2027 sits below Q2 2026 levels, yet net income is higher and the trailing 12 month net margin has improved to 5.7% from 5.0%. That combination aligns with a mildly positive view that this logistics and industrial services group can deliver better earnings quality even when the top line is not pushing higher. For investors who see Sankyu as an essential industrial backbone, more efficient profit conversion supports that long term narrative.
Revenue softness tests Sankyu industrial backbone story
The flip side is clear. Q2 2027 revenue of ¥154,165m is below the prior Q2, which contributes to a more cautious story around cyclical exposure to freight and engineering projects. Higher earnings on a smaller sales base can also reflect cost cuts or mix rather than broad business momentum. With the share price up over the past month yet down over 90 days, trading still indicates some hesitation about how durable this margin improvement is if industrial and logistics volumes come under heavier pressure.
With Sankyu posting firmer margins on softer revenue and trading at a lower P/E than peers, the key question is whether liquidity and leverage quietly limit that potential upside. Check the full financial health analysis of Sankyu stock to verify the balance sheet strength before you take that risk.Hunt Quiet Balance Sheet Setups
Sankyu reports firmer margins on softer revenue, prompting debate about the quality of the improvement. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 35% below our estimate - uses AI driven hiring and local service matching to move more fees through digital channels.
- Company 2 - 18% below our estimate - expands a maintenance focused sales force so elevator contracts convert into modernization and recurring service revenue.
- Company 3 - 45% below our estimate - leans into AI native security platforms so subscription protection gradually replaces one time software licenses.
Those are three of them. See all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com