


Earnings Beat Might Change The Case For Investing In Life Time Stock (LTH)
- Life Time Group Holdings reported Q3 2026 revenue of US$893.52 million and net income of US$106.49 million, alongside higher full year revenue guidance and reaffirmed net income expectations, while also updating investors on prior share repurchases and club expansion plans.
- An interesting angle is Life Time's nationwide rollout of DUPR-based pickleball programming and app integration, which ties digital tools directly to in-club engagement and could influence how members use services across its fitness centers.
- Now the focus turns to how Life Time Group Holdings' stronger outlook and club rollout plan may reshape the investment narrative for readers.
Compare Life Time Group Holdings' club driven momentum with a curated set of fitness and experience focused operators by scanning the 19 high quality undiscovered gems that pair solid fundamentals with under-the-radar stories.
What Is Life Time Group Holdings' Investment Narrative?
To own Life Time Group Holdings, you have to buy into a fairly simple story. The business is trying to turn a capital heavy network of resort style clubs into consistent earnings, helped by pricing power, steady membership demand and higher margin in center spending. The latest quarter, with US$893.52 million in revenue and US$106.49 million in net income, supports that view and the DUPR partnership shows that management is still pushing harder on engagement rather than pulling back.
In the short term, the key levers are execution on the planned club rollout, keeping membership churn in check and making sure the pickleball and broader wellness offerings translate into paid usage, not just app logins. Full year revenue guidance has edged higher while net income expectations sit near the prior range. That keeps attention squarely on capital intensity and returns on new projects, especially with Life Time Group Holdings already carrying a P/E above its own internal fair value estimate.
That said, there is one operational pressure point that could matter far more to Life Time Group Holdings shareholders than this upbeat quarter.
There's only one way to know the right time to buy, sell or hold Life Time Group Holdings. Head to Simply Wall St's company report for the latest analysis of Life Time Group Holdings's Fair Value.
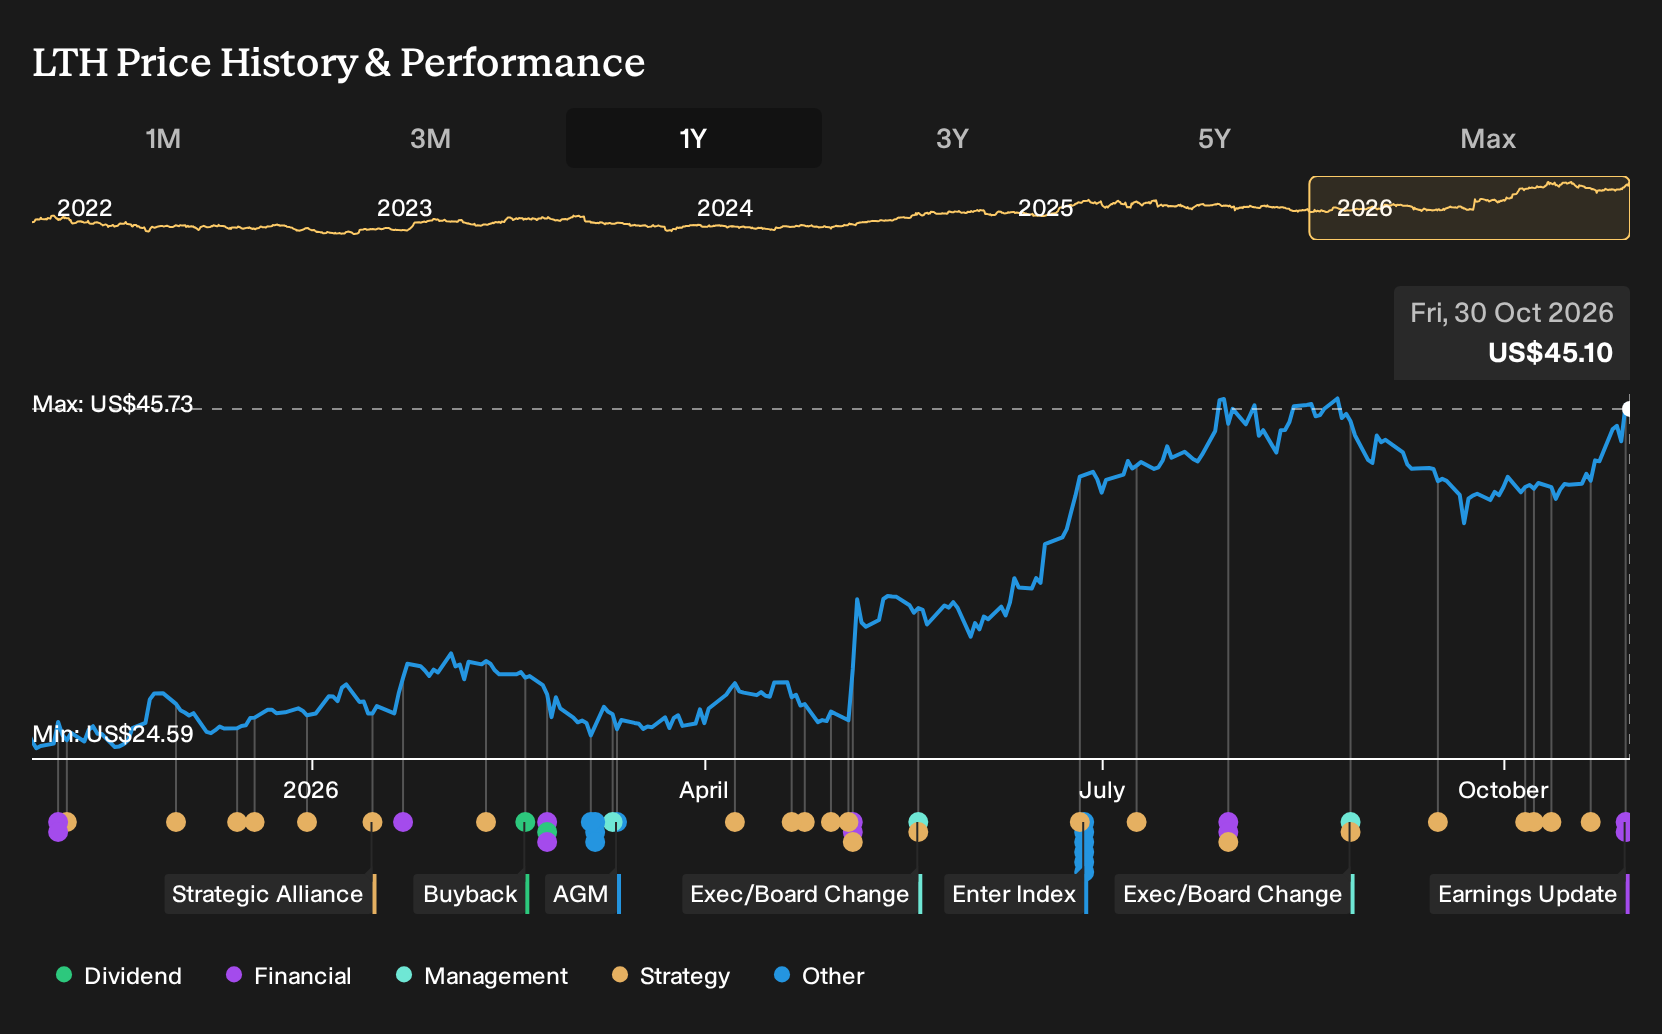
Exploring Other Perspectives
Some of the most optimistic analysts focus on Life Time Group Holdings' premium wellness concepts as a catalyst, not just club openings. Before this quarter, that bullish group was penciling in revenue of about US$4.6b and earnings near US$559.5 million by 2029. These estimates were set before the latest results, so your own view might shift as you weigh this new information.
Explore 3 other Life Time Group Holdings fair value estimates, including one that suggests there could be as much as 47% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Life Time Group Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Life Time Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Life Time Group Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Life Time Group Holdings?
If the Life Time Group Holdings story has sharpened your view on membership driven businesses, you can use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors who want income at the forefront, review companies that have built reputations around steady payouts and yield resilience by checking out 5 dividend fortresses.
- If capital preservation ranks high on your checklist, focus on businesses with sturdier financial profiles through the 29 resilient stocks with low risk scores.
- When you want quality without the spotlight, broaden your watchlist with a 19 high quality undiscovered gems that couples strong fundamentals with less crowded stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com