


J D Wetherspoon (LSE:JDW), What Is Behind The Fresh Attention?
Investor attention around J D Wetherspoon (LSE:JDW) is being driven by an upcoming trading update on Wednesday, 4 November, with sector peers also lining up statements that could sway sentiment.
Recent trading has been strong, with J D Wetherspoon’s share price delivering a 16.1% one month return and 30.0% over the past quarter. The year to date share price gain of 42.9% sits alongside a 67.1% one year total shareholder return that reflects how anticipation around updates can shift both growth expectations and perceived risk.
Scan how J D Wetherspoon’s pre update momentum compares with other consumer names that screen well for quality and valuation using our curated list of 14 high quality undervalued stocks.
After a 42.9% move this year and a share price around £10.62, J D Wetherspoon now trades well above both analyst targets and intrinsic value estimates. Where does fair value really sit within that range?
Price-to-Earnings of 17.9x: Is it justified?
On simple earnings terms, J D Wetherspoon trades on a P/E of 17.9x, which screens as slightly rich versus peers even though the DCF estimate of £7.67 already sits well below the current £10.62 share price.
The P/E ratio compares what investors are paying today for each £1 of earnings and is a common yardstick for consumer and hospitality groups where mature, steady profit streams tend to matter more than high-growth stories.
For J D Wetherspoon, a 17.9x multiple means the market is attaching a reasonably full price to forecast earnings. This is despite comments that earnings are only expected to grow 5.7% per year while revenue is projected to advance 4.3% per year and interest payments are not well covered by profits.
Compared to the UK Hospitality industry average P/E of 18.5x, the stock trades at a small discount. However, it still looks expensive relative to the peer average of 17.1x and to an estimated fair P/E of 14.8x, which is a level the valuation work suggests the market could move towards if enthusiasm around recent share price gains fades.
Explore the SWS fair ratio for J D Wetherspoon.
Result: Price-to-Earnings of 17.9x (OVERVALUED)
Still, a sharp reversal in J D Wetherspoon’s recent share price strength, or a weaker than expected trading update, could quickly challenge this stretched valuation story.
Find out about the key risks to this J D Wetherspoon narrative.
Another View: What Does The SWS DCF Model Say?
The P/E work presents J D Wetherspoon as fully priced. Looking at the company through a different lens adds weight to that concern. Our DCF model points to a value of around £7.67 per share versus the current £10.62 level, which suggests the stock screens as overvalued on projected cash flows.
For readers who want to see how that cash flow based estimate is built line by line, Look into how the SWS DCF model arrives at its fair value.
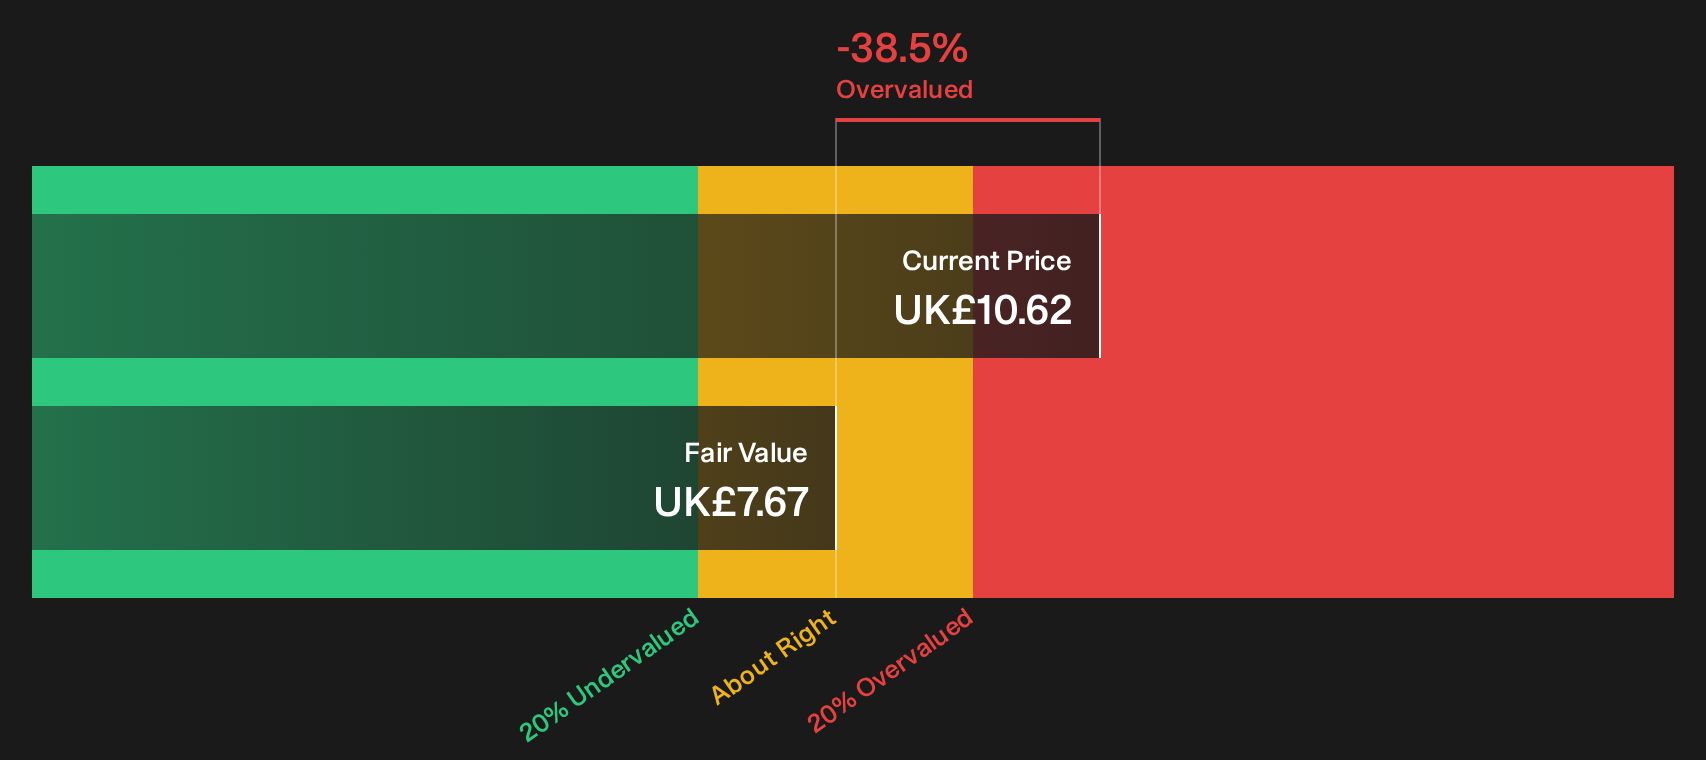
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out J D Wetherspoon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the mix of optimism and concern around J D Wetherspoon feel balanced enough for you to act? If you want to move quickly and ground your own view in the underlying data, take a closer look at the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond J D Wetherspoon?
If J D Wetherspoon has sparked fresh questions about value and risk, use that curiosity to scan wider opportunities and pressure test your next move with hard data.
- Target potential mispricing by reviewing a curated pool of 14 high quality undervalued stocks that pair quality fundamentals with appealing valuations.
- Prioritise resilience and sleep easier at night by checking companies in our 5 resilient stocks with low risk scores that carry lower overall risk scores.
- Get ahead of the crowd by scanning 5 high quality undiscovered gems that combine solid financials with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com